Aircraft Leasing
Logistics Financial Model (Free Excel Download)
Underwrite aircraft-leasing portfolios with deliveries, lease rates, utilization, maintenance reserves, residual values, debt financing, remarketing costs, and levered asset returns.

professionals from Deloitte
Used by professionals from
About this model
An aircraft leasing model captures the cash flows, financing, and equity returns of an operating-lease portfolio from the lessor (equity sponsor) perspective. The workbook lays out a 10-aircraft narrowbody fleet - 50M per aircraft, 500M total cost, an 8-year levered hold - across nine sheets: Cover, Assumptions, Fleet, Lease_Income, Debt, Cash_Flow, Returns, Sensitivity, Checks. Every input is a named-range cell, every formula is one or two operations long, and the workbook passes static-value, self-reference, dead-assumption, and unused-named-range scans.
The Fleet sheet runs the net book value roll-forward. NBV opens at zero, takes the full fleet cost as an acquisition in Year 0, and depreciates by a constant straight-line charge each operating year (cost net of a 15% accounting residual, spread over a 25-year useful life). Closing NBV equals opening plus acquisitions plus depreciation. At the end of the hold the fleet is marked to an exit residual value (72% of original cost), and the gain or loss on sale is the difference between that market value and the depreciated closing book value.
The Lease_Income sheet walks the operating result. Annual rental per aircraft equals the lease rate factor times twelve times aircraft cost; lease revenue equals aircraft on lease (fleet times 96% utilisation) times the annual rental, escalated 1.5% each year. Operating expenses are 8% of revenue; EBITDA is revenue less opex. Depreciation, interest expense, and the gain or loss on sale carry down to pre-tax income, which is taxed at 21% to give net income.
The Debt sheet schedules the senior facility: a 65% loan-to-value drawdown at acquisition (325M), straight-line amortisation over a 12-year schedule, and a balloon repaid from sale proceeds at exit. Interest accrues on the declining opening balance, so debt service falls each year. The Cash_Flow sheet builds operating cash flow (EBITDA less cash taxes less interest), then the levered (equity) cash flow that adds the Year-0 acquisition outflow, debt drawdown, debt repayment, and exit sale proceeds, plus a cumulative equity cash flow and a separate unlevered cash flow view that strips out all debt items.
The Returns sheet reports the levered IRR off the equity cash flow stream (~8.5%), the equity multiple of distributions to equity invested (~1.8x), the average operating cash yield, and the unlevered IRR off the asset cash flow (~4.0%) - with the levered IRR exceeding the unlevered IRR because the debt cost sits below the asset return. The exit summary shows sale proceeds, debt outstanding at exit, net exit equity, and total cash returned to equity. The Sensitivity sheet flexes a 5x5 grid of net lease yield on cost against lease rate factor and utilisation offsets. The Checks sheet runs seven validation checks: debt fully repaid at exit, net book value never negative, equity ties to sources, the Year-0 equity outflow equals equity invested, loan-to-value and utilisation within bounds, and accumulated depreciation reconciles to fleet cost less closing NBV.
Target users are aircraft lessors, aviation finance and structured-finance teams, infrastructure and asset-backed funds, and lenders sizing senior facilities against narrowbody fleets. Useful for acquisition underwriting (does a fleet purchase clear the equity return hurdle), leverage structuring (how loan-to-value and amortisation reshape the equity IRR), and residual-value stress testing (what a soft secondary market at sale does to the equity multiple). Calibrate against lessor 20-F filings from AerCap and Air Lease Corporation, Cirium fleet values, and aircraft appraiser residual-value curves.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Aircraft Leasing
- 10-aircraft narrowbody operating-lease portfolio, 500M fleet cost, 8-year levered hold
- Fleet net book value roll-forward: acquisition, straight-line depreciation, closing NBV
- Exit valuation: market value at 72% residual and gain/(loss) on sale versus book
- Lease income statement: revenue, opex, EBITDA, depreciation, interest, tax, net income
- Senior debt schedule: 65% LTV drawdown, straight-line amortisation, balloon at exit, declining-balance interest
- Operating, levered and unlevered cash flow with cumulative equity CF
- Returns: levered IRR, equity multiple, average cash yield, unlevered IRR, exit summary
- Sensitivity grid: 5x5 lease rate factor by utilisation producing net lease yield on cost
Inside the Aircraft Leasing Model: How Lessor Returns Are Built
This aircraft leasing model evaluates an 8-year operating-lease portfolio from the equity sponsor's perspective: a ten-narrowbody fleet, monthly lease rate factor pricing, senior secured debt amortising to a balloon, and an exit sale at residual value. It shows how the unlevered asset return and levered equity return are separated so the contribution of leverage is explicit.
What Drives the Portfolio's Cash Flow
The model's operating engine rests on a handful of commercial and financing drivers. Lease revenue begins with the lease rate factor, which sets the annual rental per aircraft as a percentage of aircraft cost, and is then scaled by the number of aircraft on lease, reflecting fleet size and utilisation.
- A contractual rent step-up applies during the hold, and a re-leasing event near year seven introduces a transition-downtime utilisation haircut and a re-lease rate step. Operating costs include a maintenance expense driver carrying lessor-funded heavy-check costs, separate SG&A and insurance, and remarketing or transition costs.
- The capital structure is set by loan-to-value, an amortisation period longer than the hold to leave a balloon, and an interest rate applied to the declining balance.
How the Model Calculates Returns
The calculation flow starts with fleet net book value, which opens at zero, takes the full fleet cost in Year 0, and depreciates on a straight line each operating year. Lease income builds revenue from the lease rate factor, utilisation, and rent step-up, then deducts opex, maintenance expense, depreciation, interest, and tax to reach net income.
- Debt is drawn at close based on loan-to-value, amortises on a straight-line schedule, and the remaining balloon is repaid from exit proceeds. The exit value is the exit residual applied to total fleet cost, and gain or loss on sale is the difference between market value and closing net book value.
- Operating, levered, and unlevered cash flow are computed separately, with the unlevered view stripping out all debt items.
Outputs and Sensitivities
The returns sheet reports the levered IRR, equity multiple, average operating cash yield, unlevered IRR, and minimum operating-year DSCR, alongside an exit summary showing sale proceeds, debt outstanding, net exit equity, and total cash returned to equity. A scenario toggle switches among base, downside, and upside cases by altering five live drivers: lease rate factor, utilisation, exit residual, interest rate, and re-lease step.
- A sensitivity sheet flexes exit residual against lease rate factor to show levered IRR and equity multiple grids. Separate maintenance reserve and security deposit mechanics track restricted cash and deposits, which net to zero over the hold.
- Deferred tax timing from accelerated depreciation is also modelled, reversing fully at exit.
Using the Template for Evaluation
This template is useful for understanding how lease rate factor, fleet utilisation, residual value retention, and senior debt structure interact to produce equity returns. The DSCR row and covenant test highlight the operating headroom available to service debt, while the separation of levered and unlevered IRR shows whether leverage is accretive given the spread between asset yield and debt cost.
- Validation checks confirm debt repayment, non-negative book value, equity ties to sources, and reconciliation of accumulated depreciation. The public download is a values-only preview; it illustrates the modelled relationships but does not contain live formulas or automatic recalculation.
- Use it to assess the logic of the structure rather than as a production underwriting tool.
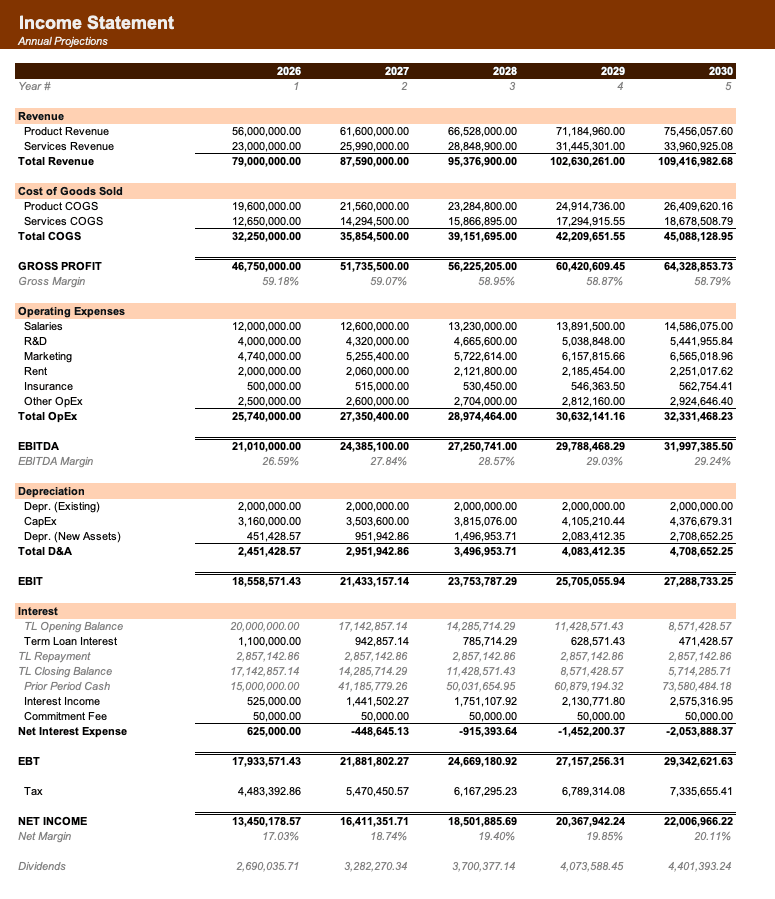
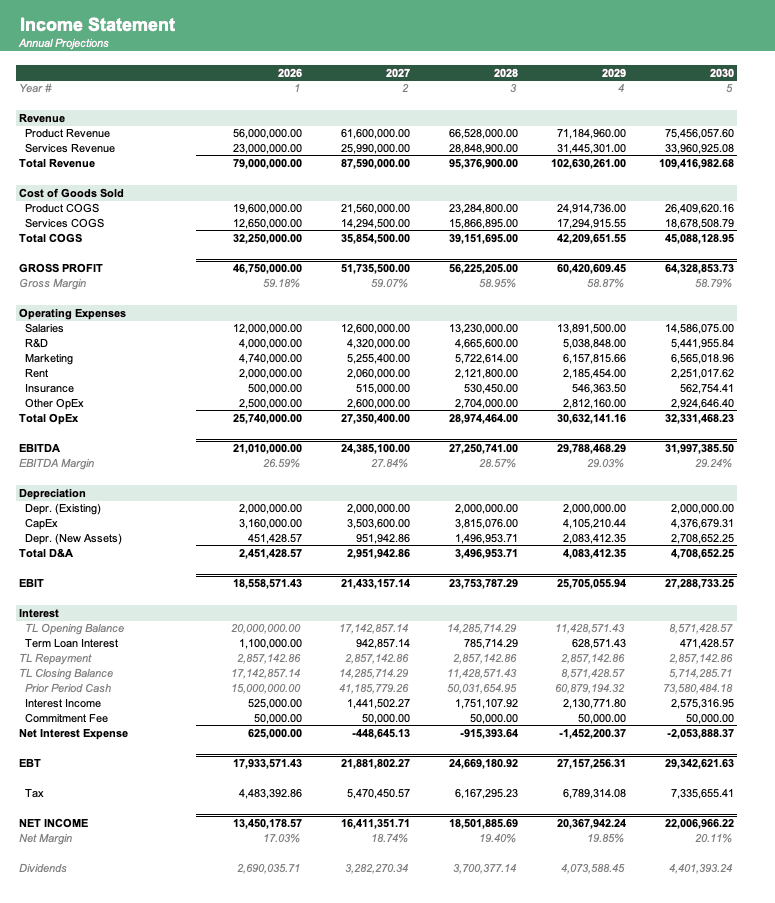
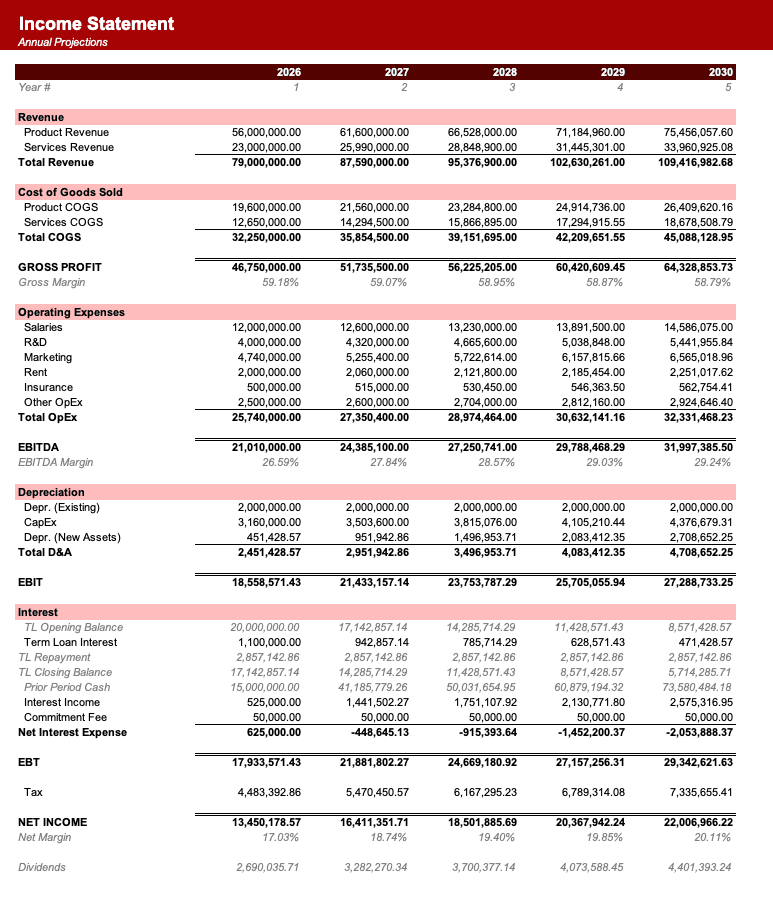
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is an aircraft operating lease?+
An operating lease is a medium-term rental of an aircraft to an airline. The lessor keeps ownership and the residual-value risk, while the airline pays a fixed monthly rental and returns the aircraft at lease end. This template takes the lessor view across a portfolio of 10 narrowbody aircraft over an 8-year hold.
What is the lease rate factor?+
The lease rate factor is the monthly lease rental expressed as a percentage of aircraft cost. A 0.95% monthly factor on a 50M aircraft implies a 5.7M annual rental. New narrowbody lease rate factors typically run 0.80 to 1.00% per month.
Why is the levered IRR higher than the unlevered IRR?+
Because the senior debt cost of 5.5% sits below the unlevered asset return, leverage is accretive. Borrowing at a rate lower than the asset earns amplifies the equity return. The model reports both the levered and unlevered IRR so the contribution of debt is explicit.
How is the senior debt repaid?+
Debt is drawn at acquisition at 65% loan-to-value, amortises straight-line over a 12-year schedule, and the balance still outstanding at the end of the 8-year hold is repaid as a balloon from the sale proceeds. Interest accrues on the declining opening balance.
What drives the exit value?+
Exit proceeds equal the exit residual value, 72% of original cost, times total fleet cost. The gain or loss on sale is the difference between that market value and the depreciated book value, and it flows through pre-tax income in the exit year.
Can I resize the fleet or change the hold?+
Yes. The number of aircraft, aircraft cost, and hold period are named-range inputs. The builder is parameterised by NUM_PERIODS, currently 9, equal to Year 0 plus an 8-year hold. Bump it together with the Hold Period assumption to extend the horizon.
Have more financial modelling questions? Contact us
Related templates
Equipment Leasing Model
Financial model for equipment leasing cash flows, accounting treatment, and lessor/lessee analysis.
Sale-Leaseback Real Estate Model
Financing model for property owners selling real estate to investors and leasing it back, with lease terms, IRR, and tax deferral analysis.
Airline Operations Model
Airline financial projections with route, fleet, and capacity planning.
Car Rental Economics Model
Vehicle fleet rental financial projections with utilization and rate dynamics.