Home Builder Operating Model
Real Estate Financial Model (Free Excel Download)
Plan home-builder profitability through lots, starts, selling prices, absorption, construction costs, cycle times, debt draws, inventory, and project-level cash flow.

professionals from Deloitte
Used by professionals from
About this model
This model helps you assess a home-building project from land purchase through construction and sale. It brings build timing, unit mix, selling prices, and sales pace together with development costs, financing, and the cash needed throughout the project.
Use it to compare sites, test different build plans, or review an investment opportunity. The model shows how construction costs, sales timing, and pricing affect project cash flow and returns.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Home Builder Operating Model
- Active community panel: Y1-Y5 vector of active communities
- Segment mix: entry-level, move-up, luxury share of communities
- Per-community deliveries by segment (entry > move-up > luxury absorption)
- ASP by segment with annual ASP growth applied uniformly
- Home gross margin by segment (entry < move-up < luxury)
- Financial services attach rate, revenue per loan, and FS gross margin
- P&L drivers: SG&A %, D&A %, effective tax rate
- Capital structure: inventory turns, debt-to-capital, cost of debt, starting equity, starting debt
Home Builder Financial Operating Model: A Plain-Language Guide
This home builder model is a five-year operating template that connects community growth, closings, pricing, and costs to financial statements and return metrics. It is built for analysts, CFOs, and deal teams who need to see how active-community decisions flow through revenue, margins, cash generation, and returns on capital.
Operating Drivers: Communities, Deliveries, and Pricing
The model begins with an active-community trajectory entered year by year. That total is split into entry, move-up, and luxury segments using a fixed mix.
- For each segment, deliveries per community are multiplied by the number of active communities to give closings. Average selling price per segment starts from a baseline and grows annually at a set rate.
- This structure lets you flex community count, segment exposure, delivery pace, and pricing independently, and see how those choices combine into total closings and revenue. Because the mix and per-community delivery assumptions are explicit, the model avoids hiding volume or price effects inside a single growth rate.
Calculation Flow: From Revenue to Net Income
Homebuilding revenue is the sum of segment closings multiplied by segment average selling price. Financial-services revenue comes from total closings times an attach rate and revenue per loan.
- Cost of sales for each segment is the segment revenue times one minus its gross margin; financial-services cost of sales follows the same logic using its own margin. Subtracting costs from total revenue gives gross profit.
- SG&A and D&A are then calculated as percentages of total revenue. The result is EBITDA, then EBIT after D&A.
Interest expense is based on average debt. Tax applies to positive pre-tax income, yielding net income.
Outputs: Inventory, Leverage, and Return Metrics
The model derives inventory from total revenue divided by inventory turns, so the balance sheet scales with the top line. Total debt is inventory multiplied by a debt-to-capital ratio, and interest expense links back to the P&L from the prior debt balance.
- NOPAT is EBIT times one minus the tax rate. Return on invested capital is NOPAT divided by inventory, while return on equity is net income divided by average equity.
- Equity rolls forward from opening equity plus net income, with dividends defaulting to zero. These outputs help you evaluate capital efficiency and leverage alongside earnings.
Practical Use: Flexing Assumptions and Checking Consistency
This template is most useful for testing how changes in community growth, segment mix, pricing, margins, financial-services attach, inventory turns, and leverage affect fifth-year EBITDA, ROIC, and ROE. The related dashboard collects headline metrics and shows traffic-light status against user-set thresholds.
- Built-in checks confirm that the P&L ties out, that segment gross margins sum to the reported home gross margin, and that total closings equal the sum of segment closings. The model follows common homebuilder conventions, such as presenting costs as positive figures and subtracting them in formulas.
- Revenue, COGS, and margin relationships stay transparent, so you can trace each result back to its driver.
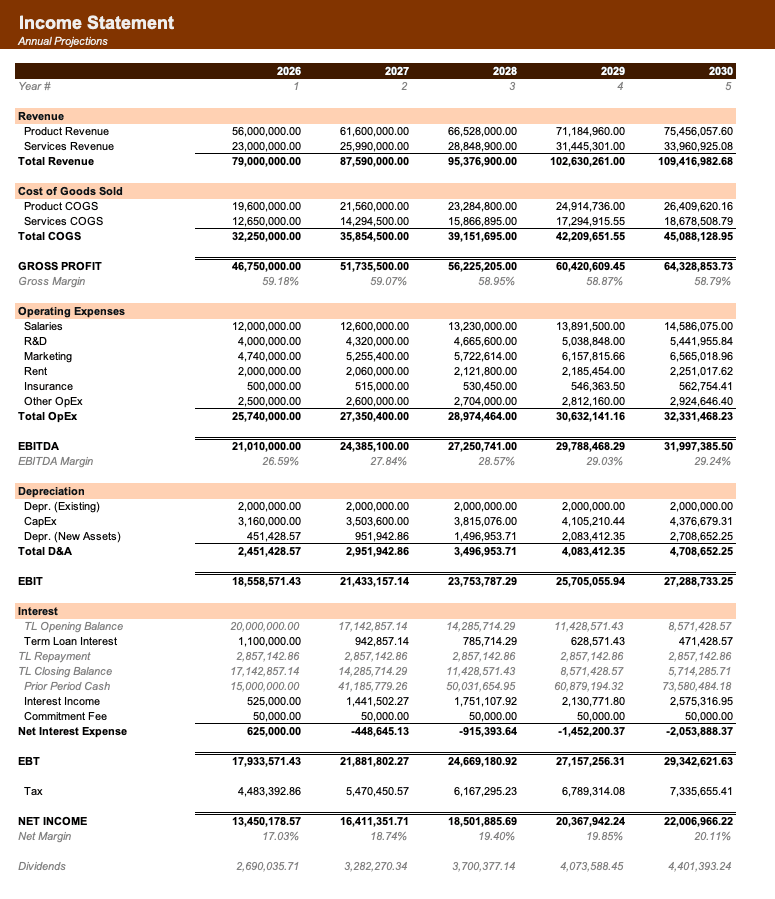
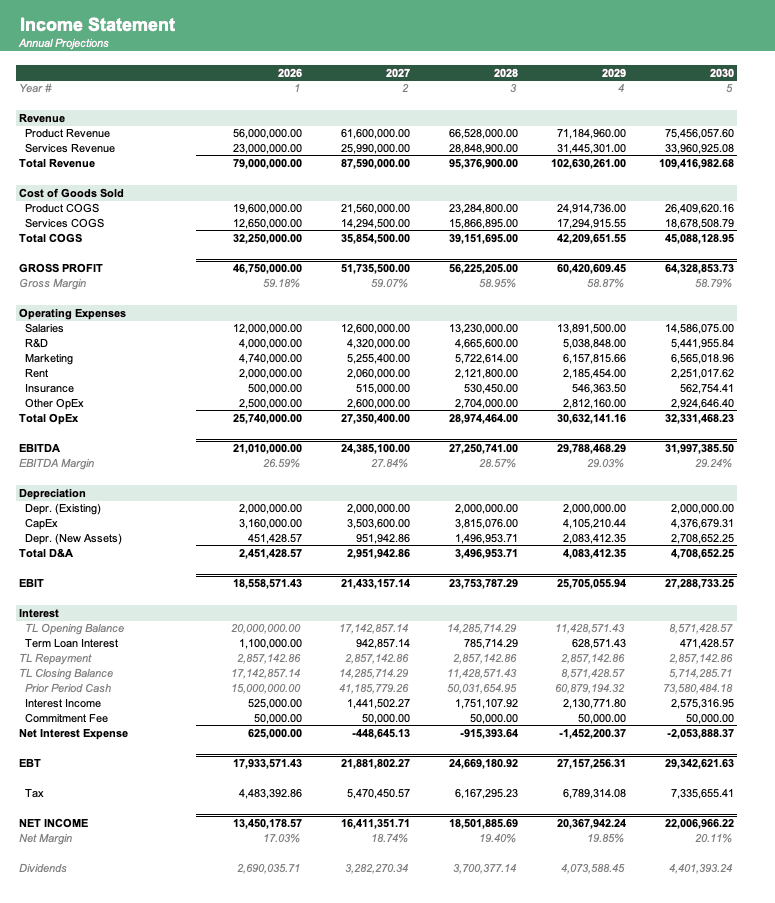
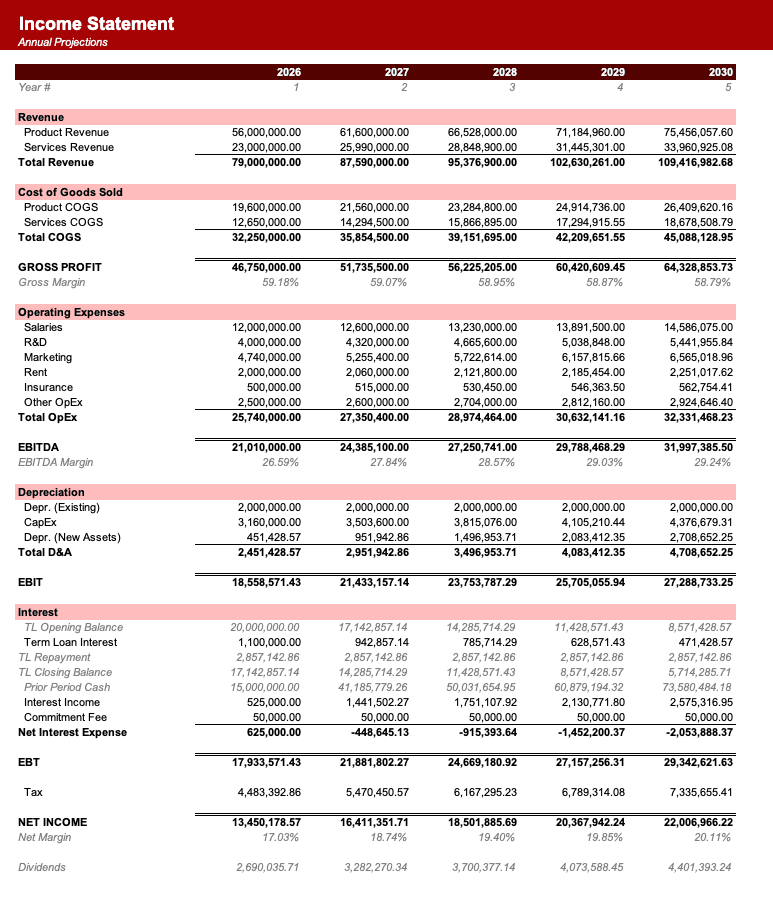
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a home-builder operating model?+
A home-builder operating model captures the five-year operating economics and capital returns of a public-style production homebuilder (D.R. Horton, Lennar, Pulte, NVR, KB Home, Toll Brothers). It drives an active community panel through buyer-segment closings, ASP, home gross margin, SG&A, EBITDA, and a NOPAT / inventory ROIC plus average-equity ROE. It is how equity research analysts, public-builder CFOs, and housing-sector PE underwrite forward home GM and ROIC.
Why split by buyer segment?+
Entry-level, move-up, and luxury buyers have very different absorption rates, ASPs, and gross margins. Entry-level absorbs ~30 deliveries per community per year at lower ASP and lower GM; luxury absorbs ~12 per community at higher ASP and higher GM. Modelling them together as a blended ASP and blended GM hides the mix shift that drives most actual public-builder margin movement through cycle.
How is interest expense calculated?+
Interest expense in year t equals prior-period (year t-1) closing debt × cost of debt. For year 1, the prior period is the user-set starting debt assumption on the Assumptions sheet. Debt itself is sized as inventory × debt-to-capital ratio, where inventory = total revenue / inventory turns. This avoids circularity - interest does not reference current-period debt which depends on revenue which depends on closings.
Why is ROIC NOPAT over inventory, not over invested capital?+
Production homebuilders disclose ROIC against inventory because inventory (land + work-in-process + finished homes) is the dominant capital base - PP&E and other invested capital are minor. NVR famously runs ROIC at 30%+ on this measure because of its asset-light land-option model; D.R. Horton and Lennar typically land at 14-20% ROIC. The model follows the public-builder filing convention so the output is comparable.
Can I extend it to a full 3-statement model?+
Not directly. This template is operating + capital-efficiency only - it does not produce a full balance sheet, cash flow statement, or land-pipeline build. For full 3-statement mechanics with land position roll-forward, layer the 3-statement template on top - point its revenue and EBITDA lines at this model's P&L sheet.
Have more financial modelling questions? Contact us
Related templates
Real Estate Development Pro Forma Model
Land cost, construction budget, lease assumptions, and project IRR for commercial and residential development.
Development Pro Forma
Real estate development underwriting model with lot acquisition, construction, presales, and cash flow timing.
Land Banking Model
Financial model for land acquisition, holding, and exit strategies with development timing optimization.
Hotel Operating Model
Operating model for hotel properties including occupancy rates, average daily rate (ADR), RevPAR optimization, and facility-level profitability.


