Neobank Operating Model
Banking Financial Model (Free Excel Download)
Forecast neobank growth from customers, deposits, card spend, interchange, lending balances, net interest margin, credit losses, operating costs, and funding needs.

professionals from Deloitte
Used by professionals from
About this model
This model helps you plan a digital bank from customer acquisition through deposits, lending, revenue, costs, and capital. It shows how changes in growth, retention, lending activity, and product mix affect profitability over time.
Use it to test the trade-offs between investing for growth and maintaining a healthy capital position. It is built for founders, finance teams, investors, and anyone evaluating a digital banking business.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Neobank Operating Model
- Customer cohort panel: new customers, annual churn, deposit / loan / fee per customer for Y1-Y5
- Rate block: loan rate, deposit rate, central-bank policy rate, cost of risk basis-points charge
- Customers sheet with opening, new, churned, closing, average, cumulative acquired
- Balance sheet: Loans, Cash (Central Bank residual), Customer Deposits, Equity rollforward, Total Assets and L+E
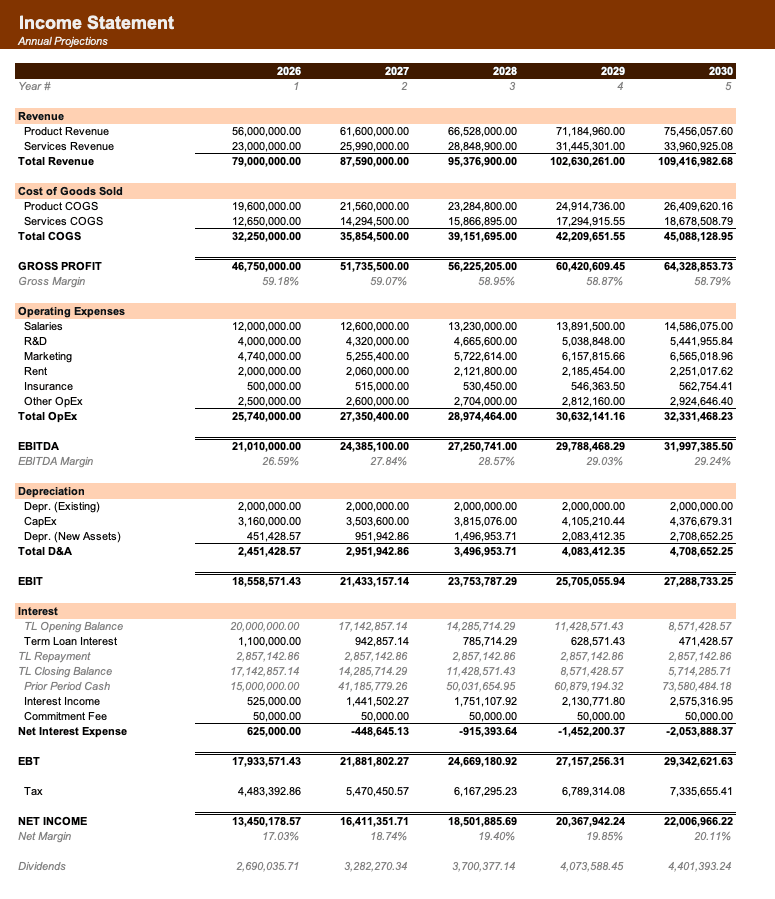
- Income statement: NII (loan interest + cash yield − deposit interest), Fee Income, CAC, Opex, Loan Loss, Tax, Net Income
- Cash flow statement: CFO from Net Income, CFI on loan and deposit growth, CFF from equity raise, closing cash
- Capital sheet: RWA at 75% retail risk weight, CET1 actual %, CET1 minimum, CET1 buffer in pp
- Returns: Net Interest Margin, Cost-to-Income, ROA, ROE, CAC payback months, customer LTV, LTV/CAC
Neobank Operating Model: Customer Cohorts, Net Interest Margin and Capital
This neobank model projects a digital challenger bank from launch to Year 5, linking customer acquisition and churn to deposit and loan balances, revenue, costs and regulatory capital. It is built for founders, finance teams and investors who need to test how growth, lending mix and equity raises interact before committing to a plan.
How Customer Growth and Balances Drive the Business
The operating engine begins with customer cohorts: each year adds a count of new customers, an annual churn rate is applied, and a closing customer count is derived. Cumulative acquired customers are tracked alongside closing customers.
- Per-customer deposit and loan balances then scale with that closing count, so balance sheet size follows acquisition and retention rather than being set independently. Fee income per customer is also applied to the average customer base.
- The specification shows the deposit-to-loan ratio narrowing over time, from a deposit-heavy starting point toward a more balanced relationship as lending layers on. That progression matters because it shifts the earnings mix from fee and cash yield toward interest income, while also increasing risk-weighted assets and the capital needed to support them.
From Balances to Profit: Revenue, Costs and Provisions
Revenue is assembled from net interest income plus fee income. Interest income is calculated on average loans at a loan rate, interest expense on average deposits at a deposit rate, and cash held at the central bank earns a policy rate.
- Fee income is average customers multiplied by fee per customer. Costs are split into customer acquisition spend, fixed operating costs that grow at a declining rate, variable operating cost per customer, and a loan-loss provision charged as a percentage of average loans.
- Pre-tax profit subtracts all of these from revenue, and tax is applied only when pre-tax profit is positive, so losses do not generate a tax shield in the model.
Balance Sheet and Capital Adequacy
The balance sheet derives deposits and loans from closing customers and per-customer balances. Risk-weighted assets apply a uniform retail risk weight to loans, while cash is the residual funding after loans and earns the policy rate without a credit risk weight.
- Equity rolls forward from an initial founding raise, adding net income and any scheduled equity raise. The capital section calculates CET1 required as risk-weighted assets multiplied by a minimum ratio, CET1 actual as equity divided by risk-weighted assets, and the buffer as the difference.
- The model assumes equity is the only CET1 capital source, so a growing loan book can erode the buffer and require a raise to stay above the minimum.
Returns, Scenarios and Validation
The returns view summarises net interest margin, cost-to-income, return on assets, return on equity, customer acquisition cost payback and lifetime value to acquisition cost, using the model's own revenue and cost relationships.
- A scenario selector applies a scalar to new-customer counts for base, bull and bear cases, which changes cumulative customers and the pace of capital consumption.
- Validation checks confirm that the balance sheet balances, customer counts reconcile with cohort arithmetic, terminal CET1 is above the minimum, net interest margin sits in a plausible range, cumulative customers never decrease, and scheduled equity injections appear when equity grows.
- Together these give a structured way to test growth and capital trade-offs.
Formatted to IB standards
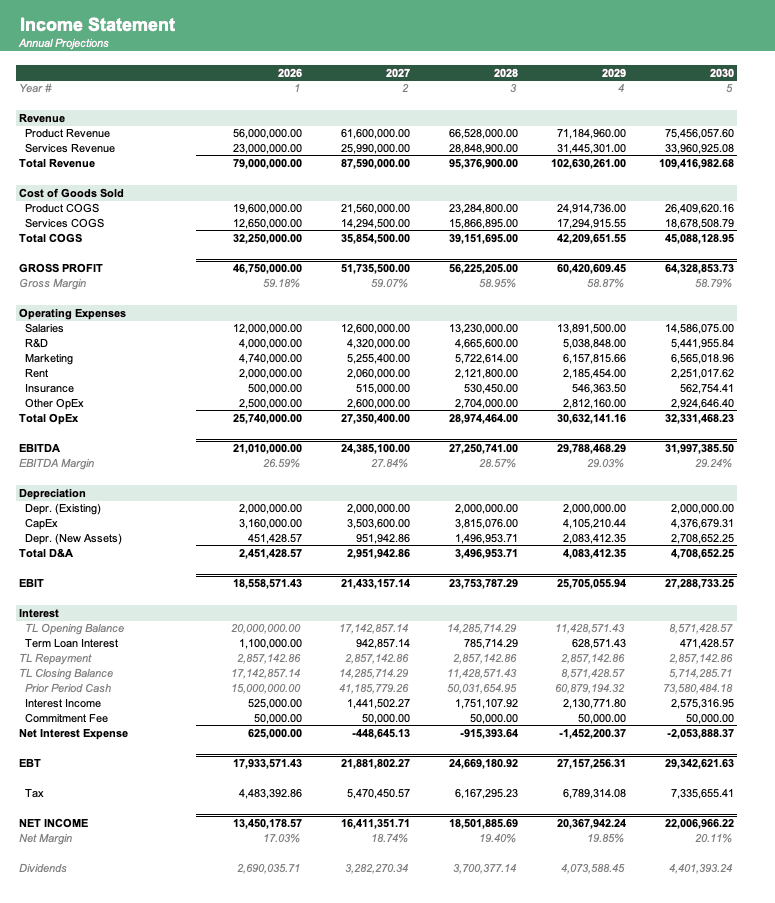
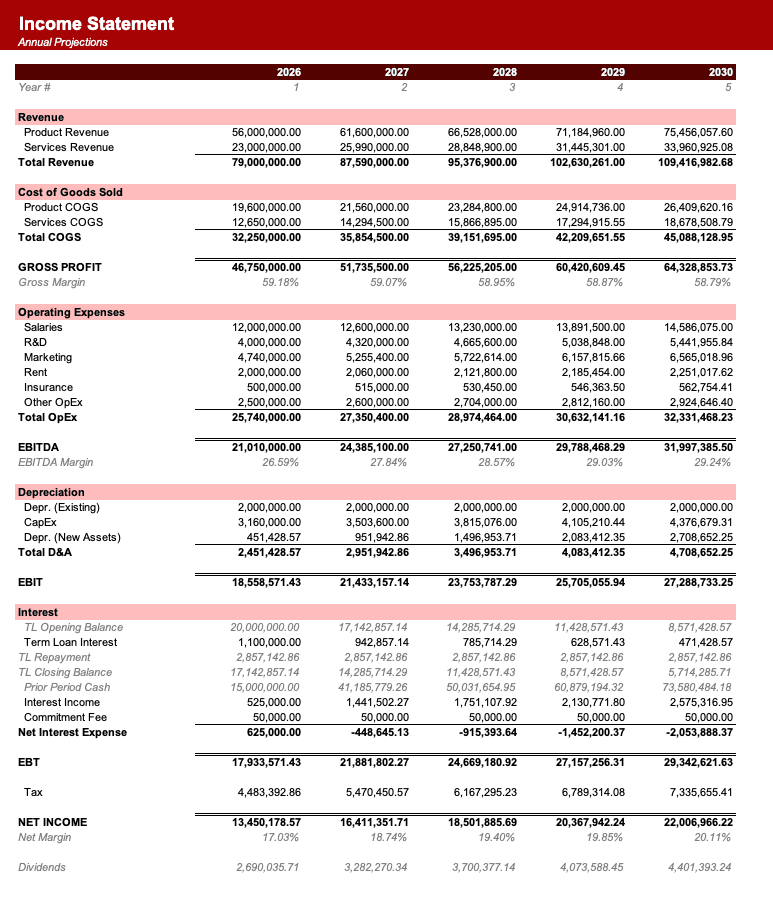
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a neobank operating model?+
A neobank operating model is a 3-statement plus capital-adequacy forecast for a digital-only bank (Revolut, Monzo, Starling, N26, Bunq, Chime). It translates customer cohort acquisition into the bank balance sheet, then runs the income statement on Net Interest Margin and Cost-to-Income, and verifies the CET1 capital ratio stays above the Basel IV minimum across the projection.
Why does cash yield use opening (not average) cash?+
Average cash creates a circular dependency: BS Cash depends on Equity Close, which depends on Net Income, which depends on Cash Yield, which would depend on average BS Cash. Using opening cash (Initial Equity in Year 1, prior closing thereafter) breaks the loop cleanly without an iterative calculation toggle. This is the institutional convention for bank operating models.
How is RWA computed?+
Risk-weighted assets equal loan balance times a 75% retail risk weight (Basel IV standardised approach). Cash held at the central bank carries a zero risk weight in this stylised model - earning the policy rate but consuming no capital. A more granular model would split RWA by product (mortgages 35%, SME 75%, unsecured 100%).
What does the scenario selector do?+
Scenario_Sel (1=Base, 2=Bull, 3=Bear) runs a CHOOSE() over three customer-acquisition scalars (1.00x, 1.25x, 0.75x). The selected scalar multiplies every year new customer count. Flipping the cell on Assumptions recomputes the entire model in one keystroke.
Can I extend it to multi-currency or banking-as-a-service?+
Not directly. The template is single-currency USD with one blended loan product, one blended fee per customer, and equity as the only CET1 source (no AT1 / Tier 2 issuance). To layer banking-as-a-service, add a non-customer revenue line (API call volume × take rate) on the income statement and a deferred-revenue working-capital item if invoicing on contracted MRR.
Have more financial modelling questions? Contact us
Related templates
Bank Capital Adequacy Model
Regulatory capital calculations and stress testing for banks.
Fintech Payments Platform Model
Unit economics model for payments fintech with transaction volume, take rate, and customer cohorts.
Bank Loan Analysis Model
Commercial bank loan origination and portfolio underwriting.
Credit Card Portfolio Model
Model credit card loan losses, interest revenue, and regulatory capital requirements.