Revenue-Based Financing
Credit Financial Model (Free Excel Download)
Evaluate non-dilutive growth capital by linking revenue performance, repayment obligations, cash costs, funding capacity, and investor returns under alternative structures.

professionals from Deloitte
Used by professionals from
About this model
Revenue-based financing is repaid as a share of a company's sales, so the pace of repayment depends on how the borrower performs. This model helps lenders and founders see the relationship between revenue growth, repayment terms, and time to payback.
Use it to assess an individual advance or a portfolio of originations. You can test how pricing, repayment rates, funding costs, and credit losses affect the economics before committing capital.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Revenue-Based Financing
- Borrower revenue path: Month-1 base plus monthly growth compounded across 36 months
- Advance terms: advance amount, factor multiple, remit percent of revenue, term cap
- 36-month single-advance roll-forward: revenue, remit due, opening balance, term-capped remit, actual remit, closing balance, cumulative repaid, payback flag, provider net cash flow
- 24-month rolling-cohort portfolio with 12 cohort rows convolved against the single-advance curve via INDEX
- Portfolio aggregates: new advances, total outstanding, gross remittance, default losses, net remittance, funding cost, opex, provider net margin
- Returns: realised MOIC, payback period via MATCH, weighted-average life via SUMPRODUCT, monthly IRR, annualised IRR
- Portfolio returns: gross and net MOIC, realised loss rate, provider net margin
- Spread block: single-advance annualised IRR less cost of funds, opex drag, expected loss
Revenue-Based Financing Model: How the Template Works
This revenue based financing model template lets you examine how an advance repaid through a share of monthly sales behaves. It covers single deals and a 24-month portfolio of originations, showing the link between borrower growth, repayment terms, and the provider's returns.
The model helps you evaluate cash timing, risk, and break-even conditions before committing capital.
Inputs and Operating Drivers
The Assumptions sheet sets the drivers for both a single advance and a rolling portfolio. For the borrower, you enter starting monthly revenue and a growth rate, which together shape how quickly the remittance grows.
- For the advance itself, you specify the amount, the factor multiple, the remit percentage, a term cap in months, and an origination fee. Portfolio inputs add the number of deals per month, an origination window, and a facility size.
- Risk inputs include a default rate, loss given default, and a recovery lag. Provider economics add a cost of funds and an operating expense percentage.
Four stress multipliers and sensitivity axis bounds allow scenario adjustment. All inputs are entered as positive numbers.
Calculation Flow from Single Advance to Portfolio
Each month, the borrower's revenue grows from its starting base, and the remit due equals that revenue multiplied by the remit percentage. The repayment cap is the advance amount times the factor, so total contractual repayment stops once the outstanding balance is cleared.
- Actual remittance is the lower of the remit due and the remaining balance; once the balance reaches zero, remittance ends. A hard term cap limits payback to a fixed number of months.
- If the borrower's revenue is too low or the remit percentage too small, the deal may not reach the factor within the term cap, and the shortfall is reported as a term-cap loss on the Returns sheet.
- The single-advance schedule is the building block for the portfolio. Each monthly cohort follows the same repayment curve, scaled by the number of deals and offset by its origination month.
- Portfolio aggregates track facility utilisation, defaults, recoveries, funding cost, operating expense, and net margin. Defaults reduce net outstanding through a cumulative corkscrew, while recoveries arrive with a lag and are added back as cash.
The portfolio section also compares new advances, cumulative originations, and facility drawn to ensure the warehouse limit is respected.
Outputs: Returns, Vintages, and Stress Views
The Returns sheet brings together the key economics for the single advance and the portfolio. For a single deal, it shows the money multiple and payback month, along with a flag for whether payback was achieved, the realised factor versus the contracted factor, any term-cap loss, the weighted-average life, and both monthly and annualised internal rates of return.
- Portfolio outputs include gross and net money multiples, default losses, recoveries, realised loss rate, provider net margin, and peak facility utilisation. A spread block compares the single-advance internal rate of return against cost of funds, operating expense, and expected loss.
- The Vintages sheet provides per-cohort returns for up to 12 vintages, showing gross and net internal rates of return, money multiples, and payback, with each vintage truncated to the months remaining inside the 24-month observation window. The Stress sheet tests five scenarios: higher default rates, a higher loss given default, slower growth, and a combined worst case.
It also reports a break-even default rate and a break-even cost of funds. Stress figures use a linear money-multiple yield, which is mechanically lower than the periodic internal rate of return for an amortising stream, so they serve as a conservative read on outcomes.
Practical Use and Validation
This template is useful when you need to assess how repayment pace and returns move together. A lender can vary the remit percentage, factor multiple, or borrower growth to see the effect on payback time and realised money multiple.
- The portfolio section supports testing how origination volume, facility size, and default assumptions interact, including whether net outstanding stays within the facility limit. The stress table helps identify break-even thresholds, such as the default rate or cost of funds at which provider economics turn negative.
- The checks sheet validates structural identities, including repayment cap, remit bounds, non-negative balances, factor minimum, term-cap consistency, facility breach, and recovery-lag bounds.
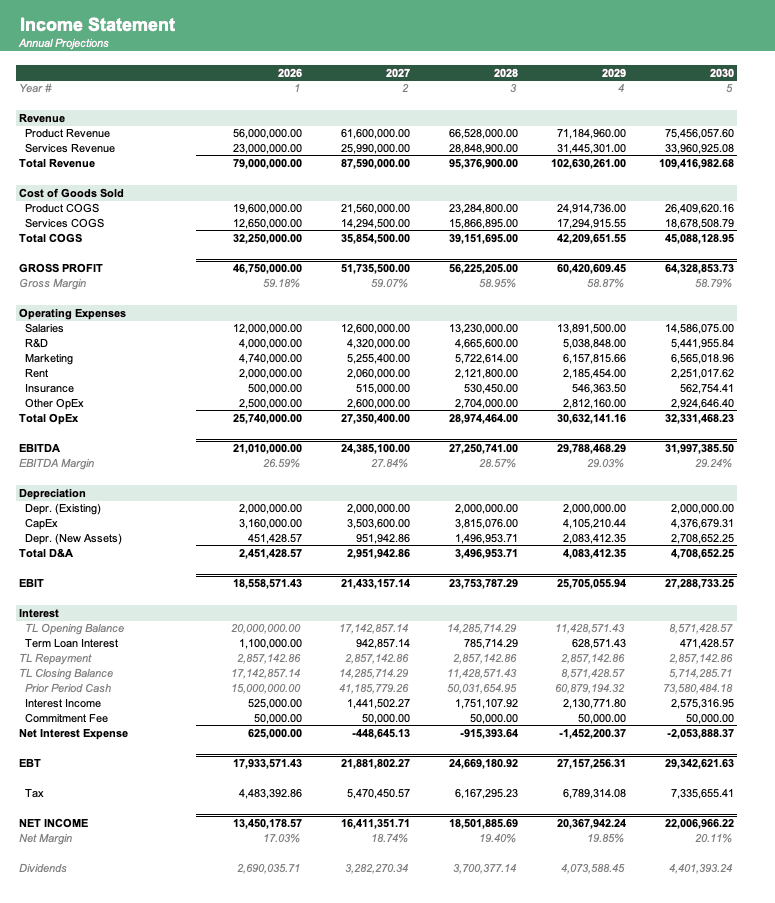
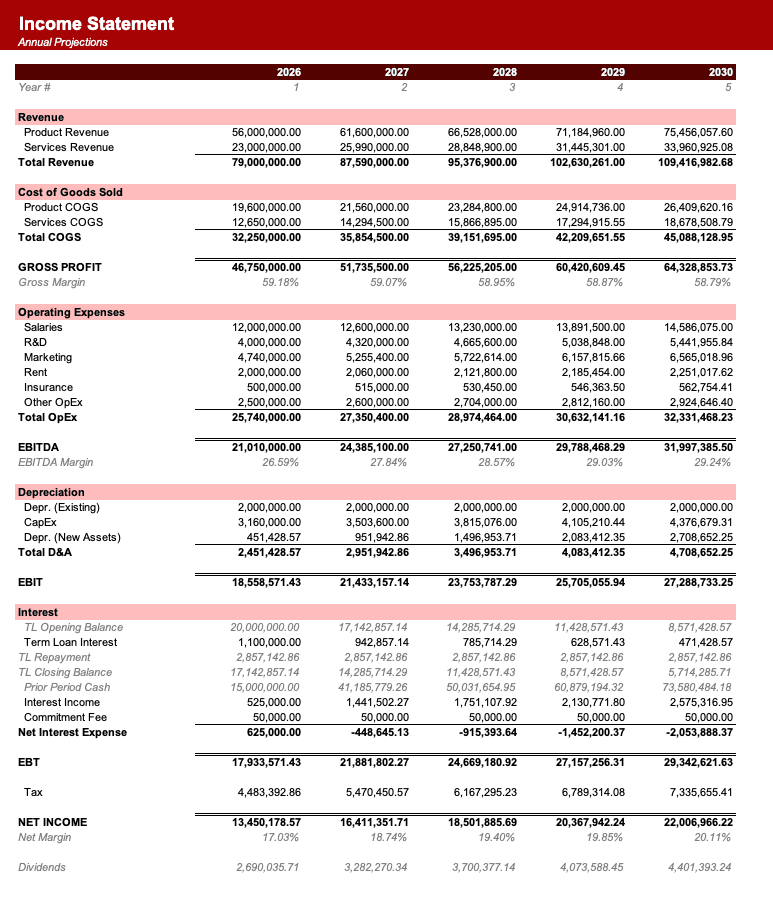
Formatted to IB standards
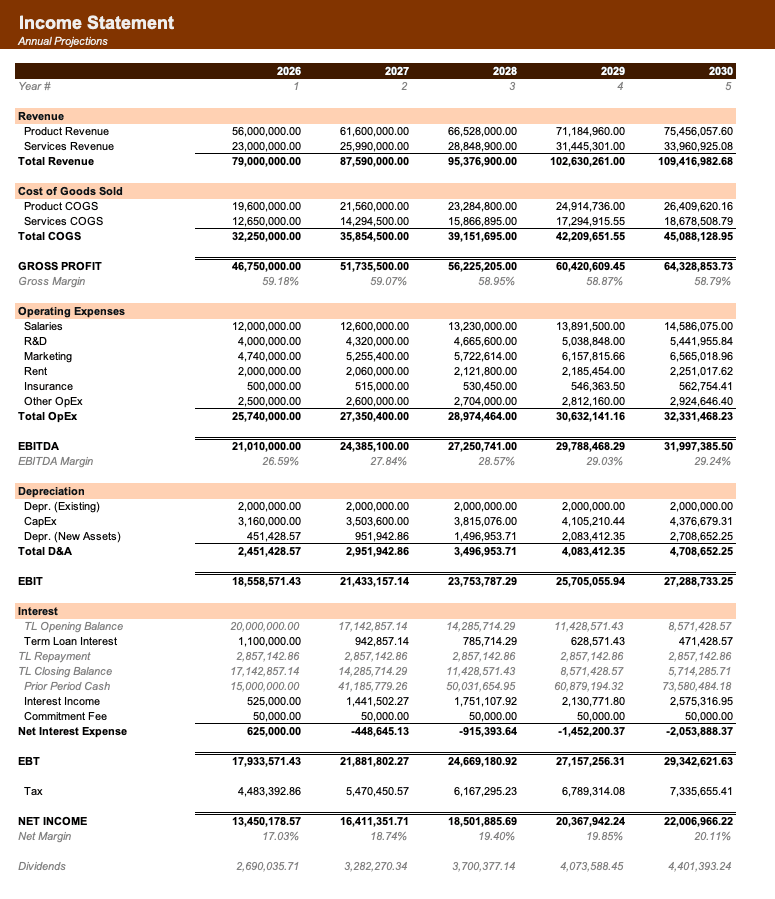
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is revenue-based financing?+
Revenue-based financing (RBF) is a non-dilutive alternative to debt and equity where a provider pays an upfront cash advance to a recurring-revenue borrower and recovers a fixed multiple of the advance - the factor - by collecting a percentage of the borrower's monthly revenue until either the cap is reached or a hard term cap binds. Pipe, Capchase, and Clearco are the well-known platforms; the structure is common across SaaS, ecommerce, and DTC.
How is RBF different from factoring or a term loan?+
Factoring is invoice-by-invoice: the provider buys specific receivables at a discount. A term loan amortises on a fixed schedule with explicit interest. RBF has no schedule and no interest - the repayment timing is set by the borrower's revenue, the total repayment is fixed at advance × factor, and the provider's IRR depends on how quickly the revenue gets there.
Why does my portfolio MOIC look low?+
The 24-month portfolio horizon catches most cohorts mid-payback - late cohorts originated in months 9–12 only see 12–15 months of remit before the window closes. The single-advance MOIC on the Returns sheet (which runs to month 36) is the steady-state number. Extend the portfolio horizon (PORT_PERIODS in the builder) if you need to see the book fully unwind.
Does the model handle defaults explicitly?+
Partially. Defaults are computed as outstanding × annual default rate / 12 × LGD and netted on the Net Remittance line. The model does not simulate default timing (typically months 6–18 in real RBF books) or separate recovery cash flows - recoveries are folded into the LGD. For a default-timing-aware build, pair with the abs-clo or loan-portfolio-cdr templates.
Can I extend the advance horizon or portfolio window?+
Yes. The builder is parameterised by ADV_PERIODS (36) and PORT_PERIODS (24). Bump either, rerun, and the cohort matrix, returns metrics, and sensitivity grid all extend automatically. The sensitivity closed-form is bounded by Adv_Term_Cap, so update that on Assumptions if you push ADV_PERIODS up.
Have more financial modelling questions? Contact us
Related templates
Factoring Program Model
Financial model for accounts receivable factoring with advance rates, discount fees, and portfolio metrics.
Direct Lending Fund Model
Financial model for direct lending fund with loan origination, yield, losses, and fund returns.
Buy Now Pay Later Model
BNPL fintech platform financial projections.
Auto Loan Portfolio Model
Automotive loan securitization and portfolio analysis.