Startup Valuation Methods: How to Value a Pre-Revenue or Early-Stage Company
Key Takeaways
- There is no single correct startup valuation - only a defensible range. Triangulate with two or three methods and let them converge.
- Match the method to the stage. Berkus and Risk Factor Summation for idea/prototype; Scorecard when a market benchmark exists; the VC Method once there is early revenue and an exit thesis; DCF and revenue comps only when cash flows are forecastable.
- Pre-money vs post-money is the number that actually matters. Post-money = pre-money + investment, and investor ownership = investment ÷ post-money. Always clarify whether a quote is pre- or post-pool.
- The VC Method is exit value ÷ target multiple. It converts a hoped-for exit and a required MOIC into today's valuation - and a 10× over 5 years quietly demands a ~58% annual return.
- Dilution is borrowed against today's price. Apply a retention ratio in the VC Method, and model founder ownership across every round before you sign.
- Watch the terms, not just the headline. Option pools, liquidation preferences, and time-to-exit assumptions can move the real economics more than the pre-money number does.
- Build it in a cap table. Every method's output has to reconcile to share counts, ownership percentages, and dilution - do that math in Excel, not in your head.
For the forecast that feeds your exit assumptions, start with our startup financial model guide, and model the ownership mechanics with the free cap table template.
Startup valuation is the art of putting a defensible number on a company that may have little or no revenue, no profits, and years of uncertainty ahead. There is no single "right" answer - instead, investors and founders lean on a handful of methods (Berkus, Scorecard, Risk Factor Summation, the Venture Capital method, and DCF/comps) and triangulate a range. This guide walks through each method with worked numbers, explains the pre-money vs post-money and dilution math that every negotiation hinges on, and shows how to pull it all into an Excel cap table.
Valuing an early-stage startup is fundamentally different from valuing a mature public company. A DCF wants years of predictable cash flow; a comps analysis wants profitable peers with clean multiples. A pre-revenue startup offers neither. So the methods below are deliberately blunt: they price the quality of the risk reduction a team has achieved, or they work backwards from a hoped-for exit. The goal is never precision - it is a range you can defend across the negotiating table.
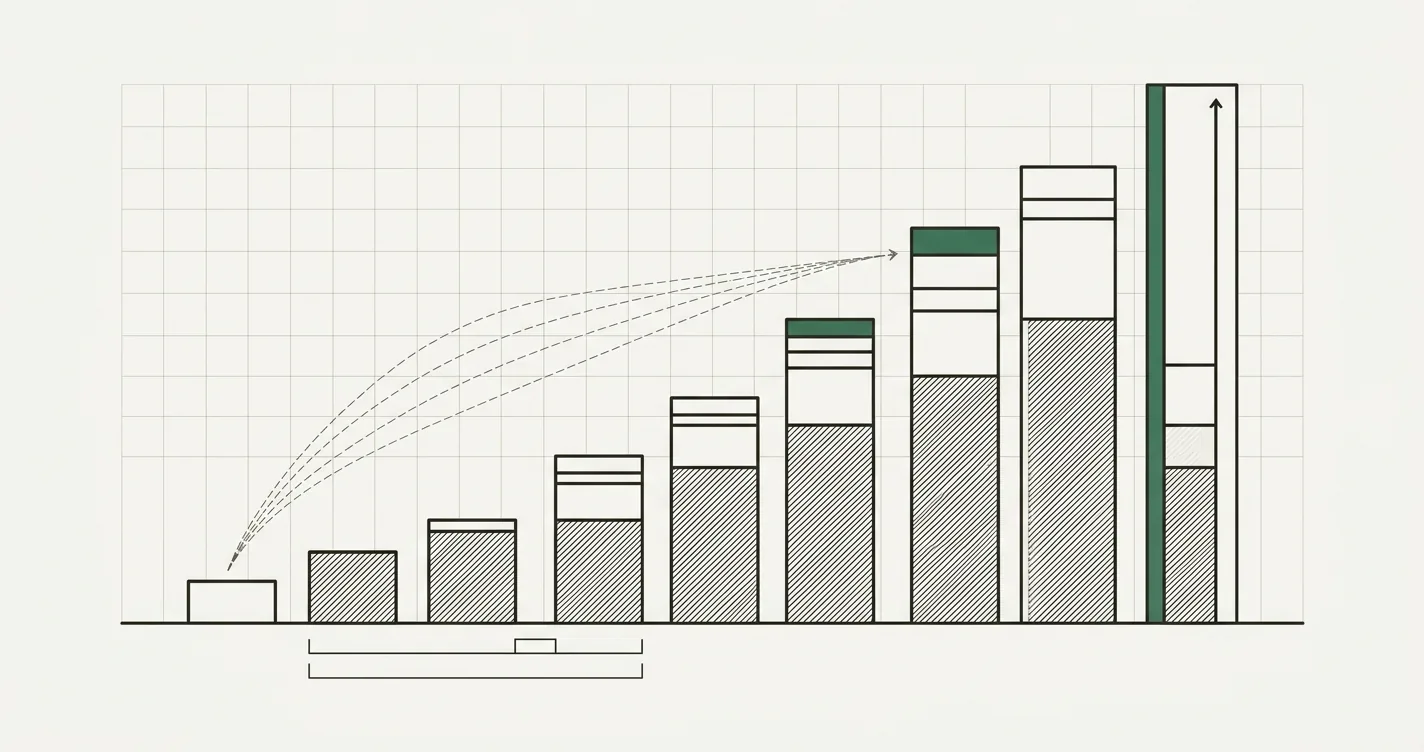
Choosing a startup valuation method by stage and data availability. Whatever the method, the output must reconcile to a pre-money number and a cap table.
Pre-Money vs Post-Money: The Foundation
Every valuation method eventually produces a pre-money valuation - what the business is worth before the new money goes in. Once you agree the pre-money and the raise, the rest is arithmetic:
Post-Money Valuation = Pre-Money Valuation + New Investment
Investor Ownership %  = New Investment / Post-Money Valuation
Worked example. A founder negotiates an $8M pre-money valuation and raises $2M:
| Item | Value |
|---|---|
| Pre-Money Valuation | $8.0M |
| New Investment | $2.0M |
| Post-Money Valuation | $10.0M |
| Investor Ownership ($2M / $10M) | 20.0% |
| Founders' Ownership (was 100%) | 80.0% |
The mechanics run through the share count. Say the founders hold 8,000,000 shares before the round:
Price per Share = Pre-Money / Pre-Round Shares = $8,000,000 / 8,000,000 = $1.00
New Shares Issued = Investment / Price per Share = $2,000,000 / $1.00 = 2,000,000
Post-Round Shares = 8,000,000 + 2,000,000 = 10,000,000
Investor Ownership = 2,000,000 / 10,000,000 = 20.0%
The Option-Pool Shuffle
Investors almost always require an unallocated employee option pool to be created before the round - which means it comes out of the pre-money, diluting founders rather than the new investor. If the term sheet asks for a 10% (post-money) pool on the deal above:
| Stakeholder | Post-Round Ownership | Implied Value |
|---|---|---|
| New Investor | 20% | $2.0M |
| Option Pool (new, from pre-money) | 10% | $1.0M |
| Founders | 70% | $7.0M |
The founders' effective pre-money value drops from $8.0M to $7.0M even though the headline number didn't change. Always ask whether a quoted pre-money is "pre-pool" or "post-pool." It is one of the most common places founders quietly lose several points of ownership.
// Core cap-table formulas
= Pre_Money + Investment                       // Post-money valuation
= Investment / Post_Money                       // Investor ownership %
= Pre_Money / Pre_Round_Shares                  // Price per share
= Investment / Price_Per_Share                  // New shares issued
You can model the full staged raise - pricing, dilution, and use of funds - in the free cap table template below.
The Five Methods at a Glance
| Method | Best for | Anchored on |
|---|---|---|
| Berkus | Idea / prototype, pre-revenue | Risk-reduction milestones (fixed $ each) |
| Scorecard | Pre-revenue with a comparable market | Regional average pre-money × quality multiplier |
| Risk Factor Summation | Pre-revenue, risk-heavy sectors | Base valuation ± 12 risk adjustments |
| Venture Capital (VC) Method | Early revenue, clear exit thesis | Projected exit value ÷ target return multiple |
| DCF / Revenue Comps | Later-stage, forecastable | Discounted cash flows or peer multiples |
No single method is authoritative for a young company. Seasoned investors run two or three and look for a convergent range. The methods below are ordered from earliest stage to latest.
Method 1: The Berkus Method (Idea & Prototype Stage)
The Berkus Method, created by angel investor Dave Berkus, sidesteps financial forecasts entirely. It assigns a dollar value - commonly up to $500,000 each - to five sources of risk reduction. The more risk a team has retired, the higher the value, capped at roughly $2.0–2.5M pre-revenue.
| Risk-Reduction Element | Max Value | This Startup |
|---|---|---|
| Sound idea (basic value) | $500K | $500K |
| Prototype (reduces technology risk) | $500K | $500K |
| Quality management team (reduces execution risk) | $500K | $400K |
| Strategic relationships (reduces market risk) | $500K | $250K |
| Product rollout / early sales (reduces production risk) | $500K | $0 |
| Pre-Money Valuation | $2.5M | $1.65M |
Summing the assigned column: $500K + $500K + $400K + $250K + $0 = $1.65M pre-money. The method's virtue is honesty about what actually de-risks a company at the earliest stage - a working prototype and a credible team matter far more than a spreadsheet forecast nobody believes.
Method 2: The Scorecard Method
The Scorecard Method (Bill Payne's method) starts from the average pre-money valuation of comparable startups in your region and sector, then adjusts up or down across weighted quality factors. It is the go-to method for angel groups where a benchmark deal-flow average is available.
Assume the regional average pre-money for comparable seed startups is $4.0M. You then score each factor as a percentage where 100% = "at par with the benchmark," above 100% = stronger, below = weaker:
| Factor | Weight | Comparison | Weight × Comparison |
|---|---|---|---|
| Strength of management team | 30% | 125% | 0.375 |
| Size of the opportunity | 25% | 150% | 0.375 |
| Product / technology | 15% | 100% | 0.150 |
| Competitive environment | 10% | 75% | 0.075 |
| Marketing / sales / partnerships | 10% | 80% | 0.080 |
| Need for additional investment | 5% | 100% | 0.050 |
| Other factors | 5% | 100% | 0.050 |
| Total multiplier | 100% | - | 1.155 |
Pre-Money Valuation = Benchmark x Sum of (Weight x Comparison)
Pre-Money Valuation = $4.0M x 1.155 = $4.62M
In Excel this is a one-line SUMPRODUCT:
// Weights in B2:B8, Comparison factors in C2:C8, Benchmark in F1
= F1 * SUMPRODUCT(B2:B8, C2:C8)      // = $4.62M
The Scorecard is powerful because it forces an explicit, weighted conversation about why this team deserves a premium (or discount) to the market - and the weights themselves are a defensible negotiating anchor.
Method 3: Risk Factor Summation
This method starts from a base pre-money (again, a regional/sector average - say $4.0M) and adjusts it across 12 risk categories: management, stage of business, political/legislation risk, manufacturing risk, sales & marketing risk, funding/capital risk, competition risk, technology risk, litigation risk, international risk, reputation risk, and potential for a lucrative exit.
Each factor is scored from −2 to +2, translated into dollars (commonly +$500K for +2, +$250K for +1, $0 for neutral, and the mirror for negatives):
| Risk Factor | Score | Adjustment |
|---|---|---|
| Management | +2 | +$500K |
| Potential lucrative exit | +1 | +$250K |
| Technology | +1 | +$250K |
| Competition | −1 | −$250K |
| All other factors | 0 | $0 |
| Net adjustment | - | +$750K |
Pre-Money = Base + Net Risk Adjustments = $4.0M + $0.75M = $4.75M
Risk Factor Summation is essentially a more granular Scorecard. Use it when the sector is risk-heavy (regulated health, hardware, deep tech) and you want each individual risk on the record.
Method 4: The Venture Capital (VC) Method
Once a startup has early revenue and a credible exit thesis, investors switch to the VC Method, which works backwards from the exit. The logic: an investor targets a multiple on invested capital (MOIC), estimates what the company could be worth at exit, and solves for today's valuation.
Step 1 - Estimate the exit value. The business plan projects $50M of revenue in Year 5. Comparable acquisitions in the space happen at roughly 5× revenue:
Exit Value = Year-5 Revenue x Exit Multiple = $50M x 5 = $250M
Step 2 - Set the required return. A seed investor putting in $2M targets a 10× MOIC on this position (early-stage funds price a wide loss rate into a few big winners).
Step 3 - Solve for post-money today. Two equivalent routes:
Required exit ownership = (Investment x Target MOIC) / Exit Value
                        = ($2M x 10) / $250M = $20M / $250M = 8.0%

Post-Money (today)      = Investment / Required Ownership = $2M / 0.08 = $25M
Pre-Money (today)       = Post-Money - Investment = $25M - $2M = $23M
Cross-check: discount the exit value by the target multiple directly - $250M ÷ 10 = $25M post-money. Same answer. At exit, 8% of $250M = $20M, exactly 10× the $2M invested. ✓
The Return Hidden Inside a MOIC
A target multiple is just an annualized return in disguise. A 10× return over 5 years implies a compound annual growth rate of:
= (10)^(1/5) - 1 // = 0.5849 -> ~58% per year
That ~58% is the eye-watering annual return that justifies why seed valuations look so low relative to the dream. Stretch the hold to 7 years and the same 10× only needs (10)^(1/7) - 1 = ~39% a year - which is why time-to-exit assumptions quietly move valuations as much as the exit multiple does. Try different multiples and holding periods below:
Adjusting for Future Dilution
The clean version above assumes the seed investor is never diluted - but Series A, B, and option pools will chip away at their stake. Investors correct for this with a retention ratio. If the seed investor expects to retain only 60% of their initial ownership by exit:
Required ownership today = Required exit ownership / Retention ratio
                         = 8.0% / 0.60 = 13.3%
Post-Money (today)       = $2M / 0.133 = $15M
Pre-Money (today)        = $15M - $2M = $13M
Accounting for dilution drops the defensible pre-money from $23M to $13M for the same target return - a stark reminder that future rounds are effectively borrowed against today's price.
Method 5: DCF and Revenue-Multiple Comps (Later Stage)
Once cash flows become forecastable, later-stage rounds lean on the same tools used for mature companies. A DCF projects unlevered free cash flow and discounts it at a (high) startup cost of capital - see our full DCF model in Excel tutorial for the mechanics, and our overview of business valuation methods for how DCF sits alongside comps. In practice, discount rates for early-stage companies run 30–60% to reflect survival risk, which crushes the value of distant cash flows.
Revenue-multiple comps are more common for growth-stage software: apply the trading or transaction multiple of comparable companies to the startup's forward revenue.
Implied Enterprise Value = Forward Revenue x Peer EV/Revenue Multiple
                         = $12M ARR x 8x = $96M
The catch: startup multiples are volatile and reflect growth expectations, so a company growing 100% year-over-year commands a very different multiple than one growing 30%. Always match comps on growth rate and margin, not just sector.
How Much Equity Should You Give Up?
A useful sanity check on any valuation is the resulting dilution. Founders start at 100% and give up a slice each round. A typical path:
| Round | New Investor Stake | Founders' Ownership After |
|---|---|---|
| Formation | - | 100% |
| Seed | 20% | 80% |
| Series A | 20% | 64% |
| Series B | 15% | 54.4% |
Founders retain 0.80 × 0.80 × 0.85 = 54.4% after three priced rounds (before counting option-pool top-ups, which push it lower). The rule of thumb - give up 10–25% per priced round - exists precisely because much beyond that leaves founders under-motivated and under-controlling by Series B. If a valuation forces you to sell 40% in a single round, that is a signal the pre-money is too low, not that you should proceed. Model the full journey - including pools and staged use of funds - with the free cap table template, and pair it with our startup financial model guide for the forecast that feeds the exit assumptions.
Common Mistakes to Avoid
- Confusing pre-money and post-money. "A $10M valuation" is meaningless until you know whether the raise is on top. On a $2M raise, an $8M pre-money and a $10M pre-money are two very different deals.
- Ignoring the option-pool shuffle. A pre-money option pool comes out of the founders' slice, not the investor's. A "pre-pool" quote can be worth several points of ownership less than it looks.
- Reverse-engineering the valuation you want. Picking a $250M exit and a 10× just to justify a headline number, then working backwards, produces fiction. Anchor the exit value in real comparable transactions.
- Using a public-company discount rate. A 9% WACC on a pre-revenue startup dramatically overvalues distant cash flows. Early-stage discount rates belong in the 30–60% range to reflect failure risk.
- Relying on a single method. Each method has a blind spot. Run at least two (e.g., Scorecard for a market anchor plus the VC Method for the exit view) and present a range, not a point.
- Forgetting future dilution in the VC Method. Ownership today is not ownership at exit. Apply a retention ratio, or you will systematically overpay.
- Treating the valuation as the goal. A high headline valuation with bad terms (heavy liquidation preferences, a big pre-money pool, aggressive anti-dilution) can leave founders worse off than a lower, cleaner number. Value the whole deal.
Alex Tapio
Founder of Finamodel • Professional Financial Modeller • Ex-Deloitte