Dry Cleaning & Laundry Group Model
Consumer Financial Model (Free Excel Download)
Forecast dry-cleaning revenue from garment volume, service mix, pricing, route density, labor, plant capacity, utilities, and expansion investment.

professionals from Deloitte
Used by professionals from
About this model
This model helps you understand a dry-cleaning business across garment care, alterations, collection and delivery, and commercial accounts. It links customer orders and service mix to labour, utilities, equipment, vehicles, and shop costs.
Use it to assess an existing operation, a new location, or a pickup-and-delivery expansion. Test order volume, pricing, staffing, and capital needs to see their impact on profitability and cash flow.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Dry Cleaning & Laundry Group Model
- Store inputs: Year-1 stores, new stores per year, orders per store, production staff per store, average ticket
- Utilisation: Year-1 utilisation with an annual ramp and a practical ceiling
- Service mix: dry cleaning, laundered shirts, wash-and-fold, alterations, and specialty shares, per-tier price indices and net margins
- Ancillary: route members per store and annual route fee, retail spend per order, price escalation
- Cost structure: production and counter-and-delivery FTEs and wage with benefits and wage growth; utilities and energy as % of revenue; facilities, marketing and SG&A as % of gross profit; depreciation (% of revenue); tax
- Capital and working capital: maintenance capex %, store build-out cost per store, NWC % of revenue growth, base-year revenue
- Valuation: WACC, terminal growth, net debt, shares outstanding
- Operations sheet: store roll-forward, utilisation ramp, orders per store, total orders, staff headcount, orders per production FTE
How the Dry Cleaning Financial Model Works
This dry cleaning financial model projects a multi-location dry cleaning and laundry group over seven years. It connects store openings, capacity utilisation, service mix and pricing to a full P&L, cash flow and valuation.
The article explains the operating drivers, calculation flow, key outputs and practical applications so you can evaluate the template.
Operating drivers: stores, utilisation and service mix
The model starts with a store roll-forward: opening stores plus new stores equals closing stores. Closing stores drive production and counter headcount, order volume and route memberships.
- Each store supports a mature order count, multiplied by a utilisation factor to get effective orders per store. Utilisation starts at a Year 1 input, ramps annually and is capped at a practical ceiling.
- Total orders is the key volume driver. Revenue splits across dry cleaning, laundered shirts, wash-and-fold, alterations and specialty services, each with a share, an average ticket and a per-tier price index.
Route memberships and retail attach layer on top. This structure lets you test how new stores, utilisation ramp and service mix interact.
Calculation flow from orders to EBITDA
Orders times tier share times average ticket times price index, escalated at a menu step-up, builds service revenue by tier. Product and supplies cost is each tier's revenue times one minus its net margin.
- Revenue less this direct cost gives gross profit. Production and counter/delivery labour are headcount-driven: FTEs per store times wage, loaded for benefits and wage growth.
- Utilities and energy are a percent of revenue, while facilities, marketing and corporate SG&A are percentages of gross profit. These costs stack to EBITDA, then depreciation leads to EBIT, tax on positive EBIT and net income.
The model also checks the P&L identity.
Outputs: P&L, free cash flow and valuation
The P&L outputs include revenue, gross profit, gross margin, EBITDA, EBITDA margin, EBIT, net income and net margin. The free cash flow bridge starts with EBIT, calculates unlevered tax and NOPAT, adds depreciation, subtracts maintenance capex and store build-out capex, and subtracts the change in working capital.
- Working capital is a light call because dry cleaning is a prepaid, low-inventory business. Unlevered free cash flow is discounted at WACC.
- Valuation sums the present value of explicit cash flows and a Gordon-growth terminal value to enterprise value, then subtracts net debt for equity value and value per share. The dashboard summarises stores, orders, utilisation, revenue per store, average ticket, revenue, EBITDA, EBITDA margin, enterprise value and value per share.
Practical use and analytical flexibility
Use the model to assess an existing operation, a new location or a pickup-and-delivery expansion. Flex orders per store, utilisation ramp, service mix, route attach and pricing to see how blended revenue per order, gross profit, EBITDA and enterprise value respond.
- The model makes per-tier price indices and net margins explicit, so you can analyse the trade-off between high-ticket specialty work and low-ticket laundered shirts. Because labour sits in operating expense, gross margin is not the headline profitability measure; EBITDA margin is more meaningful.
- Changing new store counts shows the capital call from build-out. The discounted cash flow ties operating assumptions to a valuation, helping you evaluate growth strategies.
All monetary figures are in dollars, with stores, orders and FTEs as counts.
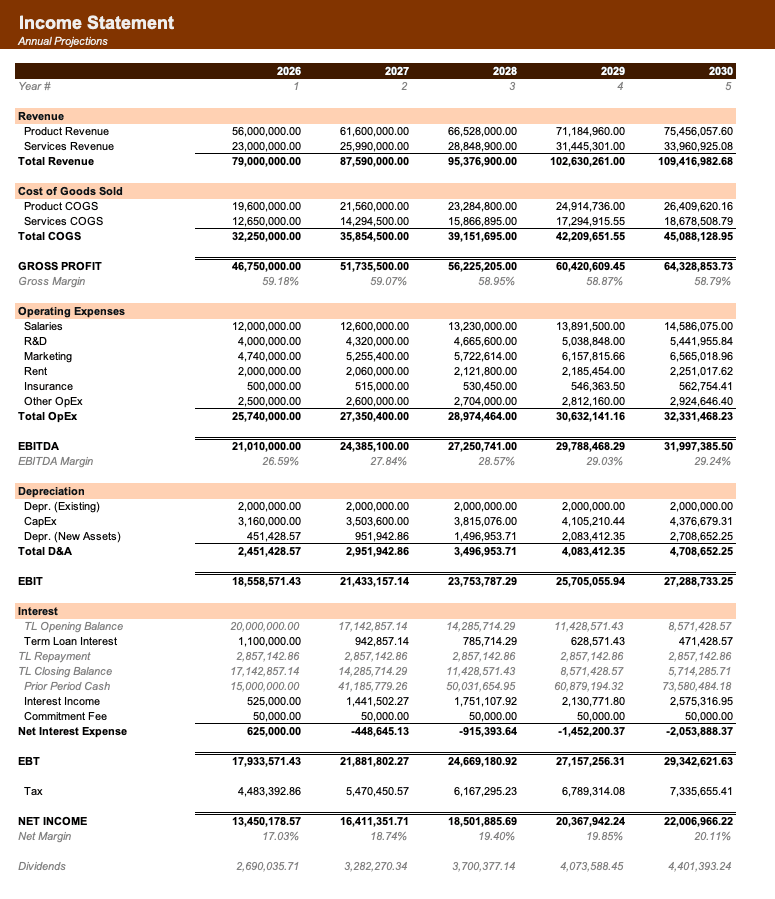
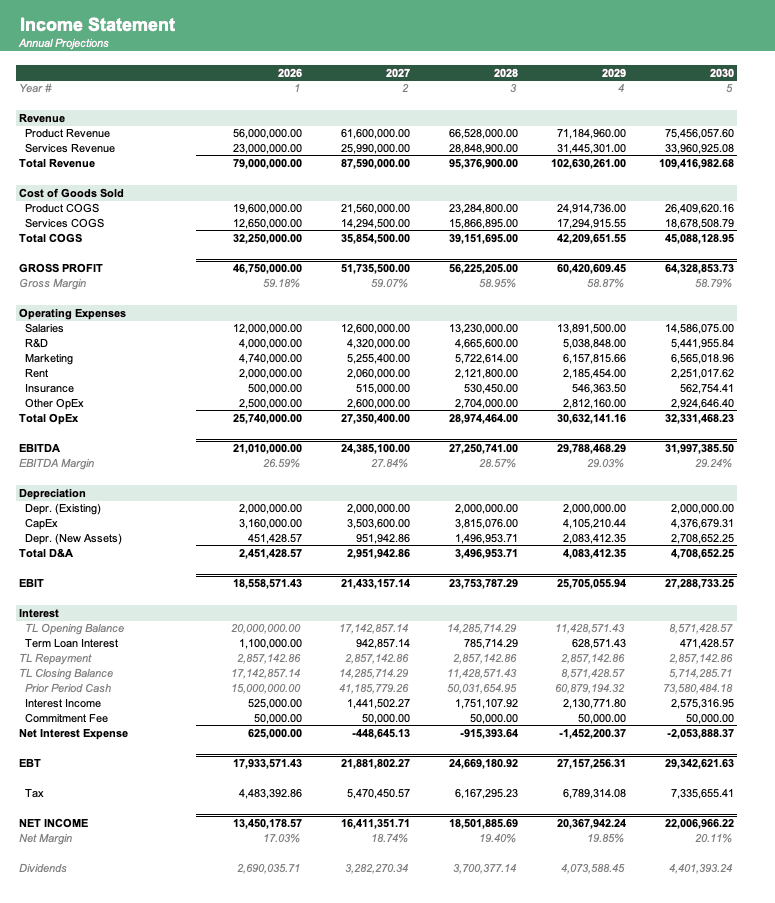
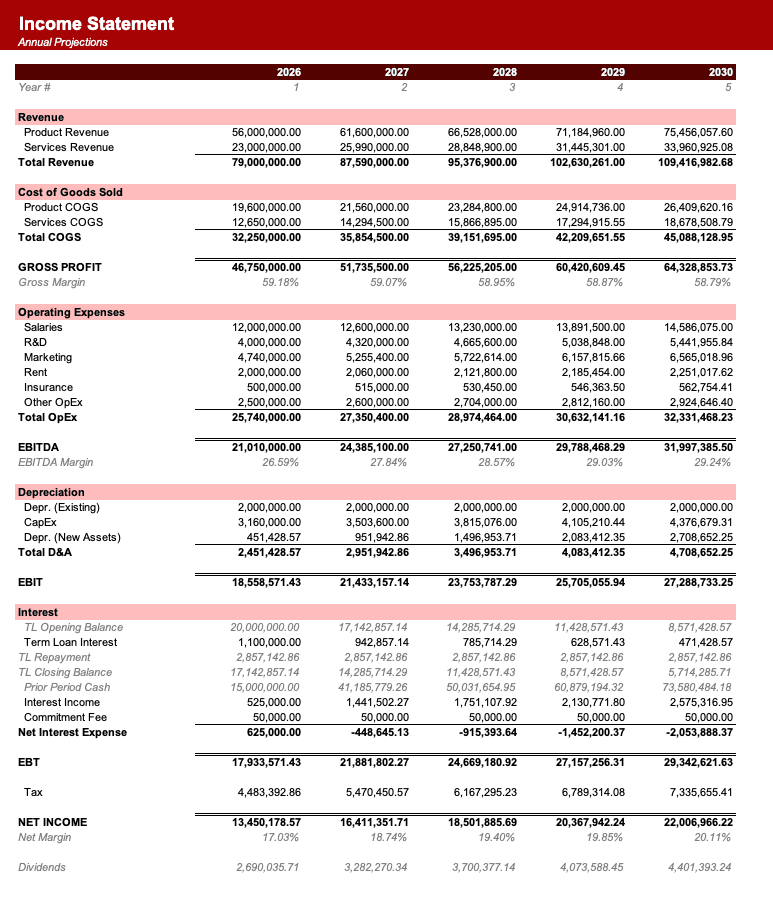
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a dry cleaning financial model?+
A dry cleaning financial model captures the seven-year operating economics and intrinsic value of a multi-location dry cleaning and laundry group that offers garment dry cleaning, laundered shirts, wash-and-fold laundry, alterations and repairs, and specialty and preservation work, plus a pickup-and-delivery route membership. It rolls a store count forward, converts a capacity-utilisation ramp into total orders, splits an average ticket across five service tiers each at its own price index and net margin, charges the labour- and energy-heavy cost stack to EBITDA, and discounts an unlevered free-cash-flow stream to enterprise value, equity value, and value per share.
How is dry cleaning revenue built?+
Revenue is driven by the store estate and its utilisation: total orders equal closing stores times orders per store times a utilisation factor that ramps to a ceiling, and service revenue is total orders times an average ticket split across a five-tier service mix that sums to one, with a per-tier price index setting each ticket. Store-driven route memberships and an order-driven retail attach layer on to total revenue.
Why does the gross margin run so high?+
The consumables that touch a garment, poly, hangers, solvent and detergent, are inexpensive, so each service tier carries a high net margin and the blended gross margin runs in the low eighties. The meaningful profitability line is EBITDA, because the pressers, cleaners, spotters and counter staff who do the work sit in operating expense rather than cost of revenue, alongside an energy-intensive utilities line for the plant.
Why an unlevered DCF instead of an EBITDA multiple?+
A cleaner still builds out and equips each plant and refreshes that equipment, so EBITDA overstates cash. The model bridges to unlevered free cash flow, NOPAT plus depreciation, less maintenance and build-out capex, less a light change in working capital for a prepaid, low-inventory cash business, and discounts it at a WACC, then adds a below-normal Gordon-growth terminal value. The implied EV/EBITDA falls out as a sanity check rather than as the valuation input.
Have more financial modelling questions? Contact us
Related templates
Laundromat Model
Plan and value a multi-store laundromat business using machine turns, vend pricing, utility expenses, and a DCF.
Retail Store Model
Plan and value a retail-store chain using new stores, customer traffic, sales, inventory, and operating costs.
Coffee Shop Chain Model
Plan and value a specialty coffee chain using store foot traffic, average ticket size, beverage gross margins, and a DCF.
E-Commerce Unit Economics
P&L model for e-commerce business with CAC, LTV, gross margin, and unit economics.


