Value Creation Bridge Model
Private Equity Financial Model (Free Excel Download)
Decompose sponsor returns into revenue growth, margin, leverage, multiple change, cash flow, and acquisitions so value creation is measurable year by year.

professionals from Deloitte
Used by professionals from
About this model
A five-year private equity deal model whose output is an attribution rather than a valuation: the movement from entry equity value to exit equity value is decomposed into organic revenue growth, add-on revenue, gross margin expansion, operating leverage, multiple change, free cash flow and the capital deployed on acquisitions, and every component reconciles exactly to money multiple and IRR. The signature mechanic is that the attribution is chain-linked and struck year by year rather than computed once end to end: each year's revenue effect is valued at the prior year's EBITDA margin and each year's margin effect at that year's revenue, both capitalised at the entry multiple, so the five annual columns telescope arithmetically into the hold-period bridge and an attribution check row resolves to zero in every single year instead of only in aggregate. Equity is deliberately marked at the entry multiple in every intermediate year and re-marked only at exit, which quarantines the multiple effect into the exit year and stops a re-rating from contaminating the operating attribution. The margin effect is split further into a gross margin component and an operating leverage component using the identity that EBITDA margin equals gross margin less the operating cost ratio, and the cost base is built so that leverage is earned rather than assumed - each of four expense lines escalates at inflation plus a line-specific share of revenue growth, against a cumulative cost programme, so the operating cost ratio falls from 27.2% to 24.1% and EBITDA margin rises from 14.8% to 19.9% without a single margin being hardcoded. On the shipped base case a 420,000 revenue platform is bought for 590,520 at 9.5x, funded with 279,720 of term debt and a 40,000 revolver that is drawn to 4,666 to complete the second add-on and swept back to zero by Year 3; the business exits at 9.0x, half a turn below entry, and still returns 2.79x aggregate and 2.57x to the sponsor at a 20.8% IRR because 212,654 of free cash flow and 148,976 of operating leverage more than cover a 57,702 multiple contraction. The second half of the model converts every bridge line into turns of invested equity - organic growth 0.56x, free cash flow 0.63x, operating leverage 0.44x, gross margin 0.30x, add-ons net 0.09x, multiple change negative 0.17x - and reconciles the entry equity value to the 337,005 actually invested through the 18,204 fee load the plan has to earn back before it creates a cent of value.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Value Creation Bridge Model
- Entry transaction: LTM revenue and gross margin, entry EBITDA multiple, transaction and financing fees, minimum cash, management rollover
- Entry cost base: personnel, facilities and IT, sales and marketing, and overhead as shares of LTM revenue
- Operating plan: a per-year organic growth row, an annual gross margin gain, cost inflation, four line-specific revenue flex factors and a per-year cost programme savings row
- Add-on programme: a per-year acquired revenue row, the target EBITDA margin that prices it, and the add-on entry multiple
- Capital and working capital: opening net fixed assets, asset life, capex as a share of revenue, receivable, inventory and payable days
- Debt facilities: Term Loan A and Term Loan B leverage, rates and amortisation, a revolver with a drawn rate and commitment fee, the cash sweep share and the tax rate
- Exit and incentives: exit EBITDA multiple and the management incentive pool
- Operating plan sheet: revenue build, gross profit, cost escalators, operating expenses, capital base, earnings and working capital
Value Creation Bridge: How This Model Attributes Returns
The Value Creation Bridge explains where returns come from in a sponsor deal, breaking down the change in equity value into seven distinct drivers. It tracks organic growth, add-on revenue, margin shifts, multiple change, free cash flow, and acquisition capital, showing each component's contribution in turns of invested equity.
What Drives Value Creation in the Bridge
The model isolates seven components that sum exactly to the change in equity value. Organic revenue growth captures same-business expansion, valued at the prior year's margin.
- Add-on revenue reflects acquisitions, similarly valued. Gross margin expansion results from procurement, pricing, and delivery mix.
- Operating leverage arises as the operating cost ratio falls. Multiple change isolates entry-to-exit re-rating, confined to the exit year.
- Free cash flow represents deleveraging after interest, tax, capex, and working capital. Add-on capital deployed is a negative item for cash spent on acquisitions.
Each component is restated in turns of invested equity to show return contributions.
How the Attribution Is Calculated
The attribution is chain-linked and computed year by year. For each period, revenue effect equals the change in revenue times the prior margin times entry equity, while margin effect equals current revenue times the change in margin times entry equity.
- These annual effects telescope exactly to the total change over the hold. The margin effect is further split into gross margin expansion and operating leverage, reflecting the identity that EBITDA margin equals gross margin less the operating cost ratio.
- This approach ensures the attribution check resolves to zero in every year, not just in aggregate.
Model Outputs and Calculations
The model produces a hold-period bridge that sums the annual components and reconciles to the exit equity value. An equity invested reconciliation bridges the gap between entry equity value and the sponsor's actual invested capital, incorporating transaction and financing fees.
- Outputs include the money multiple attribution, which expresses each bridge component as a multiple of invested equity. The base case includes a deliberately halved multiple contraction, yet the deal still clears a strong return because operating leverage and cash generation contribute more than a turn of money multiple.
- All outputs are derived from the operating plan and capital structure, with validation checks ensuring arithmetic consistency.
Practical Use of the Model
This bridge is designed for evaluating where returns come from in a given deal, not for sizing a deal or solving for returns. It takes the deal as given and attributes the outcome.
- The model is particularly useful for understanding the impact of operational improvements versus multiple expansion. It assumes immediate and complete integration of add-ons, with no interim distributions, so all cash flow is swept against debt.
- Users should be aware that add-on revenue is annualised and cost programme savings are cumulative run-rate. The model is built to show operations against a modest re-rating, not for distress scenarios.
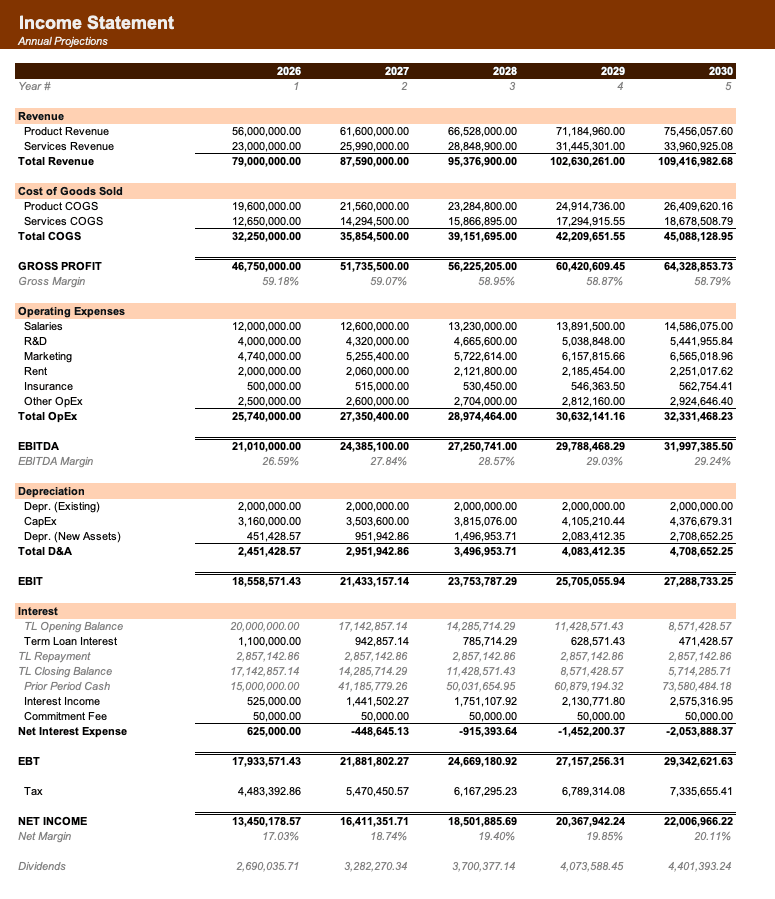
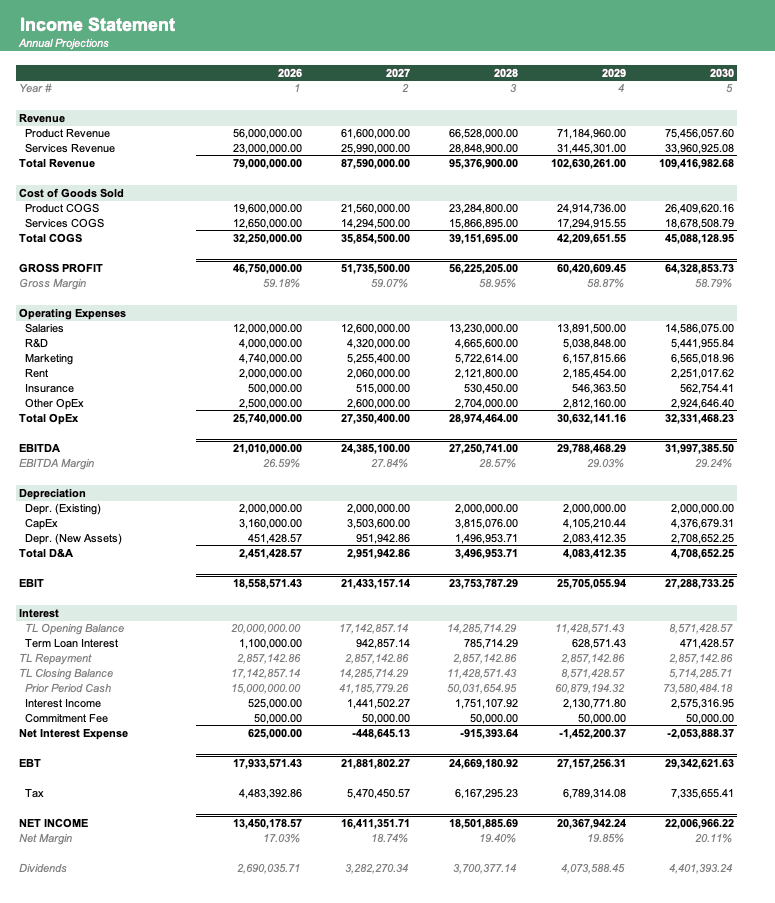
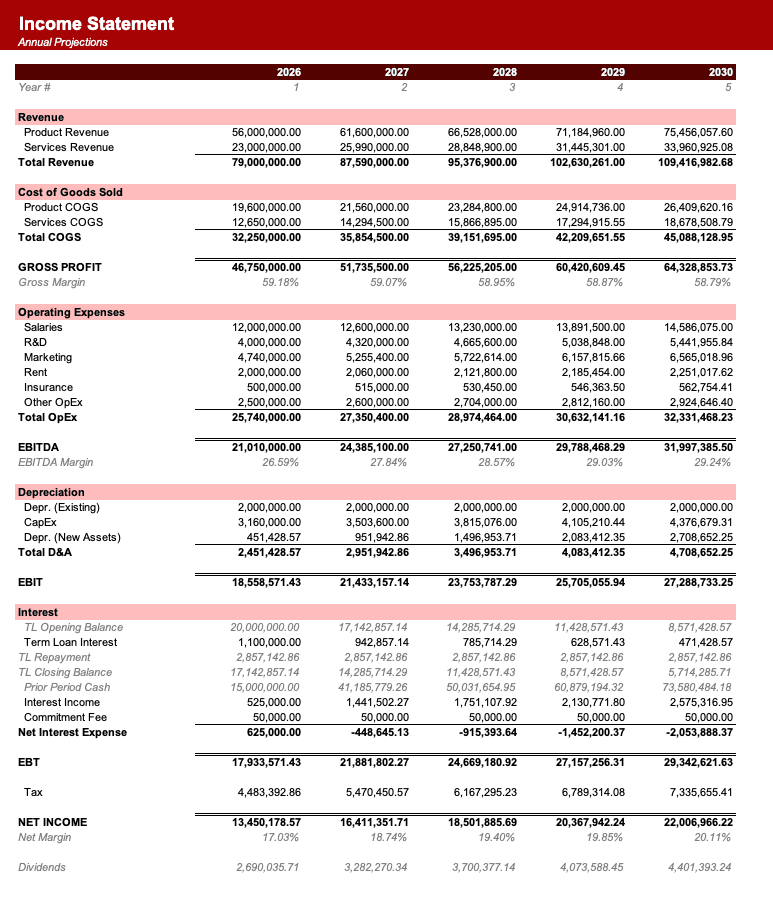
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a value creation bridge?+
A value creation bridge attributes the change in a private equity investment's equity value between entry and exit to the drivers that produced it, so that a money multiple stops being a single number and becomes a set of contributions. This model splits the movement into organic revenue growth, add-on revenue, gross margin expansion, operating leverage, multiple change, free cash flow and the capital deployed on acquisitions, and every component reconciles to the money multiple and IRR.
Why is the attribution chain-linked rather than computed end to end?+
A one-shot decomposition is path-dependent: the split between the revenue effect and the margin effect depends on whether you hold the entry margin or the exit margin fixed, and the two answers differ by a real amount whenever both move. Striking the effects year by year, with each year's revenue effect valued at the prior year's margin and each year's margin effect at that year's revenue, telescopes exactly into the total. The annual columns therefore sum to the hold-period bridge by arithmetic, and the workbook proves it with a check row that must be zero in every year.
Why is equity marked at the entry multiple until the exit year?+
Because a mid-hold re-rating would otherwise leak into whichever year it was applied and make that year's operating attribution unreadable. Holding the multiple constant until exit means every intermediate equity mark is a pure operating mark, and the whole re-rating lands in a single multiple change line in the exit year, which is exactly where a reader wants to find it.
How does the model separate operating leverage from margin improvement?+
EBITDA margin equals gross margin less the operating cost ratio, so the margin effect splits exactly into those two terms. Gross margin walks up by an annual gain from procurement and mix; the operating cost ratio falls because four expense lines escalate at inflation plus only a line-specific share of revenue growth, net of a cumulative cost programme. No EBITDA margin is ever an input, which is why the leverage component is earned rather than assumed.
Why does the base case assume the multiple contracts?+
Because a bridge whose largest positive component is multiple expansion teaches nothing about the plan. The shipped case exits at 9.0x against a 9.5x entry, a half-turn contraction worth negative 57,702, and still returns 2.79x aggregate and 2.57x to the sponsor at a 20.8% IRR. Operating leverage contributes 0.44 turns and free cash flow 0.63 turns, which between them more than cover the re-rating.
Can I use this for my own deal?+
Yes. Every driver is a labelled input on the Assumptions sheet wired through named ranges, so you can replace the entry revenue and margin, the entry multiple and fee load, the organic growth and cost programme rows, the add-on schedule, the debt tranches and sweep, the working capital days, the exit multiple and the incentive pool with your own. The workbook recalculates end to end and five validation rows tell you immediately whether the bridge still foots.
Have more financial modelling questions? Contact us
Related templates
Leveraged Buyout Model
Complete LBO analysis with debt financing structures, sponsor returns, and sensitivity to exit scenarios.
EBITDA Bridge
Year-over-year EBITDA bridge decomposing variance across volume, price, variable costs, FX, and opex drivers.
Secondary Private Company Sale Model
Modeling secondary sales of stakes in private companies, including buyer valuations, hold periods, and investor return scenarios.
Venture Capital Fund Model
Model VC fund cash flows, distributed returns, and IRR by vintage year and exit scenario.


