DADayforward Financial Model
InsurTech Startup Financials (Free Excel Download)
Digital direct-to-consumer life insurance carrier - issues its own policies, holds its own risk.

professionals from Deloitte
About this model
Dayforward is a digital direct-to-consumer life-insurance carrier that issues and holds its own policies. It uses alternative data and digital underwriting to simplify life cover and avoid broker-led distribution friction.
Because it is a carrier rather than a broker, Dayforward earns premiums but also retains insurance risk. Its economics benefit from direct acquisition and product design, while claims, reserves, and capital requirements remain central to the business.
The model is a life-insurance carrier P&L. Policies sold, face value, premium, persistency, reinsurance, claims, loss ratio, acquisition expense, and statutory surplus determine value. Underwriting selection and reserve development are critical sensitivities.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Dayforward
dayforward.com
How to build a detailed financial model for Dayforward
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Dayforward model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Dayforward is a licensed life insurance carrier (not an agent or broker) that issues, prices, and holds its own policies.
- Proprietary products not available elsewhere - described as "new, revolutionary products only available from Dayforward."
- Mobile-first, D2C buying experience: no brokers, no jargon, no long application.
- Proprietary underwriting driven by new/alternative data sources - faster issuance, better risk assessment, better pricing.
- Claims "Better LTV compared to conventional term life." - no dollar figures attached.
- Three pain points explicitly targeted: product confusion, distribution mistrust (95% of policies sold through commissioned brokers, 89% distrust them), underwriting complexity.
Market
- U.S. life insurance ownership fell from 77M households (1989) to 60M households (2020).
- 20M additional U.S. households should be buying life insurance but are not.
- Of households that do have life insurance: 55% are under-insured, 38% are over-insured, only 7% have the right amount.
- 85% of shoppers try to buy online; fewer than 5% complete a purchase online.
- Industry term life margins: 6% or less.
- No explicit TAM/SAM/SOM dollar figures in deck.
Revenue model
- Revenue = net premiums written on proprietary life insurance policies (carrier model: premiums in, claims + expenses out).
- D2C channel only - no broker commissions paid out; company retains full economics.
- Product type: term life insurance (and potentially new proprietary variants). Pricing not disclosed in deck.
- Economics advantage claimed: eliminating broker commissions (typically 50–100%+ of year-1 premium) improves unit margins vs. traditional carriers.
- No pricing tiers, premium ranges, or policy face amounts disclosed in deck.
Unit economics
- "Better LTV compared to conventional term life." - qualitative only, no figures.
- Industry term life margin benchmark: ~6% or less. - cited as the industry problem to fix.
- No CAC, LTV dollar values, payback period, loss ratio, or combined ratio disclosed.
Competition / moat
- Traditional carriers: unwilling to disrupt their own broker channel, legacy tech, risk-averse culture.
- InsurTech startups (e.g. Haven Life, Bestow, Ladder): act as agents/brokers selling third-party products; innovation limited by dependence on legacy carriers.
- Positioning: Dayforward is the only full-stack D2C life insurance carrier in the U.S. life segment - analogous to Root (auto) and Lemonade (home), both described as "likely to IPO."
- Moat sources: carrier license + regulatory approvals (high barrier), proprietary underwriting IP, brand, and D2C distribution.
Team & funding ask / use of funds
- Team (slide 16):
- Michael Welles - Technology (Huge, Apple, United Technologies)
- Matthew Wolf, FSA - Product & Actuarial (HavenLife/MassMutual, Zurich, AXA)
- Zoe Gruenberg - Marketing (Havas, Huge)
- Tim Nolan - Creative & Design (Bloomberg campaign, Havas, Vice, Huge)
- Mallika Khandelwal - Operations (Collective Health; CEO Choice Fertility)
- Felicia McElhaney - Underwriting (National Life, Sun Life, Great American)
- Zohaib Rathmore, FSA, CFA - Finance & Risk (Chief Actuary, Longitude RE; Willis Towers Watson)
- Board of Directors (slide 17):
- Paul Rooney - Former Global COO, ManuLife
- Elaine Sarsynski - Former CEO, MassMutual International; Board of Directors, AXA
- Maria Vullo - Former Superintendent, NYS Department of Financial Services (Head Insurance Commissioner)
Recommended financial model
- Archetype + why: Insurance GWP / P&L carrier model. Dayforward is a licensed carrier that holds its own risk - the correct model is a life insurance company P&L built around Gross Written Premium (GWP), net earned premium, loss ratio, expense ratio, combined ratio, and statutory surplus. A pure SaaS ARR or DTC P&L would miss the balance sheet / reserve / capital adequacy dimension that defines carrier economics. A simplified 3-statement with embedded insurance KPIs is appropriate given the early stage.
- Forecast horizon & granularity: 5 years (Y1–Y5); monthly for Y1 (pre-launch ramp critical), quarterly for Y2–Y3, annual for Y4–Y5.
- Key drivers & assumptions:
| Driver | Value | Source |
|---|---|---|
| Addressable uninsured households (U.S.) | 20M | - |
| % under/over-insured (re-buy opportunity) | 93% of current 60M policyholders | - |
| Online purchase conversion (industry baseline) | <5% of browsers | - |
| Industry term life net margin | ~6% | - |
| Dayforward target net margin (carrier, D2C) | 12–18% | D2C eliminates broker commission (~50%+ of yr-1 premium); proprietary underwriting tightens loss ratio |
| Average annual premium per policy | $600 | Typical 30-year-old, $500k 20-yr term; benchmark from public carrier filings |
| Average policy face amount | $500,000 | Middle-market D2C target; no deck data |
| Policy lapse rate (annual) | 5–8% | Industry average for term life |
| Loss ratio | 55–65% | Typical for term life; proprietary UW may compress toward 55% |
| Expense ratio (pre-scale) | 35–45% | High early; D2C marketing-heavy; declines with scale |
| Combined ratio | 90–110% → <95% at scale | Target combined <95% by Y3 |
| CAC (digital D2C) | $300–$600 | Paid digital; no agents; benchmarked against Haven Life public commentary |
| LTV (claimed superior to term) | >CAC * 3–5x | Carrier holds multi-year premium stream; exact figure not in deck |
| New policies / month (Year 1 ramp) | 50 → 500 | Pre-revenue, product launching 2020 |
| Reinsurance ceded | 50–70% of face | Early-stage carrier typically cedes majority to manage surplus strain |
| Required statutory surplus | ~$10M+ initial | State licensing / RBC requirements; varies by domicile state |
- Scenarios (Base / Bull / Bear - which variables flex):
- Bear: Online conversion stays near industry 3–4%; loss ratio elevated (65%+); CAC $700+; Y3 combined ratio >105%. Cash-burn focused; need reinsurance support.
- Base: Conversion 5–8%; loss ratio 58%; CAC $450; combined ratio <100% by Y3; 10k policies in force by end Y2.
- Bull: Proprietary UW drives loss ratio to 50%; viral/referral CAC compression to $250; conversion 10%+; 30k+ policies Y2; earlier path to combined ratio <90%.
- Required sheets / outputs:
- Assumptions - all drivers in one place, switchable by scenario.
- Policy volume build - new policies written, lapsed, in-force by month.
- Premium P&L - GWP → net earned premium (after reinsurance ceded) → loss ratio → expense ratio → underwriting income.
- Unit economics - CAC, LTV, payback by cohort.
- Cash & capital - operating cash, statutory surplus build, capital calls.
- 3-statement - simplified IS / BS / CF; BS must include policy reserves (life insurance liability).
- Reinsurance schedule - ceded premium, ceded losses, net retention.
- KPI dashboard - GWP, in-force policies, loss ratio, combined ratio, CAC, LTV/CAC.
Frequently asked
Is the Dayforward financial model free?+
Yes. The Dayforward model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
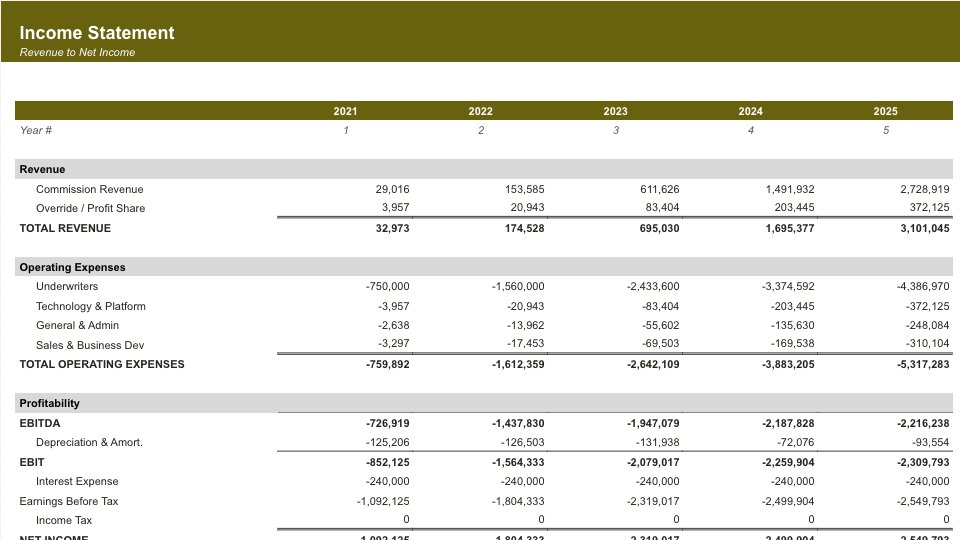
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Dayforward's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other InsurTech Startup Financial Models
Browse another startup in the same category.
Ark Kapital
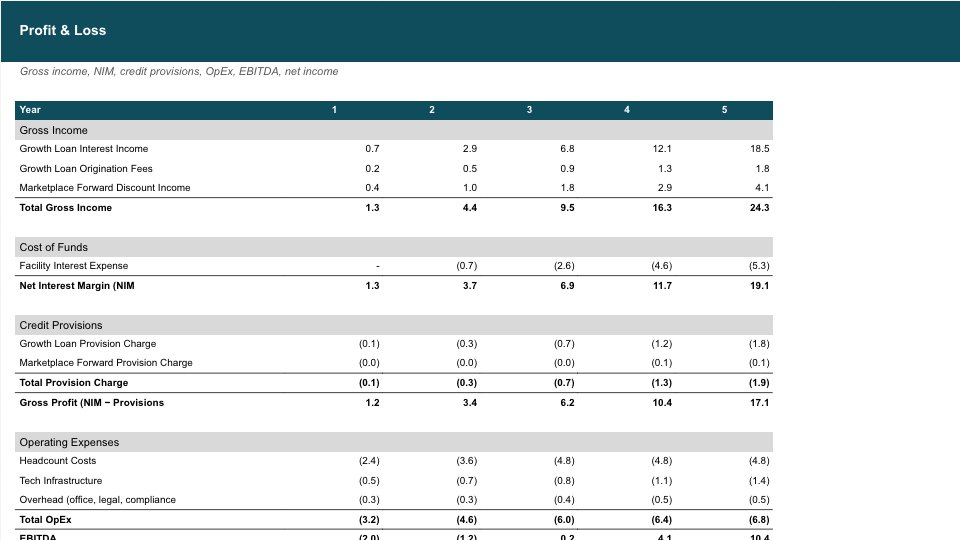
AI-powered precision lending platform for European tech startups, providing non-dilutive growth loans using real-time raw data analytics.
Battleface
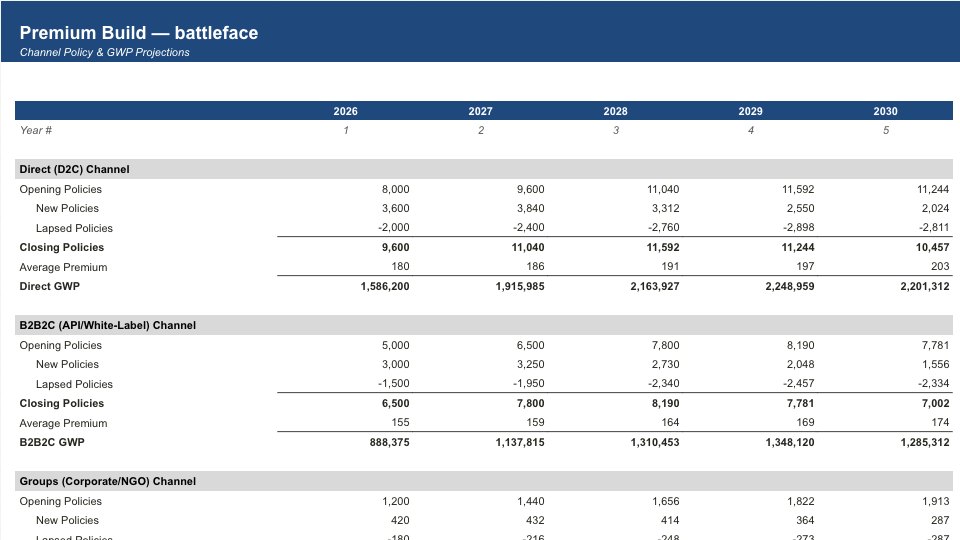
Tech-enabled travel insurance platform covering high-risk and non-standard destinations globally, sold direct and via B2B2C partners.
Beam
Digital-first dental insurance company selling group dental (and ancillary) benefits to employers via brokers

Branch
Tech-enabled home & auto insurance company operating as a reciprocal exchange, selling bundled policies via embedded, direct, and agency channels.
Cachet
B2B2C insurtech marketplace offering flexible, usage-based insurance products to gig/platform economy workers via partnerships with ride-hailing, delivery, and gig platforms.
Caura
Mobile app that aggregates all car-related payments (parking, congestion/ULEZ, tolls, tax, insurance) into a single platform, with insurance comparison as a key monetisation layer.
Clark
Digital insurance broker (Makler) providing a robo-advisor + human expert hybrid platform to manage and purchase all insurance lines via mobile app
Counterpart
Digital MGA (managing general agent) selling D&O and management liability insurance to US SMEs via a tech-enabled underwriting platform.