PAPluralsight Acquisition Financial Model
EdTech Startup Financials (Free Excel Download)
Proxy/shareholder vote presentation defending the Vista Equity Partners take-private acquisition of Pluralsight at $20.26/share (all-cash).

professionals from Deloitte
About this model
This Pluralsight example concerns Vista Equity Partners' all-cash take-private acquisition proposal, not an operating startup pitch. The proxy materials sought shareholder approval for an offer of $20.26 per share and focused on transaction fairness, valuation, and process.
Pluralsight itself is a subscription platform for enterprise technology skills, but operating ARR is context rather than the main analytical output. Vista was acquiring the public company at roughly 9.2 times LTM revenue and 8.1 times NTM revenue, using a conventional private-equity transaction structure.
The relevant model is an LBO or take-private analysis: offer price, shares outstanding, equity value, leverage, sponsor contribution, operating value creation, exit multiple, and investor returns. Premiums, alternatives, financing, and closing conditions complete the deal case.
A turnkey financial model
Live formulas, no hardcoded values
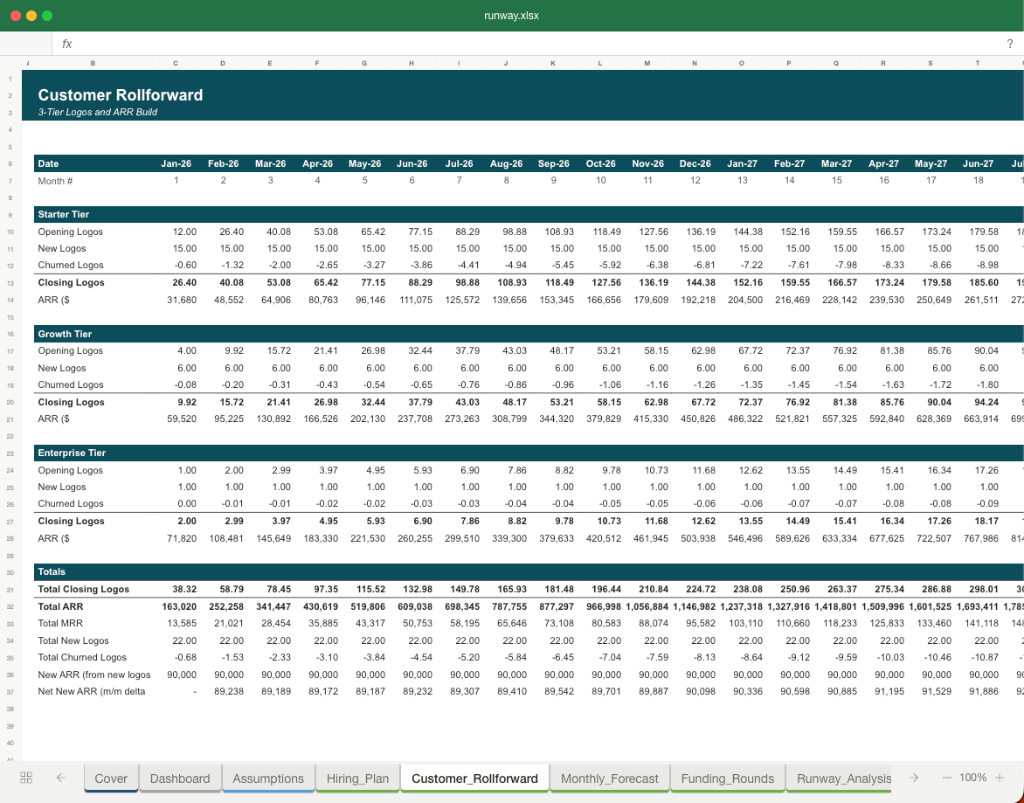
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Pluralsight Acquisition
pluralsight.com
How to build a detailed financial model for Pluralsight Acquisition
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Pluralsight Acquisition model - distilled from its pitch deck and publicly available information.
Product & value proposition
Pluralsight is a B2B-focused technology skills platform providing online courses and assessments for enterprise technology teams. Product portfolio expanded via 11 acquisitions over 8 years (e.g. GitPrime, DevelopIntelligence, Code School, digital-tutors, etc.). Core value prop: upskilling developers and IT professionals. Serves both B2B enterprise and SMB segments; B2C/B2B mix not broken out in deck.
Market
- Eminence/Akaris (opposing shareholders) cited a TAM of $42B immediate and $300B+ global eLearning market - but the Pluralsight board explicitly disputes these figures as overstated given barriers-to-entry and competitive dynamics.
- No TAM/SAM/SOM figures presented by Pluralsight itself in this deck.
Revenue model
- B2B SaaS subscriptions (primary) - enterprise and SMB license seats.
- Recurring subscription revenue model; billings and revenue are distinct metrics tracked separately.
- S&M spend-heavy go-to-market; LTM S&M as % of revenue was ~52%.
- Acquisition-driven inorganic growth: 11 transactions totaling ~$425M over 8 years.
- ~$594M convertible note overhang limiting low-cost debt access.
Traction & metrics
Revenue / Billings growth (YoY, quarterly):
- Billings growth: 42% (Q2'18), 44% (Q3'18), 42% (Q4'18), 41% (Q1'19), 23% (Q2'19), 28% (Q3'19), 28% (Q4'19), 16% (Q1'20), 11% (Q2'20), 9% (Q3'20), 17% (Q4'20 midpoint guidance)
- Revenue growth: 38% (Q2'18), 42% (Q3'18), 42% (Q4'18), 40% (Q1'19), 42% (Q2'19), 34% (Q3'19), 32% (Q4'19), 33% (Q1'20), 25% (Q2'20), 20% (Q3'20), 18% (Q4'20 midpoint guidance)
NTM billings growth consensus estimate: Declined from ~33% to ~13% over 6 quarters
Dollar-based net retention rates (B2B, LTM):
- 125% (Q2'18), 127% (Q3'18), 128% (Q4'18), 128% (Q1'19), 126% (Q2'19), 120% (Q3'19), 120% (Q4'19), 120% (Q1'20), 118% (Q2'20), 113% (Q3'20) - declining trend
S&M efficiency:
- LTM S&M as % of revenue: 52% (Pluralsight) vs. 18–54% peer range (2nd highest behind Domo)
- Projected sales investment per $1 of incremental revenue: $3.65 (Pluralsight) - 4th highest of 15 peers behind New Relic, Box, Domo
Free Cash Flow (quarterly, $M):
- Q2'18: (9), Q3'18: (1), Q4'18: 5, Q1'19: 2, Q2'19: (11), Q3'19: (7), Q4'19: (13), Q1'20: 3, Q2'20: (18), Q3'20: (15), Q4'20 guidance: ~(5) midpoint
GAAP to Non-GAAP S&M reconciliation (quarterly $M):
- Non-GAAP S&M: Q1'18 28.7, Q2'18 34.3, Q3'18 37.0, Q4'18 38.4, Q1'19 37.3, Q2'19 41.5, Q3'19 46.9, Q4'19 49.2, Q1'20 52.4, Q2'20 46.5, Q3'20 46.1
Transaction price / multiples:
- Deal price: $20.26/share all-cash (announced Dec 13, 2020)
- Initial Vista offer: $16.50 (Nov 6); negotiated up 23% to $20.26
- EV / LTM Revenue: 9.2x
- EV / NTM Revenue: 8.1x
- NTM Rule of 40 multiple: 0.54x (vs. peer median 0.26x)
- Premium to undisturbed share price (11/9/20, $16.10): 26%
- Premium to 30-day VWAP ($16.23): 25%
TRA (Tax Receivable Agreement): Original liability $417M; negotiated down 70% to $127M, saving shareholders ~$1.80/share
CEO ownership: Aaron Skonnard holds ~15.5M shares (~10% of outstanding)
M&A history: 11 acquisitions, aggregate ~$425M over 8 years
Unit economics
- No explicit CAC or LTV figures in deck.
- Dollar-based net retention declining from 128% peak to 113% by Q3'20 - proxy for net revenue expansion.
- S&M expense per $1 of incremental NTM revenue: $3.65 - implies very poor sales efficiency.
- Company consistently FCF negative except sporadic positive quarters (Q4'18 +$5M, Q1'20 +$3M).
- NTM FCF margin implied at ~1% based on Rule of 40 comparison data.
Competition / moat
Competitors called out: LinkedIn Learning (Microsoft), Coursera, Udemy, Udacity, Skillsoft, Cornerstone, General Assembly, New Horizons, MasterClass, YouTube (user-generated), GitHub. Moat assessment (board's own words): "Modest barriers to entry and low switching costs relative to broader enterprise software sector". Competitive pressure driving lower retention, higher S&M spend, slowing growth. Content refresh risk cited by Raymond James. Pricing pressure from LinkedIn enterprise bundling.
Team & funding ask / use of funds
- CEO/co-founder: Aaron Skonnard (founded 2004)
- Independent Transaction Committee: Bonita C. Stewart (VP Global Partnerships, Google) and Leah Johnson (Chief Communications Officer, Lincoln Center)
- This is not a fundraising deck. The "ask" is a shareholder vote in favor of the Vista Equity Partners acquisition at $20.26/share. Vote deadline: March 2, 2021 special meeting; record date January 15, 2021.
- Acquiror: Vista Equity Partners (private equity). Post-close: company goes private.
- No use-of-funds breakdown in deck; Vista's rationale per analyst commentary is to invest in product, M&A, and GTM away from public market quarterly scrutiny.
Recommended financial model
This is an M&A acquisition (take-private) proxy deck, not an operating startup pitch. The appropriate model is an LBO / take-private deal model.
- Archetype + why: LBO / take-private model. Vista Equity Partners is a PE acquiror taking Pluralsight private at $20.26/share (~9.2x LTM / 8.1x NTM revenue). The deck is a proxy presentation defending deal fairness to public shareholders. The model should evaluate deal entry price, leverage structure, value creation levers, and sponsor return / exit multiple - standard PE LBO framework for a SaaS target.
- Forecast horizon & granularity: 5-year hold (FY2021–FY2025) at annual granularity, with quarterly detail for the stub year (FY2021 remainder). Standard PE hold period; Vista is known to hold 3–7 years.
- Key drivers & assumptions:
| Driver | Value |
|---|---|
| Entry price per share | $20.26 |
| EV / LTM Revenue at entry | 9.2x |
| EV / NTM Revenue at entry | 8.1x |
| LTM Revenue (implied, from 9.2x) | ~$420M |
| NTM Revenue at deal (implied, from 8.1x) | ~$476M |
| Revenue growth year 1 (NTM) | ~14% |
| Revenue growth years 2–5 | Declining from ~14% → ~8–10% |
| Gross margin | ~75–80% |
| Non-GAAP S&M as % of revenue | ~52% declining to ~35–40% by Y5 |
| NTM FCF margin at entry | ~1% |
| Target FCF margin by Y5 | ~15–20% |
| Dollar-based net retention | 113% declining toward 110% |
| Total deal equity value | ~$3.3B |
| TRA liability (post-negotiation) | $127M |
| Convertible note overhang | ~$594M |
| Leverage: entry debt / EBITDA | ~5–6x given SaaS profile; exact structure not in deck |
| Exit multiple | 8–12x NTM revenue; scenario-dependent |
| Exit year | Y5 (2025–2026 vintage) |
- Scenarios (Base / Bull / Bear):
- Base: Revenue re-accelerates modestly to ~15–17% by Y3 via GTM restructuring + targeted M&A; FCF margin expands to ~15% by Y5; exit at 10x NTM revenue.
- Bull: Competitive headwinds abate; net retention recovers to ~120%; organic growth to 20%+; M&A accelerates product portfolio; exit at 12–14x NTM revenue.
- Bear: LinkedIn / Microsoft bundling deepens pricing pressure; net retention continues declining to 105%; revenue growth stays sub-10%; FCF positive but limited; exit at 7–8x NTM revenue (potential impairment scenario).
- Flex variables: Revenue growth rate, NTM FCF margin, exit multiple, hold period, additional M&A spend.
- Required sheets / outputs:
- Sources & Uses - entry price, equity check, debt tranches, fees, TRA payoff ($127M), converts refinancing ($594M).
- P&L / Operating Model - annual revenue, gross profit, S&M, R&D, G&A, EBITDA, D&A, EBIT.
- Free Cash Flow Bridge - EBITDA → unlevered FCF → debt service → equity FCF.
- Debt Schedule - term loan amortization, revolver, interest expense, covenant tracking.
- Returns Analysis - MoM and IRR at exit for each scenario; entry/exit bridge.
- Valuation Benchmarking - precedent transactions comp table (LTM/NTM multiples, Rule of 40) confirming deal entry fairness (mirrors Slide 18/27 data).
- Sensitivity Table - IRR vs. exit multiple × revenue growth rate.
Frequently asked
Is the Pluralsight Acquisition financial model free?+
Yes. The Pluralsight Acquisition model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
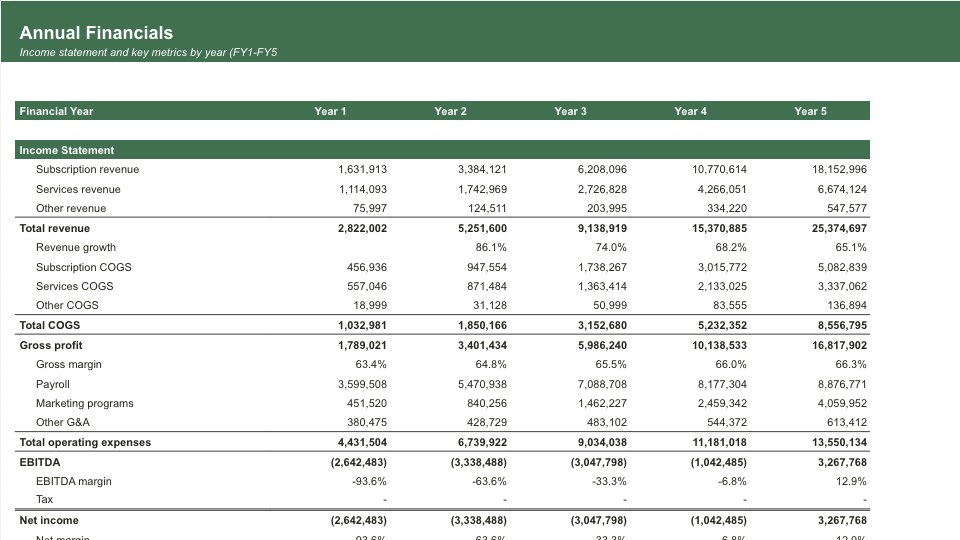
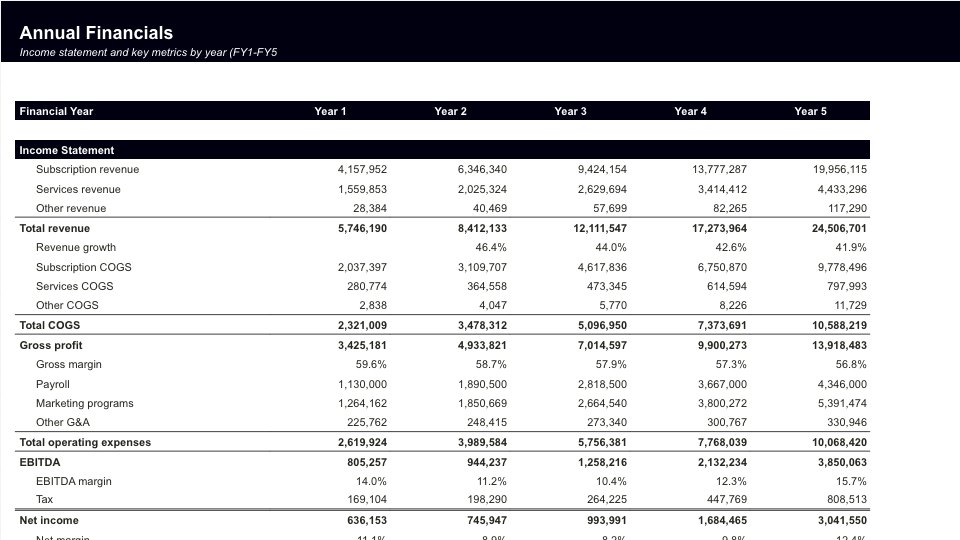
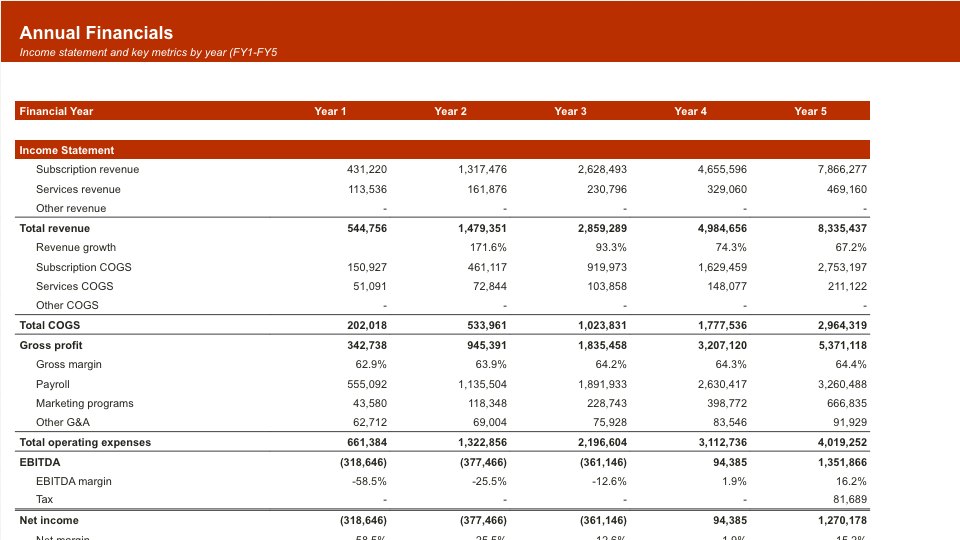
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Pluralsight Acquisition's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other EdTech Startup Financial Models
Browse another startup in the same category.
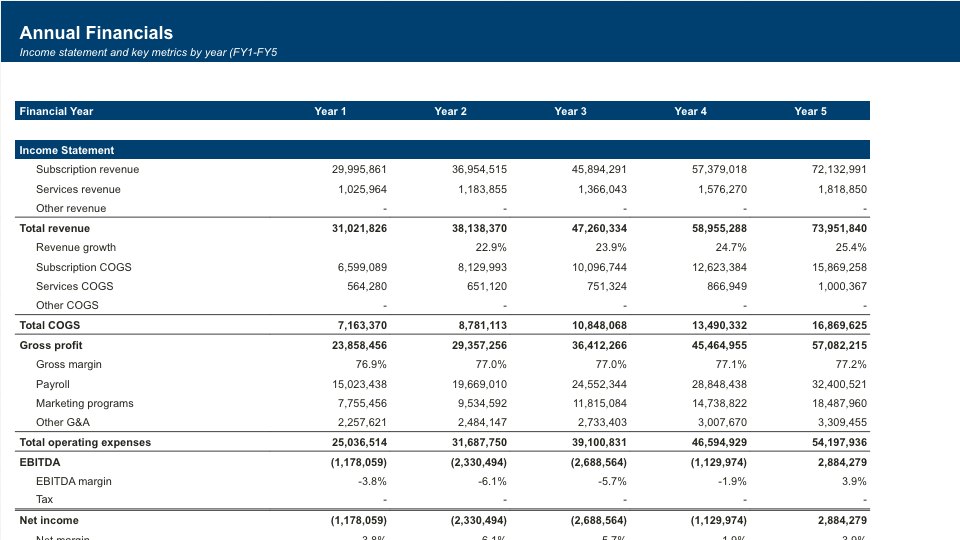
Green Flower Media
Cannabis education platform offering streaming video content, professional certificate programs, and college/university partnerships.
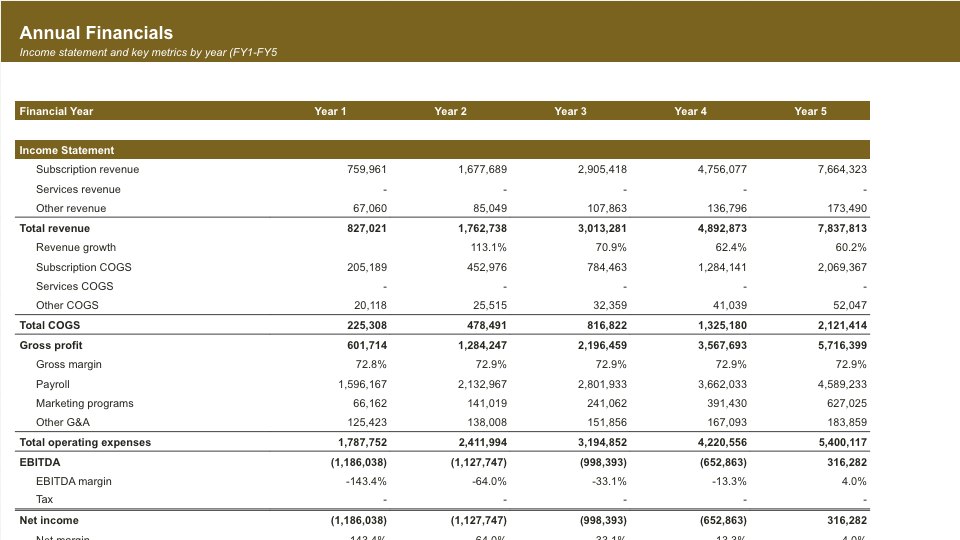
Labster
Web-based virtual science lab platform that replaces or supplements physical labs for higher ed and high school students.
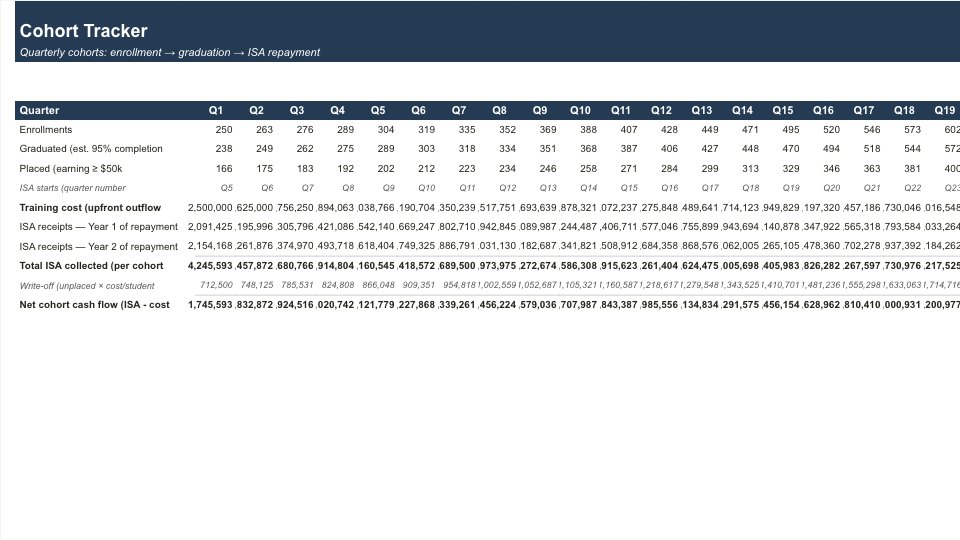
Lambda School
Online coding bootcamp that charges $0 upfront and takes 17% of income for 2 years once a graduate earns $50k+, capped at $30k total.
Learn.xyz
AI-powered mobile learning app that lets anyone create and consume short lessons on any topic in seconds.
Our Future
Short-form video business news and education platform targeting Gen Z, positioned as the missing media brand for that demographic.
Paper
Paper.co sells a cloud-based tutoring/academic-support platform ("Platform as a Service") to K-12 school districts on an annual subscription basis.
Pilgrim Soul
Cannabis brand positioned as the "creativity" category king - proprietary live resin blends, branded journals, and content ecosystem targeting the Creative Class.
Replit
Browser-based coding environment ("REPL") for learning, building, and sharing code - no local setup required.