 Syneroid Technologies Financial Model
InsurTech Startup Financials (Free Excel Download)
NFC/QR smart pet tag + mobile app that connects lost pets to their owners via a centralized database and geo-targeted alerts.



professionals from Deloitte
Used by professionals from






About this model
Syneroid Technologies makes NFC and QR smart pet tags linked to a mobile app and central pet database. A scan can surface owner and veterinary information, notify the owner with location data, and trigger local lost-pet alerts.
Revenue comes primarily from hardware-tag sales through consumer and municipal or institutional channels. The product had a live mobile app, municipal partnerships in New York and California, and manufacturing support from Avery Dennison.
The model is a hardware P&L with an optional services layer. Units sold, ASP, channel mix, manufacturing cost, app activation, replacement sales, and partnership orders drive revenue. Distribution cost, hardware margin, and potential subscription attachment determine profitability.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Syneroid Technologies
syneroid.com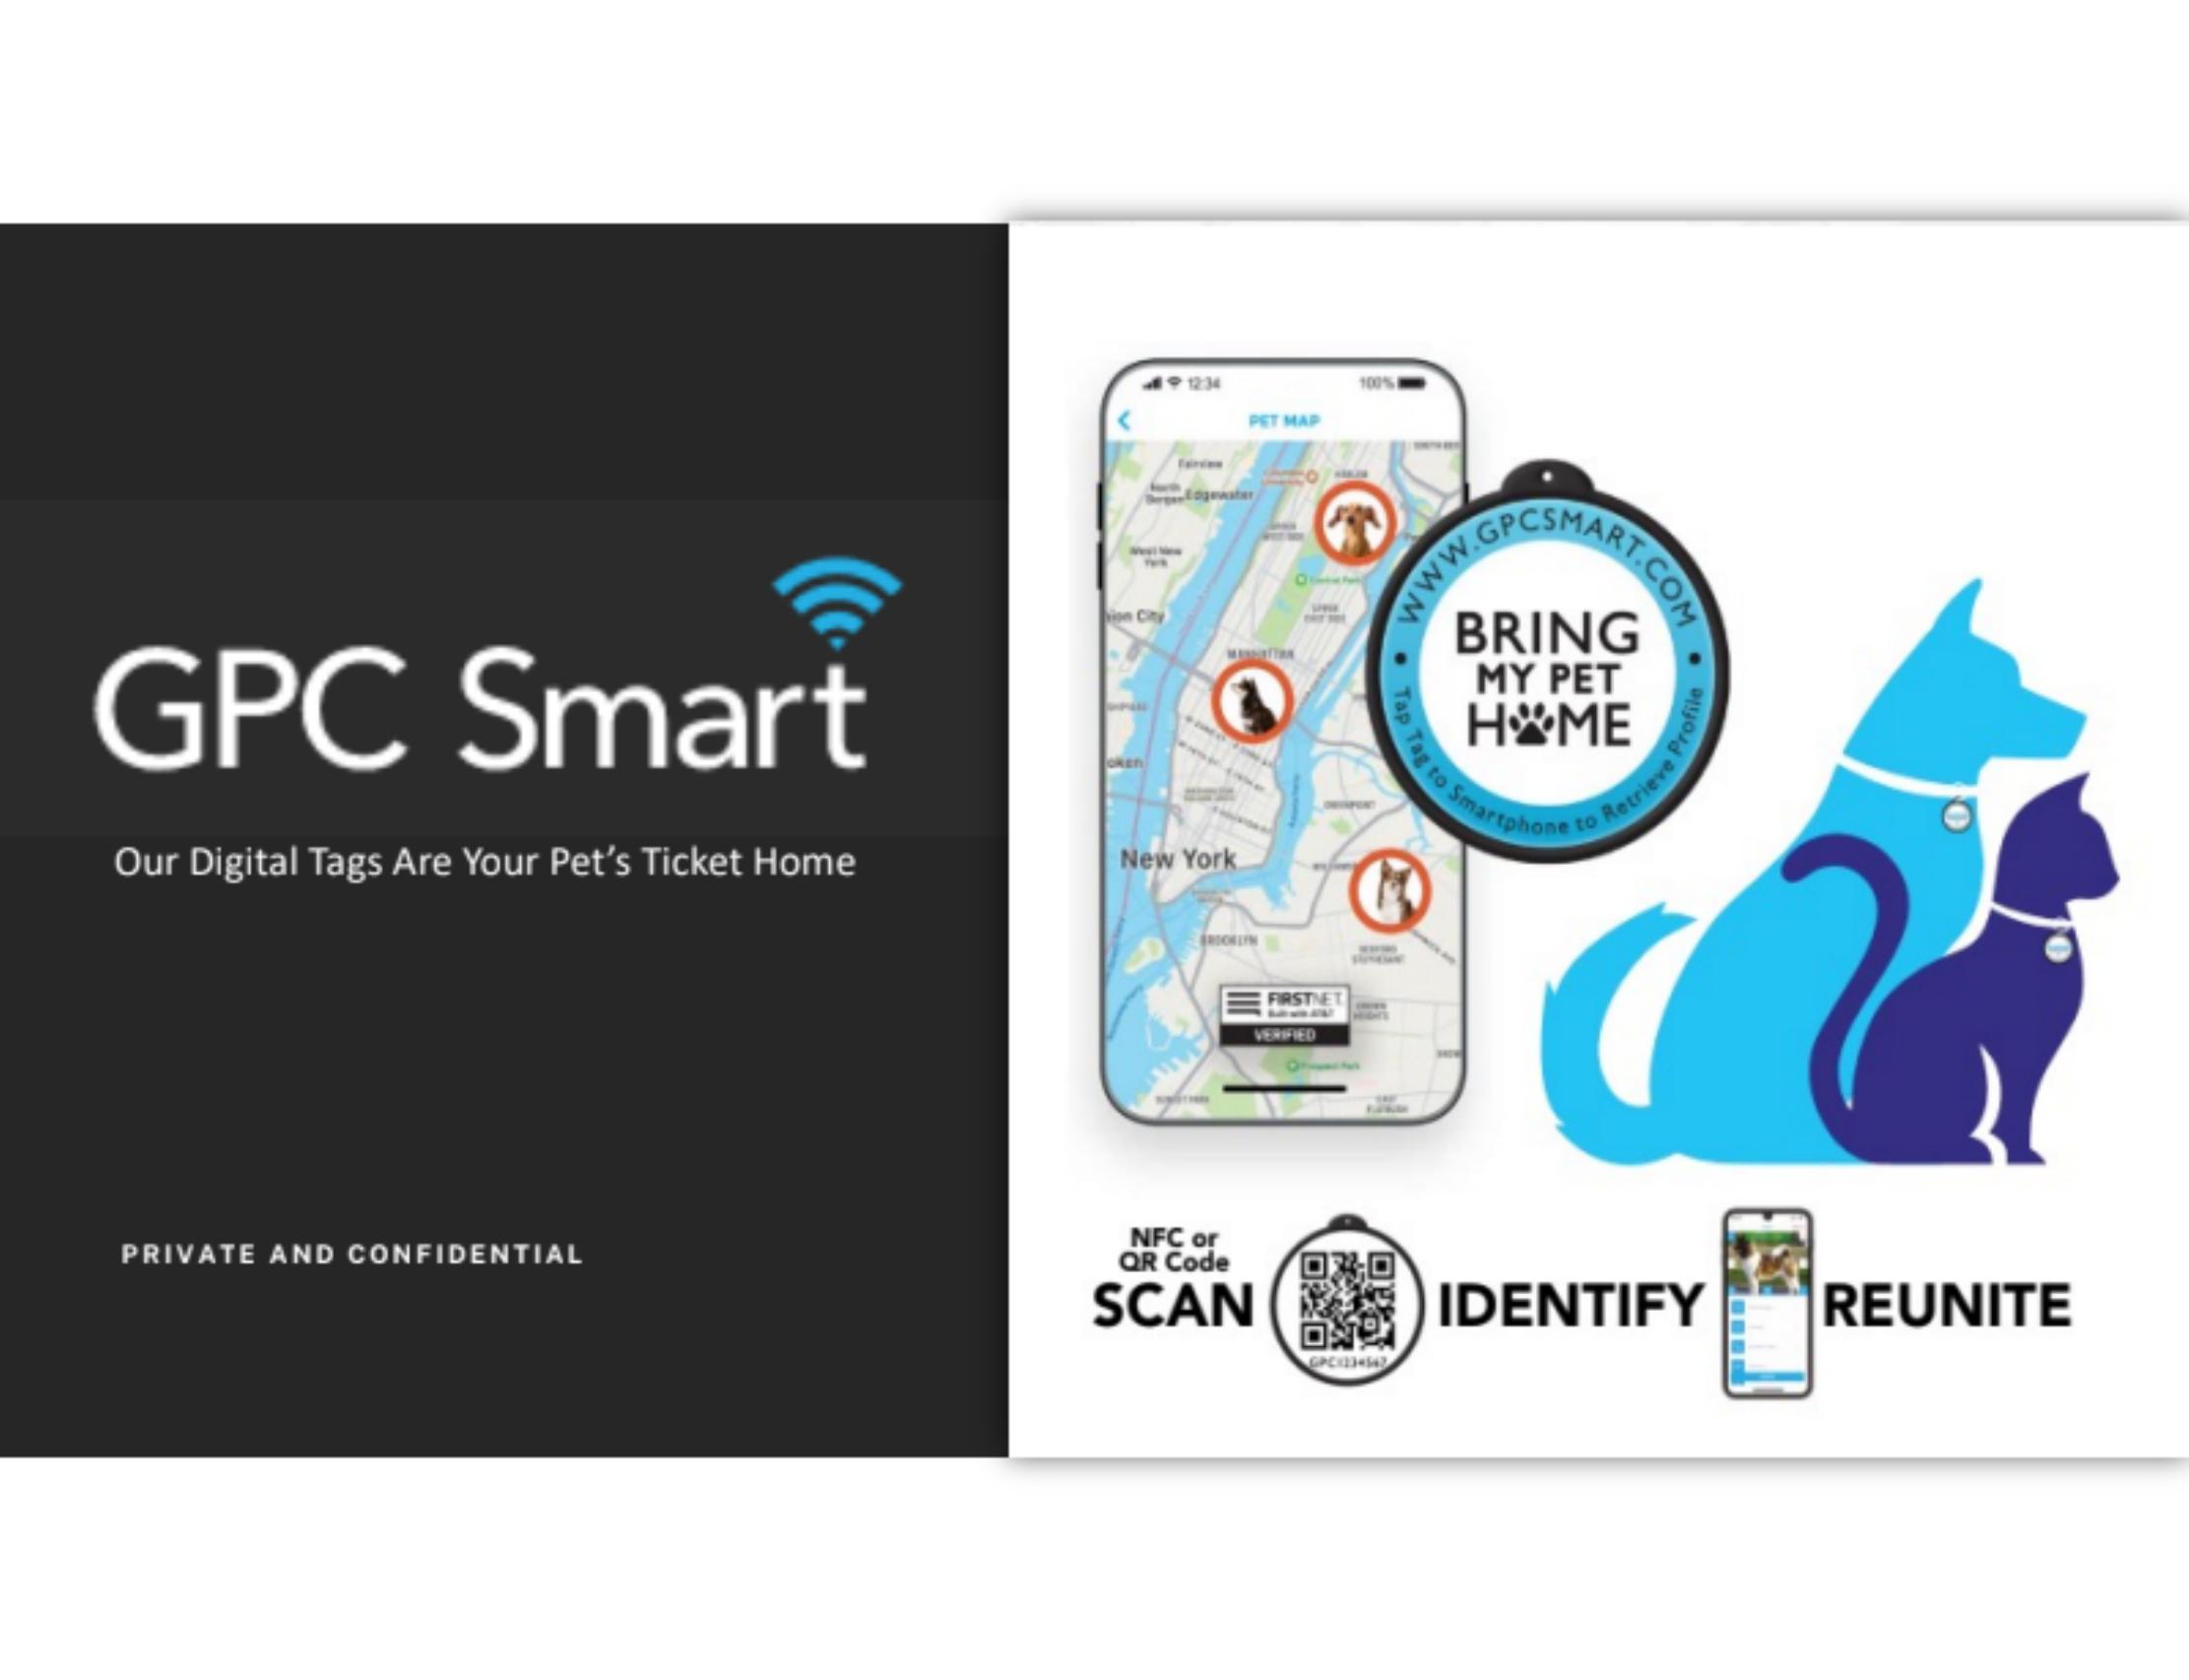
How to build a detailed financial model for Syneroid Technologies
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Syneroid Technologies model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Physical carbon-fibre NFC/QR tag (brand: GPC Smart) ships with a unique serial number.
- Tag scan (any smartphone, no app required) surfaces owner contact info, vet info, pet health/behavioural data, and notifies the owner with a mapped location.
- Companion mobile app (iOS, Android, FirstNet) lets owners mark pets missing, triggering geo-targeted push notifications and a "Lost Pet Website" listing.
- Centralized database crosses municipal boundaries - positioned as a universal pet registry.
- FirstNet® verified (AT&T emergency management network); manufactured by Avery Dennison; patented technology.
- Planned 911 data integration; compliant with H.R.3858 (2006 Federal Pets Act).
Market
- Global Pet Wearable Market: $2.1B - growing at 14.3% CAGR through 2030.
- US Pet Wearable Market: $696M - growing at 12.9% CAGR through 2030.
- 135M dogs & cats in the US; 27M born every year.
- 10M pets go missing each year in the US; <30% returned; 64% euthanised; $700/pet average municipal shelter cost.
- No SAM/SOM breakdown provided.
Revenue model
- Primary: hardware tag sale (price not stated in deck; competitors: engraved metal tags ~$15, microchips ~$50).
- Tag price: likely ~$20–30 per unit based on competitor pricing and implied ASP ($1.47M gross revenue / 185K units = ~$7.95/unit - this is surprisingly low; may include B2B bulk-discount volumes). ASP ~$8 derived from deck financials, but deck may bundle subscription or grant-subsidised units.
- Channels: B2B bulk (municipalities for digital pet registration, pet insurance, subscription boxes, shelters) and D2C (Amazon, veterinarians, pet stores, big-box retail).
- Subscription / data / SaaS revenue: not explicitly priced in deck; app is free to download. Potential recurring revenue not quantified.
- Grant funding available for cost reimbursement (municipalities) - revenue recognition implications unclear.
Traction & metrics
- 1 utility patent issued, 1 pending.
- Prototype created & beta tested.
- Mobile app live in Apple, Google, and FirstNet stores.
- Municipal partnerships in New York & California.
- FirstNet® Verified.
- Full-scale manufacturing by Avery Dennison.
- Active users in multiple US states.
- International distribution agreement in 24 countries.
- No revenue-to-date figure given; all financial data is forward-looking projections.
- Endorsement from former FEMA & Homeland Security Chief Administrator Peter Gaynor.
Unit economics
- COGS Year 1: $309K on 185K units = ~$1.67/unit - very low; likely manufactured cost of tag only.
- Gross Margin Year 1 (implied): ($1.47M - $309K) / $1.47M = ~79%.
- Monthly burn rate: $30K/month until break-even.
- Break-even target: Q3 2023 - note: deck appears to be pre-2023 given this forward-looking framing.
Competition / moat
- Direct competitors named:
- Engraved metal tags (~$15): no updatable info, no tracking, limited space.
- Injected microchips (~$50): invisible, requires vet/shelter scanner, <10% adoption.
- Moat: patented technology, FirstNet® verification, Avery Dennison manufacturing, universal cross-jurisdictional database, planned 911 integration, federal regulatory compliance (Pets Act), established municipal partnerships.
- GPS tracker competitors (Whistle, Fi) not mentioned in deck.
Team & funding ask / use of funds
- Thomas Ickovic (CEO): 40 years entrepreneurial experience, founded 8 companies with $25M+ exits, NYC/NYS/NPS partnerships.
- Renn Burke (COO): 15+ years Emergency Management Government Services, FEMA COOP certified.
- Richard Fry (Microchip Initiator): 32 years; ISO member; owns Unique Manufacturing Code 944.
- Bill Bruce (Board): former Director of Animal Services & Bylaws, Calgary; credited with best-in-world animal control model.
- Ossian B. Riday (Chief Engineer): 25 years; consumer, medical, automotive & military product development.
- Muhammad Awais (Product Lead): 10+ years electronics hardware / multi-layer PCB / wireless / embedded systems.
Funding ask:
- $500K seed; minimum ticket $50K; for 12.8% equity; $0 debt.
- Current valuation: $3.9M pre-money.
- Use of funds: marketing ramp-up, inventory, general operations - no founder compensation.
- Projected Year 5 valuation: $59.9M (based on 8× profit multiple).
Recommended financial model
- Archetype + why: Hardware + subscription (freemium) unit-economics P&L with a 5-year forecast. This is primarily a hardware-distribution business in Year 1–2, transitioning to a recurring-revenue base as registered users accumulate. The dual B2B/D2C channel structure warrants a channel-split revenue build. A 3-statement model is not needed at seed stage; a simplified P&L + cash runway model is appropriate.
- Forecast horizon & granularity: 5 years; Year 1 quarterly (per deck framing of Q3/Q4 profit), Years 2–5 annual.
- Key drivers & assumptions:
| Driver | Value | Source |
|---|---|---|
| Year 1 units distributed | 185,000 | - |
| Registered user conversion rate | 75% of units → 138K users | - |
| Gross revenue Year 1 | $1.47M | - |
| Implied ASP | ~$7.95/unit | - |
| COGS Year 1 | $309K (~$1.67/unit) | - |
| Gross margin Year 1 | ~79% | - |
| Burn rate (overhead + initial marketing) | $360K Year 1 | - |
| Marketing / R&D costs | $390K (% of sales) | - |
| Year 1 profit (Q3+Q4 only) | $420K | - |
| Monthly cash burn pre-breakeven | $30K/month | - |
| Breakeven timing | Q3 2023 | - |
| Year 5 projected valuation | $59.9M (8× profit) | - |
| Implied Year 5 net profit | ~$7.49M | - |
| Unit growth rate Years 2–5 | 40–60% YoY tapering to 25% - consistent with 12.9% market CAGR but assumes market share gains early on | |
| ASP escalation | flat or slight increase as B2C mix grows; B2B bulk likely discounted vs. D2C | |
| Subscription/SaaS revenue per registered user | $0 in Year 1 (not mentioned); potential $5–10/yr in Years 2–5 if monetised - high uncertainty | |
| COGS per unit | slight decline with Avery Dennison volume scale, ~$1.50–1.80/unit | |
| Marketing as % of revenue | 25–30% in Years 1–2, declining to 15% by Year 5 | |
| Headcount / OpEx | lean team; $30K/month burn implies ~$360K annual overhead pre-scale |
- Scenarios (Base / Bull / Bear - which variables flex):
- Base: 185K units Year 1, ~40% unit growth Years 2–3, 25% thereafter; no subscription revenue.
- Bull: B2B municipal/insurance deals accelerate unit volumes; subscription layer adds $5–8/user/yr from Year 2; international distribution activates.
- Bear: Retail channel slow to adopt; B2B deals delayed; units ~100K Year 1; burn extends past Q3 2023 breakeven.
- Required sheets / outputs:
- Assumptions - all drivers, toggleable for scenarios.
- Revenue Build - unit sales by channel (B2B bulk vs. D2C), ASP by channel, subscription users × ARPU.
- P&L - gross revenue, COGS, gross profit, opex (marketing/R&D, overhead), EBITDA, net profit.
- Cash Runway - starting cash ($500K raise), monthly burn, cumulative cash, breakeven month.
- Valuation Bridge - Year 5 profit × 8× multiple to confirm $59.9M target; sensitivity on multiple (6×–10×).
- KPI Summary - units distributed, registered users, ASP, gross margin %, monthly burn, months to breakeven.
Frequently asked
Is the Syneroid Technologies financial model free?+
Yes. The Syneroid Technologies model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Syneroid Technologies's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us

Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Other InsurTech Startup Financial Models
Browse another startup in the same category.
Ark Kapital
AI-powered precision lending platform for European tech startups, providing non-dilutive growth loans using real-time raw data analytics.

Battleface
Tech-enabled travel insurance platform covering high-risk and non-standard destinations globally, sold direct and via B2B2C partners.
Beam
Digital-first dental insurance company selling group dental (and ancillary) benefits to employers via brokers

Branch
Tech-enabled home & auto insurance company operating as a reciprocal exchange, selling bundled policies via embedded, direct, and agency channels.
Cachet
B2B2C insurtech marketplace offering flexible, usage-based insurance products to gig/platform economy workers via partnerships with ride-hailing, delivery, and gig platforms.

Caura
Mobile app that aggregates all car-related payments (parking, congestion/ULEZ, tolls, tax, insurance) into a single platform, with insurance comparison as a key monetisation layer.

Clark
Digital insurance broker (Makler) providing a robo-advisor + human expert hybrid platform to manage and purchase all insurance lines via mobile app

Counterpart
Digital MGA (managing general agent) selling D&O and management liability insurance to US SMEs via a tech-enabled underwriting platform.


