Bowling Alley Model
Operating Businesses Financial Model (Free Excel Download)
Forecast bowling-venue economics through lane bookings, league play, events, food and beverage, utilization, labor, rent, and refurbishment capex.

professionals from Deloitte
Used by professionals from
About this model
This model helps you assess a bowling alley or family entertainment venue. It connects lane usage, parties, league play, food and drink, and arcade income to the staffing, rent, maintenance, and equipment costs of operating the venue.
Use it to test a new concept, renovation, or acquisition. You can explore how pricing, guest volume, group bookings, and seasonal demand affect profit, cash flow, and value.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Bowling Alley Model
- Center inputs: Year-1 centers, new centers per year, lanes per center, games per lane, games per visit
- Utilisation: Year-1 utilisation with an annual ramp and a practical ceiling
- Revenue drivers: price per game, shoe-rental price and attach, food & beverage and arcade per-caps, league bowlers and season fee, events per center and average package price, per-line gross margins, price escalation
- Cost structure: floor and management comp and wage with benefits and wage growth; facilities & occupancy, utilities & maintenance, marketing and SG&A as % of gross profit; depreciation (% of revenue); tax
- Capital and working capital: maintenance capex %, center build-out cost per center, NWC % of revenue growth, base-year revenue
- Valuation: WACC, terminal growth, net debt, shares outstanding
- Operations sheet: center roll-forward, total lanes, utilisation ramp, games per lane, total games, customer visits, floor and management headcount, visits per FTE
- Revenue sheet: lane bowling, shoe rental, food & beverage, amusements & arcade, walk-in subtotal, league play, events & parties, total revenue
Bowling Alley Financial Model: A Guide to the Template
A bowling alley financial model translates lane capacity, guest visits, and per-cap spending into revenue, profit, and enterprise value. This template helps you evaluate a multi-location bowling and family entertainment center by connecting operating drivers to cash flow and a discounted valuation.
It is suited for assessing concepts, renovations, or acquisitions.
How Operating Drivers Build Volume and Capacity
The template starts with a center roll-forward, where opening locations plus new openings equal closing centers. Closing centers determine total lanes (closing centers times lanes per center), forming the capacity base.
- Each lane supports a mature number of games annually, and a utilization factor represents the share of that capacity actually filled. Utilization begins at a Year 1 input and ramps by a fixed number of percentage points per year, capped at a practical ceiling, reflecting that new centers take time to build league play and local following.
- Total games equal total lanes times effective games per lane. Customer visits then equal total games divided by games per visit, since a typical party or guest bowls roughly two games.
That visit count becomes the foundation for ancillary per-cap revenue and staffing needs.
From Volume to Revenue: The Per-Cap Engine
Revenue is constructed line by line. Lane bowling is total games times a price per game, escalated at a menu step-up.
- Shoe rental, food and beverage, and amusements and arcade revenue are visits times a per-cap amount, with shoe rental additionally scaled by the share of visits that rent. This structure means blended revenue per visit emerges from the mix, and growth in food and arcade spending can expand per-cap even with flat game volume.
- Center-driven league play (closing centers times league bowlers times a season fee) and events and parties (closing centers times annual events times average package price) layer on top. Each line has an explicit gross margin, which sets its cost of sales as line revenue times one minus that margin.
Costs, Margins, and Operating Profit
The cost structure separates cost of sales from operating expenses. Cost of sales is calculated per line: food and beverage carry a real product cost, arcade carries a redemption or prize cost, while bowling and shoe rental are nearly pure contribution.
- Floor and management labor are headcount-driven, based on full-time equivalents per center, wage rates, benefits loading, and annual wage growth. These labor costs sit in operating expense, not cost of revenue, so blended gross margin runs high.
- The remaining overhead stack, including facilities and occupancy, utilities and maintenance, marketing, and corporate SG&A, is set as a percentage of gross profit. This yields EBITDA as the key profitability line, with depreciation, taxes, and net income following.
Headcount scales with closing centers, and visits per FTE provides a productivity check.
Cash Flow and Valuation in Practice
Unlevered free cash flow is NOPAT plus depreciation, less maintenance capex and center build-out capex, less the change in working capital. Working capital is a modest call on cash because bowling and FEC operations collect at the point of sale and hold limited inventory.
- The heavy cash demand is the de novo build-out of new centers, which can push early free cash flow negative before scaling turns it positive. The discounted cash flow sums the present value of explicit free cash flows and a Gordon-growth terminal value to reach enterprise value, then subtracts net debt for equity value and value per share.
- Practically, you can flex assumptions such as lanes per center, utilization ramp, per-cap spending, league volume, and event bookings to see how revenue, gross profit, EBITDA, and enterprise value respond together.
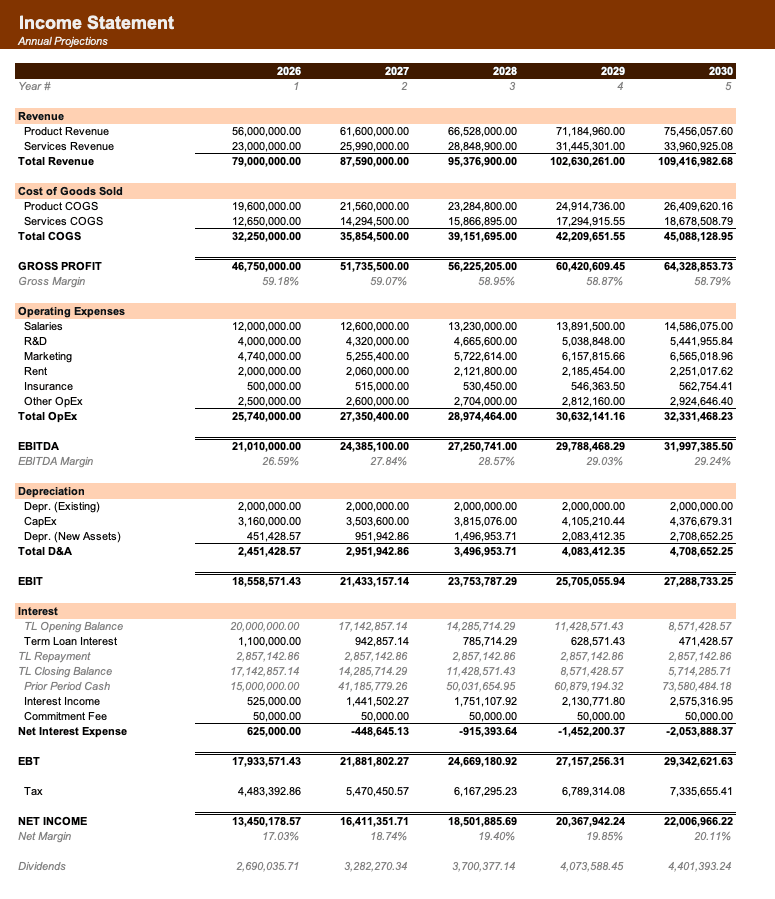
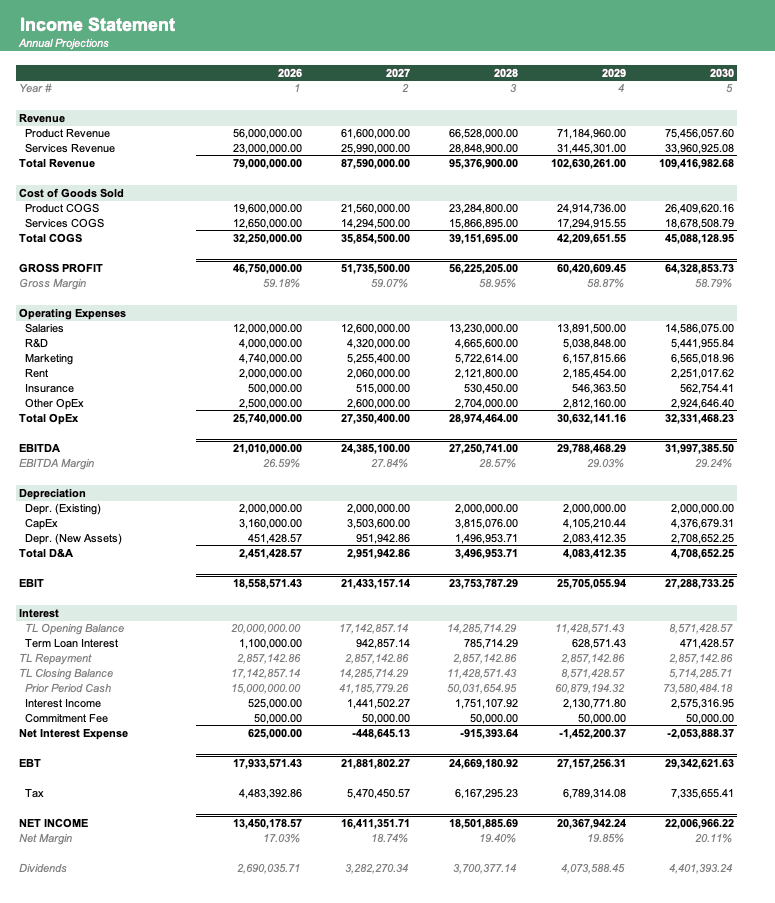
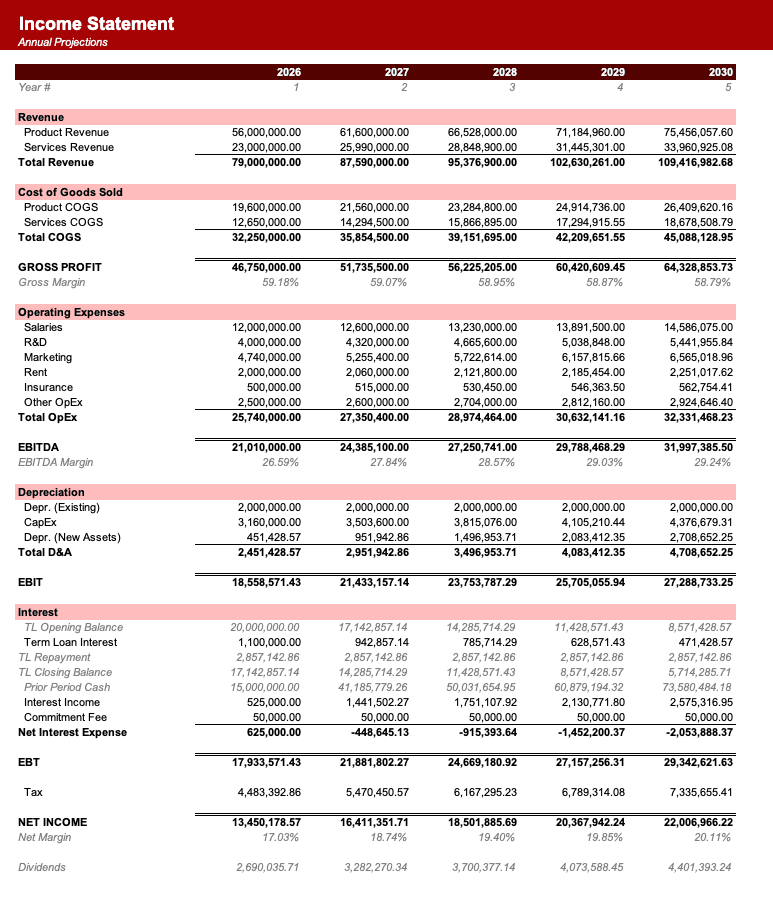
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a bowling alley financial model?+
A bowling alley financial model captures the seven-year operating economics and intrinsic value of a multi-location bowling and family-entertainment center (FEC) group that earns lane-bowling and shoe-rental revenue alongside food & beverage, an amusements and arcade floor, recurring league play and booked events and parties. It rolls a center count forward, converts a capacity-utilisation ramp into total games and customer visits, builds revenue off per-cap spend by line, runs the high-gross-margin two-crew labour cost stack to EBITDA, and discounts an unlevered free-cash-flow stream to enterprise value, equity value, and value per share.
How is bowling alley revenue built?+
Revenue is driven by the center estate and its utilisation: total games equal closing centers times lanes per center times mature games per lane times a utilisation factor that ramps to a ceiling, and customer visits fall out of total games divided by games per visit. Lane bowling is total games times a price per game, while shoe rental, food & beverage and arcade are visits times a per-cap; center-driven league play and events & parties layer on to total revenue.
Why is labour in operating expense instead of cost of sales?+
The people who run the lanes, the front desk, the bar and the kitchen are a fixed operating cost, not a per-unit cost of goods, so the model charges floor-and-lane and management-and-admin labour in operating expense and reserves cost of sales for the real product cost of food, beverage and arcade redemption. That keeps the gross margin high and makes the EBITDA margin, after labour and occupancy, the headline profitability measure.
Why an unlevered DCF instead of an EBITDA multiple?+
A bowling operator still builds out and equips each center with lanes, pinsetters and a fit-out and keeps them fresh with maintenance capex, so EBITDA overstates cash. The model bridges to unlevered free cash flow, NOPAT plus depreciation, less maintenance and build-out capex, less a light change in working capital, and discounts it at a WACC, then adds a Gordon-growth terminal value. The implied EV/EBITDA falls out as a sanity check rather than as the valuation input.
Have more financial modelling questions? Contact us
Related templates
Cinema Model
Plan and value a multiplex cinema circuit using screen count, admissions, concessions, film-hire costs, and a DCF.
Golf Course Model
Plan and value a golf course operator using rounds played, green fees, membership dues, operating costs, and a DCF.
Gym and Fitness Studio Operating Model
Operating model for fitness franchises and independent gyms including membership revenue, class scheduling, and facility utilization.
Food Manufacturing Model
Operating model for food production and processing businesses with ingredient sourcing, production scheduling, and margin analysis.


