Dividend Recap Model
Private Equity Financial Model (Free Excel Download)
See what a distribution policy actually costs. A 4.75x entry on 118 of EBITDA leaves a 735 equity cheque, and the policy pays 451 back over the hold - 61 per cent of the cheque - in three draws of 149, 118 and 183. What caps each one changes: the ratings ceiling of 5.00x binds at entry and again in Y1, Y3 and Y5, arranger appetite of 1.25 turns caps the first draw at 147, and in Y4 the credit has 100 of leverage headroom and still pays nothing because the restricted-payments basket is empty. The first draw splits 50 / 69 / 28 across first lien, second lien and PIK because the secured baskets run out before the quantum does. Against the same plan run with no draws at all, the policy lifts the annual return from 16.13 to 16.79 per cent and takes the money multiple from 2.11x to 1.99x - and at a 9.00x downside exit it adds five basis points and still costs 0.12x.

professionals from Deloitte
Used by professionals from
About this model
A sponsor's distribution policy across a five-year hold, built as a policy rather than as a single dated dividend. A facilities-services group is bought at 10.50x the 118 of entry EBITDA for 1,234 of enterprise value, funded with a 558 first lien term loan at 4.75x and a 735 equity cheque, and the model then asks the only question that matters to a recap: how much can be distributed in each year of the hold, and what stops it. Capacity is recomputed every year as the minimum of five independent tests, each struck on opening balances so nothing resolves circularly - a maintenance covenant of 6.00x total net leverage less a 0.75x cushion the sponsor refuses to spend, a self-imposed ratings ceiling of 5.00x, a cash interest cover floor of 2.25x converted into a quantum at the incremental margin, a restricted-payments basket of a 90 starter plus 60 per cent of cumulative consolidated net income less everything already paid, and an arranger appetite limit of 1.25 turns in a single draw. The basket only applies while pro-forma leverage sits above 4.25x, because credit agreements permit unlimited payments below that level - a gate that makes the policy self-regulating, since a large draw pushes leverage above the test and throws the sponsor back onto a basket the draw has just consumed. At the shipped assumptions capacity runs 54, 106, 173, 129, nil and 195: ratings binds four times, market appetite once, and in Y4 the basket alone stops a credit carrying 100 of leverage headroom from paying anything at all. The covenant and the cover floor never bind, which is the correct ordering - a sponsor prices a recap off the rating, not off a default trigger. Each quantum is then allocated down a secured waterfall, because the tests that set the size are total-leverage tests while the incremental facilities are sized off secured net leverage at 4.00x first lien and 4.50x secured. The gap between them is where a PIK note lives: the first draw of 147 splits 50 into incremental first lien, 69 into second lien and 28 into PIK, while by Y5 the baskets have rebuilt on a larger EBITDA and 161 of a 166 draw fits inside first lien alone. The PIK share of a recap is an output of where the credit sits, never an input, and because it accretes rather than paying cash it consumes leverage capacity without consuming cover. Distributions of 149, 118 and 183 come to 451 over the hold, a run rate of 90 a year and 61 per cent of the equity cheque returned before exit, with total net leverage never above 4.75x against the 5.00x ceiling and cash interest cover never below 2.66x against the 2.25x floor. The same operating plan is then run through a second, complete debt schedule with no draws in it, because the counterfactual is the denominator of the whole argument. Exiting 177 of Year 5 EBITDA at 10.50x gives 1,854 of enterprise value: without the policy that is 1,553 of equity for 2.11x and 16.13 per cent, with it 1,016 for 1.99x and 16.79 per cent. The policy buys 66 basis points of annual return and costs 0.12x of money multiple, and the trade gets worse as the exit gets worse - at a 9.00x downside it adds five basis points and still gives up 0.12x. That asymmetry, shown across all five exit cases, is the argument that actually gets had in an investment committee.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Dividend Recap Model
- Business and plan inputs: two revenue segments with their own growth and contribution margins, a margin ramp, field and central overhead with inflation, the sponsor monitoring fee, capex, depreciation, working capital intensity and tax
- Entry structure: the entry multiple, entry leverage, revolver commitment, transaction and financing fees and the minimum cash balance
- Debt terms: first lien, incremental, second lien and PIK margins, the commitment fee, scheduled amortisation, the cash sweep, issue discount by tranche and an arrangement fee on the quantum
- Distribution policy: a seasoning period, a minimum syndicable draw, capacity utilisation, the share of surplus cash released, and the starter and builder prongs of the restricted-payments basket
- Constraint limits: the maintenance covenant and the cushion, the ratings ceiling, the cash cover floor, arranger appetite in turns, and the first lien and secured ratio baskets
- Five exit multiple cases spanning downside to upside, plus the hold period
- Operating_Plan sheet: segment revenue, contribution, the cost base, EBITDA, EBIT, and unlevered free cash flow
- Entry_Structure sheet: purchase price, sources, uses, entry leverage and a sources-and-uses check
How the Dividend Recap Model Tests Capacity, Funds Draws and Measures Returns
This dividend recap model treats a recap as a multi-year distribution policy, not a single event. It calculates what can be paid each year, identifies which of five independent constraints binds, builds the funding stack from secured leverage baskets, and compares returns with and without the policy.
The public download is a values-only preview.
What Determines Annual Recap Capacity
Recap capacity in each year is the minimum of five tests, all struck on opening balances and current EBITDA so nothing resolves circularly.
- A maintenance covenant test uses a sponsor cushion; a ratings test applies a self-imposed total net leverage ceiling; a cash cover test ensures incremental cash interest leaves EBITDA above a floor; a restricted-payments basket builds from retained earnings and shrinks with prior distributions; a market test caps the quantum arrangers will syndicate in one draw.
- The tightest test wins, so capacity is customised by the actual credit position. The unlimited payments gate also matters: when opening group net leverage sits at or below a specified level, the basket test is switched off and capacity rests on the leverage tests alone.
A large draw can push leverage above that gate, closing the unlimited prong and forcing the following year onto a basket the draw has just consumed.
How a Draw Is Funded Across Debt Tranches
Capacity is a single number, but the funding stack is sized by separate secured leverage limits. Incremental first lien is capped by a first lien ratio basket less existing first lien debt; the remaining balance is tested against a secured ceiling, which includes first lien and any second lien net of cash.
- What will not fit in second lien headroom becomes a PIK note. Because secured baskets are tighter than the total leverage tests that set capacity, the tranche mix is an output of where the credit sits, not an input.
- The PIK note accretes rather than paying cash, so it consumes total leverage capacity but not cash interest cover. The model sizes the full quantum against the cash-pay cover test before allocation, which is conservative and means the actual cover ratio stays above the floor whenever PIK is used.
Returns Comparison With and Without the Policy
The model runs two full debt schedules over the same operating plan: a no-recap counterfactual and a post-recap policy schedule with draws layered in. Exit equity value differs only by net debt remaining, while the sponsor cash-flow stream includes annual distributions.
- A returns bridge lays both streams across five exit multiples and computes annual return and money multiple for each case. This shows the trade-off: a recap pulls cash forward and can lift IRR, but incremental debt reduces exit equity value and lowers the money multiple.
- The divergence widens at higher exit multiples and collapses at the downside case, so the case axis makes the asymmetry visible. The model reports the uplift in basis points and the cost in multiple turns side by side.
Practical Use and Operating Mechanics
This is a capital-structure model, not an operating model. A facilities-services plan supplies EBITDA and unlevered cash flow, while assumptions cover entry structure, debt terms and constraint limits.
- The sheet flow moves through operating plan, entry structure, the no-recap debt schedule, recap capacity and draw, post-recap debt, and the returns bridge. Draws are blocked during a seasoning period and below a minimum draw size, both shown as flags.
- Every year resolves in a fixed order: opening balances, cash interest, capacity, draw, then closing balances with amortisation, sweep and accretion. Draws carry no interest in the year made, cumulative net income and distributions lag one year in the basket, and the cash release is based on surplus above minimum cash, gated by the same eligibility flag as the draw.
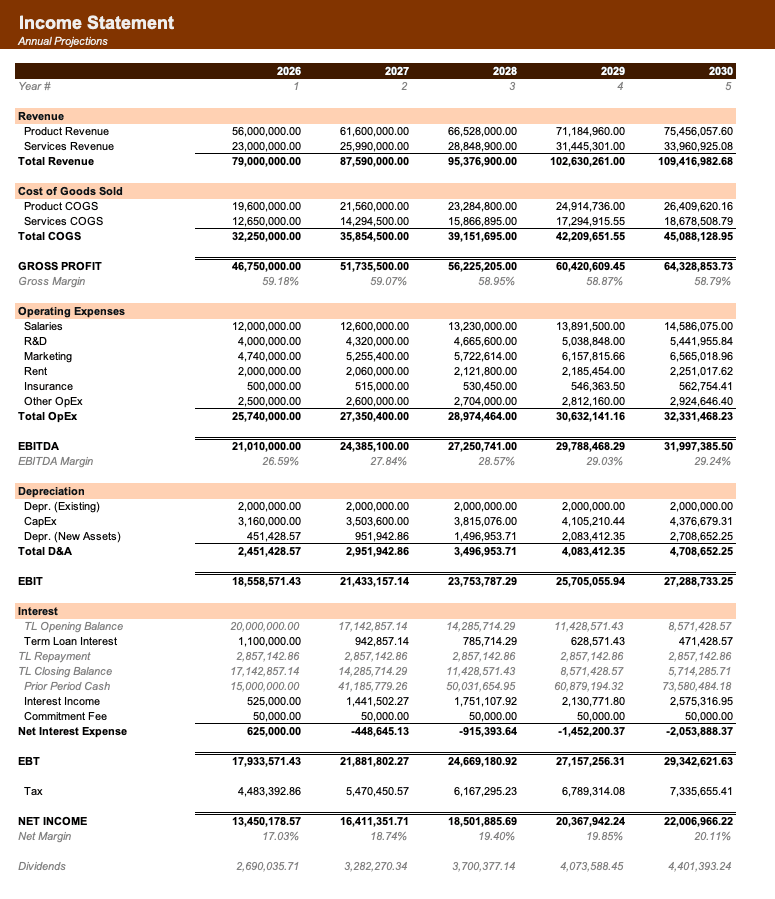
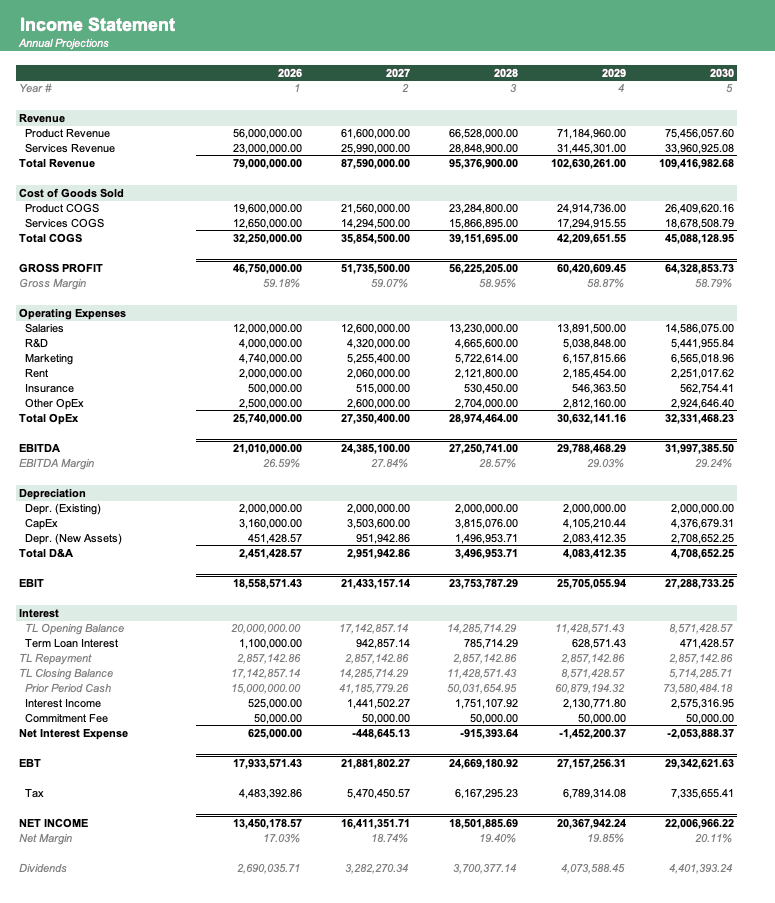
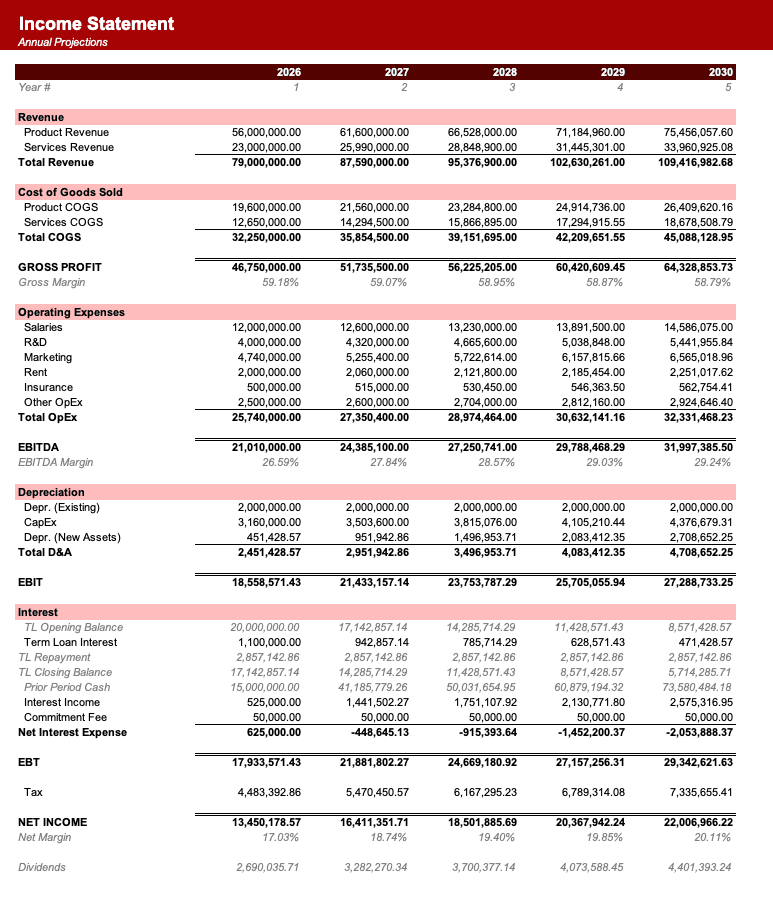
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a dividend recap?+
A dividend recapitalisation is a sponsor drawing new debt into a portfolio company and paying the proceeds out to itself as a dividend, rather than waiting for an exit to realise value. It does not change the business; it changes the capital structure and the timing of the sponsor's cash flows, which is why it lifts the internal rate of return and reduces the money multiple.
Why model it as a policy rather than a single event?+
Because a sponsor does not decide once. Capacity is retested every year against covenants, the rating, cash cover and the restricted-payments basket, and the constraint that binds changes as the credit deleverages and the baskets rebuild. Modelling one dated dividend hides the mechanic entirely - in this model, the year with the most leverage headroom is the year that pays nothing.
What is a restricted-payments basket?+
It is the capacity a credit agreement gives the borrower to pay money out to its owners. Typically it combines a fixed starter amount with a builder prong that accretes at a share of cumulative consolidated net income, and it is reduced by every payment already made. Most agreements also allow unlimited payments once leverage falls below a specified level, which is the gate this model implements.
Why does the basket matter more than leverage headroom?+
Because leverage headroom is necessary but not sufficient. In Y4 of this model the credit could carry another 100 of debt on every leverage test, and pays nothing, because the two earlier draws consumed the basket and leverage sits above the level at which unlimited payments are permitted. Documentation, not arithmetic, is what usually stops a recap.
Why does the model use a ratings limit as well as a covenant?+
They are different constraints. The covenant is a hard default trigger and a sponsor keeps well clear of it; the ratings ceiling is a self-imposed policy limit set inside the level at which the corporate family rating would come under pressure, and it is what arrangers price off. At a plan that performs, the ratings limit binds first - here four times out of six, while the covenant never binds.
Why is some of the draw a PIK note?+
Because the tests that set the size of a draw are total-leverage tests, while the incremental facilities are sized off secured leverage. When a quantum is larger than the remaining secured ratio baskets, the excess has to sit outside the security package, and a holdco PIK note is where it goes. The PIK share is therefore an output of where the credit sits, not an assumption.
Why does a PIK note not consume cash cover?+
Because it accretes into its own balance rather than paying a cash coupon. That is the reason it is used: it takes up total-leverage capacity while leaving the interest cover ratio alone. This model sizes the whole quantum against the cash-pay cover test before allocating, which is deliberately conservative, so the realised cover ratio comes in above the floor whenever PIK is issued.
Why does a recap raise IRR but lower money multiple?+
The distribution arrives years before the exit, so it is discounted less - that is the IRR uplift. But the debt that funded it stays on the balance sheet and is repaid out of exit proceeds, so the total cash the sponsor receives falls. Here the policy adds 66 basis points of annual return and gives up 0.12x of multiple at the base exit.
When does a recap stop being worth doing?+
When the exit disappoints. The uplift depends on the gap between the return the recap pulls forward and the return the business would have earned on that capital anyway. At a 12.00x exit this policy adds 106 basis points; at a 9.00x exit it adds five, and the 0.12x multiple give-up is unchanged. The asymmetry is why the case axis is in the model.
How is this different from an LBO model?+
An LBO model runs one capital structure from entry to exit. This one runs two - the policy and a no-draw counterfactual over the same operating plan - and spends most of its structure on the annual constraint suite and the tranche waterfall that a standard LBO never has to compute, because a standard LBO never adds debt after close.
Have more financial modelling questions? Contact us
Related templates
Leveraged Buyout Model
Complete LBO analysis with debt financing structures, sponsor returns, and sensitivity to exit scenarios.
Take-Private Model
LBO take-private model with premium to unaffected share price, debt financing flex, and rollover equity mechanics.
Management Incentive Plan Model
Private equity MIP model with sweet equity ratchet, paired IRR and MOIC hurdle gates, and dilution waterfall.
Venture Capital Fund Model
Model VC fund cash flows, distributed returns, and IRR by vintage year and exit scenario.


