Management Incentive Plan Model
Private Equity Financial Model (Free Excel Download)
See what the incentive plan actually costs. Management subscribe 2,040 for ten per cent of a 20,398 ordinary layer sitting under 165,227 of rolled-up loan notes, and a four-tier ratchet steps that share up as the sponsor crosses paired IRR and money-multiple hurdles - taking whichever of the two tests binds, and interpolating between rungs so nobody has a reason to hold an exit back. On the base case a 2.77x gross return grants a 15.80 per cent pool, vesting and leaver forfeiture cut it to an effective 14.46 per cent, and management's 2,040 becomes 40,871 - a 20.0x multiple. The sponsor's 178,585 returns 2.92x excluding the plan, 2.77x before the ratchet and 2.70x after it: 0.22 turns and 1.95 points of IRR, or 11.1 per cent of the equity value created.

professionals from Deloitte
Used by professionals from
About this model
A private equity management incentive plan modelled from the plan outwards rather than as a line item at the bottom of an LBO. The institutional strip is split ninety-ten between loan notes and a deliberately thin ordinary layer, and management subscribe for sweet equity alongside a cash co-investment, so the size of the pool is not an input but an output: a ratchet that steps the management share of the ordinary up as the sponsor crosses paired IRR and money-multiple hurdles, taking whichever of the two tests binds. The signature mechanic is that progress into each tier is measured separately on the IRR test and on the multiple test, bound by the weaker of the two and clamped between zero and one, so the ladder interpolates smoothly instead of jumping at a hurdle, and it is tested on the sponsor's pre-ratchet return - the drafting convention that keeps the calculation out of a circular reference, since a ratchet tested on post-dilution proceeds depends on its own answer. The sweet equity subscription is likewise solved algebraically rather than iterated: a gearing factor of the base pool over one less the base pool, applied to the ordinary share of the strip, sizes the sponsor cheque so the pool lands on exactly its base share. On the shipped base case a 34,000 EBITDA industrial services group is bought at 10.00x for 340,000, funded with 170,000 of senior debt at 5.00x and 185,625 of equity, of which management put in 5,000 of co-investment and 2,040 for ten per cent of the 20,398 ordinary. Two revenue segments carry the plan from 212,500 to 283,883 and EBITDA from 34,000 to 53,181 as margin walks from 16.0 to 18.7 per cent, while a full cash sweep takes net debt from 165,000 to 74,688 and leverage from 4.85x to 1.40x. Exiting at 11.50x gives 536,893 of equity, of which the 9 per cent rolled-up loan notes take 254,222 and the ordinary 282,671. The sponsor's gross return of 2.77x and 22.6 per cent clears the second tier outright and gets just over half way into the third, granting a 15.80 per cent pool against a 10 per cent base. Vesting then takes it back: five-year straight-line vesting behind a one-year cliff, six per cent of the pool leaving each year as good leavers who keep what has vested and hand back the rest, two per cent leaving as bad leavers who hand back everything, and sixty per cent of forfeitures regranted, leaves 91.5 per cent of the pool participating and an effective 14.46 per cent. Management's 2,040 becomes 40,871, a 20.0x sweet equity multiple and 7.7x blended across their co-investment, and the plan takes 11.1 per cent of the 351,268 of equity value created. The cost to the sponsor is read off three ways on the same cheque: 2.92x excluding the plan, 2.77x before the ratchet and 2.70x after it, a total of 0.22 turns and 1.95 points of IRR, of which the ratchet itself is 0.07 turns. Running the same ladder across exit multiples from 9.00x to 14.00x traces the whole curve - the granted pool widening from 12.59 to 18.74 per cent, sponsor net multiples from 2.11x to 3.26x, and the plan's share of value created from 7.0 to 14.3 per cent.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Management Incentive Plan Model
- Entry terms: LTM EBITDA, entry multiple, transaction and financing fees, minimum cash, senior leverage, rate, amortisation and tax rate
- Institutional strip terms: the loan note coupon, the ordinary share of the strip, the management co-investment and the hold period
- Operating plan: two revenue segments with their own growth paths and contribution margins, a central overhead with an inflation floor and a revenue flex, capex, depreciation and working capital intensity
- A five-rung ratchet ladder: a base pool plus four tiers, each with its own IRR hurdle, money-multiple hurdle and pool percentage
- Vesting terms: vesting period, cliff, good and bad leaver rates and the share of forfeitures regranted
- Participant allocation across the chief executive, chief financial officer, chief operating officer, divisional directors and the wider team
- Five exit multiple cases spanning downside to upside, all driven off one input row
- Entry structure sheet: sources and uses, the strip split, an algebraic sweet equity sizing that lands the pool on its base share without iteration, and ownership at entry
Management Incentive Plan Model: Hurdle Ratchets, Sweet Equity and Sponsor Cost
A five-year sponsor buyout built from the incentive plan outwards. Management subscribe for sweet equity in a thin ordinary layer, and the share they hold is set by a ratchet that steps up as paired IRR and money-multiple hurdles are crossed.
The model shows what the management incentive plan costs the sponsor on the same cheque. Rates and financial results described here reflect illustrative model settings, not industry benchmarks.
How the Paired Hurdle Ratchet Works
The ratchet ladder has a base pool and four tiers, each defined by both an IRR hurdle and a money-multiple hurdle.
- Progress into a tier is measured separately on each test, then bound by the weaker of the two and limited to between zero and one.
- A fully cleared tier contributes its whole step, while a partly cleared tier contributes its fraction, so the pool interpolates smoothly between hurdles rather than jumping at each one.
- In the base case, the sponsor's gross return clears Tier 1 and Tier 2 outright and reaches partway into Tier 3 on the IRR test, granting a pool above the base.
Solving the Sweet Equity Subscription
Management must end up holding exactly the base pool share of the ordinary, but the ordinary layer is itself a percentage of a sponsor cheque that shrinks by whatever management subscribe.
- The model solves the sweet equity subscription algebraically rather than iterating: it uses the base pool and the ordinary share of the strip to derive a ratio, then applies that to the available equity after co-investment. This determines the sponsor investment and the sweet equity subscription.
- On the shipped case, the subscription lands the pool on the base share of the ordinary to the cent, avoiding circularity.
Vesting, Leaver Forfeiture and the Effective Pool
The granted pool and the participating pool are different numbers. Vesting rolls the pool forward as a share of the original grant: good leavers keep what has time-vested and forfeit the rest, bad leavers forfeit vested and unvested shares alike, and a portion of everything forfeited is regranted to the remaining team.
- Time vesting is straight line over five years behind a one-year cliff. By exit, participating shares fall from 100% to 91.5%.
- The lapsed shares do not vanish; they revert pro rata to the holders of the residual ordinary. The exit waterfall therefore applies the effective pool, which is the granted pool multiplied by the participating percentage.
Reading the Sponsor's Cost Across Three Measures
Returns states the sponsor's outcome three ways on the same cheque: excluding the plan, before the ratchet, and after the ratchet.
- Excluding the plan holds no sweet equity at all; before ratchet uses the base pool only, which is the ratchet test basis; after ratchet applies the effective pool actually paid.
- The differences show the plan's cost in money multiples and IRR points on a comparable basis.
- The model tests the ratchet on the sponsor's return before giving effect to the ratchet shares, the common drafting convention that keeps the calculation out of a circular reference entirely.
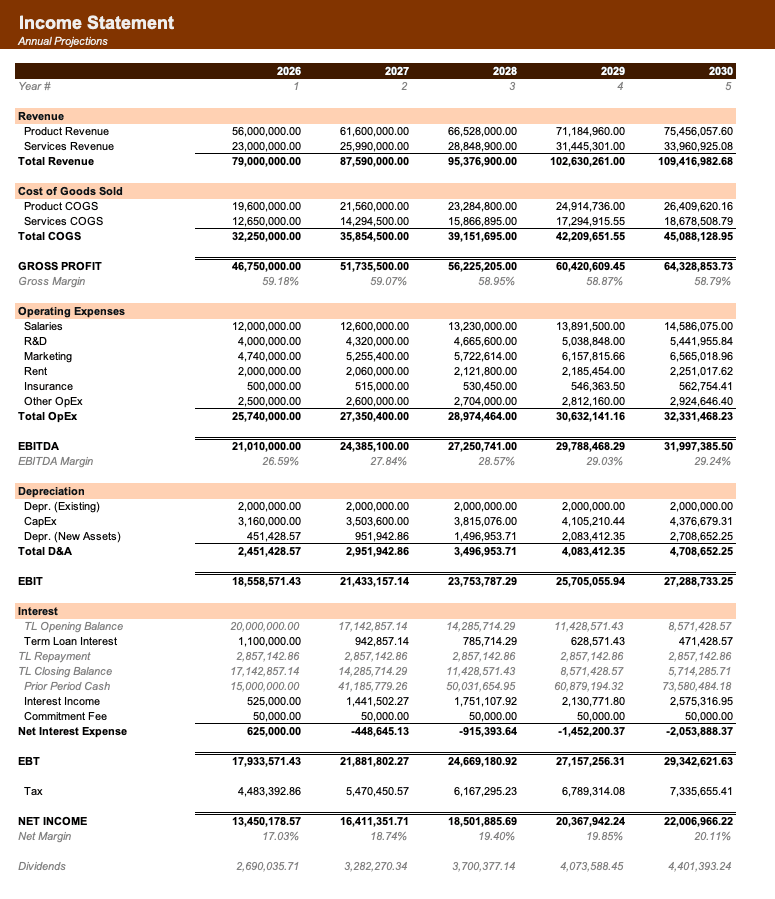
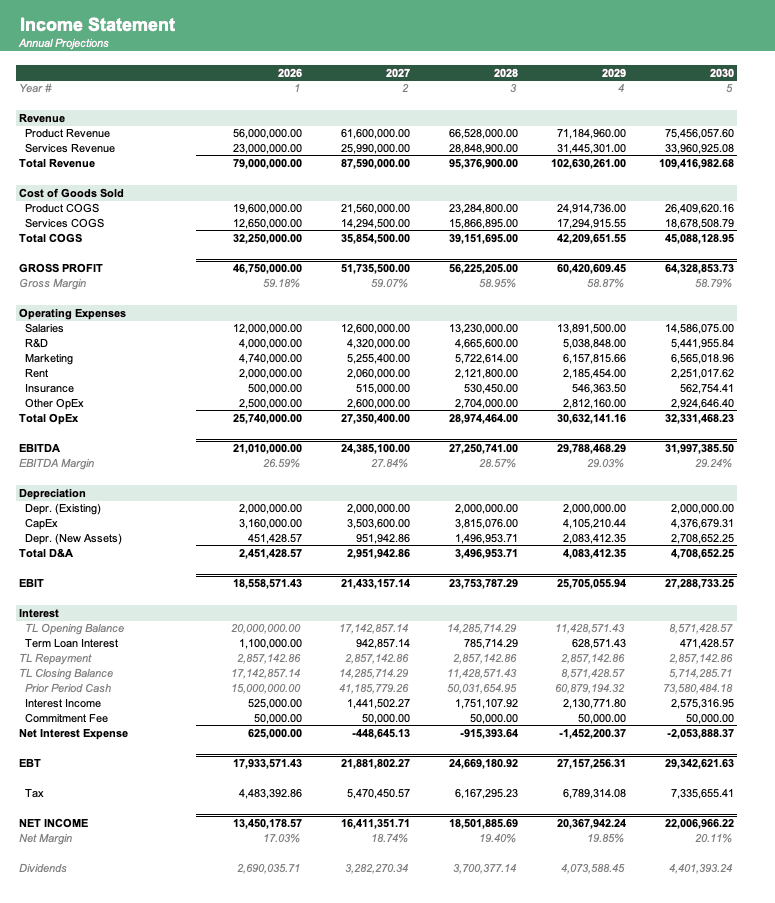
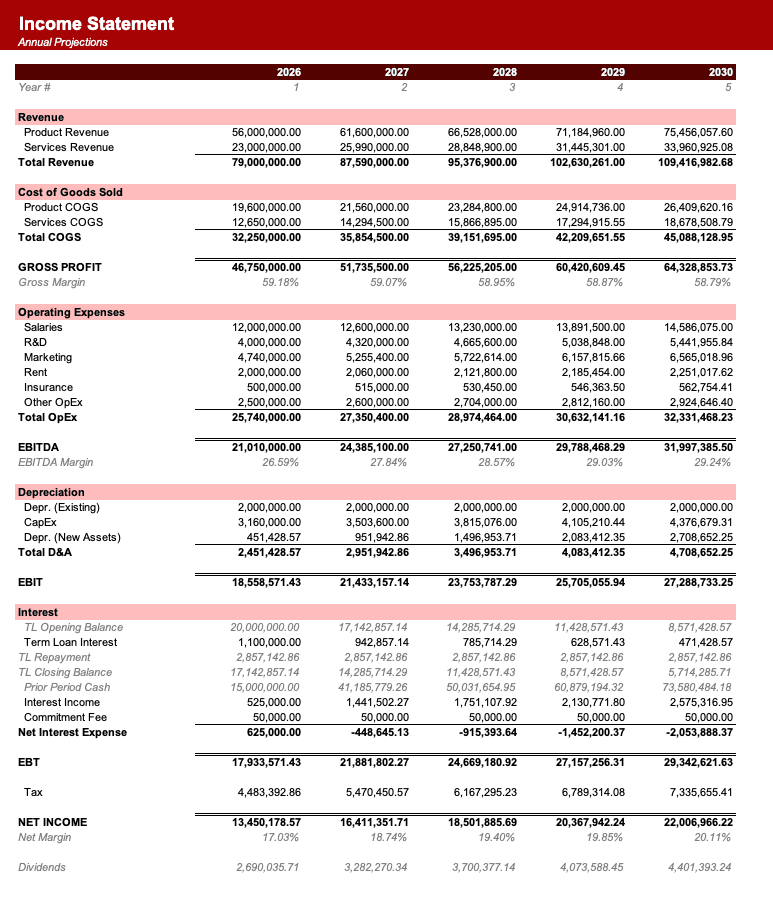
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a management incentive plan in private equity?+
It is the equity a sponsor gives the management team of a portfolio company so that their outcome tracks the sponsor's. In the common European structure the sponsor's money goes in as an institutional strip - mostly shareholder loan notes with a thin ordinary layer - and management subscribe separately for ordinary shares at a low absolute cost. Because the ordinary layer sits behind the loan notes, it is highly geared to the equity value created, which is what makes a small cash subscription worth a large multiple on a good deal.
What is sweet equity?+
Sweet equity is the ordinary shares management subscribe for outside the institutional strip. It is 'sweet' because management pay only for the ordinary, not for the loan notes, so they get the leverage of the ordinary layer without funding the debt-like part of the sponsor's investment. In this model 2,040 buys 10 per cent of a 20,398 ordinary layer that sits under 165,227 of loan notes; on the base case that 2,040 returns 40,871.
How does an equity ratchet work?+
A ratchet increases management's share of the ordinary as the sponsor's return crosses agreed hurdles. This model uses a five-rung ladder - a base pool of 10 per cent plus four tiers reaching 20 per cent - where each rung carries both an IRR hurdle and a money-multiple hurdle. Progress into a tier is measured on each test separately, bound by whichever is weaker, and clamped between zero and one, so the pool moves smoothly with the sponsor's return rather than jumping at each hurdle.
Why are IRR and money multiple tested together?+
Because either test alone can be gamed by timing. A quick exit can clear an IRR hurdle on a modest absolute gain; a long hold can clear a multiple hurdle on a poor annualised return. Taking the lower of the two progress measures means the ratchet only pays for outcomes that are good on both counts, which is why almost every real plan tests both.
Why is the ratchet tested on the sponsor's return before the ratchet?+
Because testing it on post-dilution proceeds makes the calculation depend on its own answer: the pool dilutes the sponsor, which lowers the sponsor's return, which lowers the pool. That circularity is normally resolved by iteration, which is fragile in a spreadsheet and hard to audit. Testing on the pre-ratchet return is both a common drafting convention and the reason this workbook contains no circular references at all.
What is the difference between a good leaver and a bad leaver?+
A good leaver - a retirement, an agreed departure, ill health - keeps whatever has time-vested and forfeits the rest. A bad leaver, typically someone dismissed for cause or leaving to compete, forfeits vested and unvested shares alike. The distinction is what gives the plan its retentive effect, and in this model it is what takes the participating pool from 100 per cent at grant to 91.5 per cent at exit.
How much should a management incentive plan cost the sponsor?+
Most sponsors underwrite a plan that takes between 8 and 15 per cent of the equity value created. On the shipped base case the plan takes 11.1 per cent of 351,268, costing the sponsor 0.22 turns of money multiple and 1.95 points of IRR on an unchanged 178,585 cheque. The ratchet component of that is only 0.07 turns; most of the cost is the base pool the sponsor agreed at completion.
How is this different from an option pool or an exit waterfall model?+
An option pool model tracks dilution across venture financing rounds in a cap table; there is no institutional strip, no hurdle and no exit test. An exit waterfall distributes proceeds across preference tranches with preferred returns and catch-ups. This model sits inside one portfolio company's ordinary share capital and answers a different question: how large management's slice of that ordinary becomes, and what it costs the sponsor to have promised it.
Have more financial modelling questions? Contact us
Related templates
Leveraged Buyout Model
Complete LBO analysis with debt financing structures, sponsor returns, and sensitivity to exit scenarios.
Exit Waterfall Model
Waterfall analysis for M&A, IPO, or sale with proceeds distributed to shareholders and securities holders.
ESOP Pool Model
Employee Stock Ownership Plan model with vesting, allocation, and dilution impact.
Venture Capital Fund Model
Model VC fund cash flows, distributed returns, and IRR by vintage year and exit scenario.


