
Enterprise value = the present value of explicit cash flows + the present value of a Gordon-growth terminal valueLaw Firm Model
Operating Businesses Financial Model (Free Excel Download)
Plan law-firm economics through matters, billable hours, realization, rates, partner mix, associate staffing, collections, compensation, and partner distributions.
DownloadSign up to downloadFree, no credit card required
Edit in Excelprofessionals from Deloitte
Loading...
Used by professionals from
About this model
This model helps a law firm plan revenue and profitability across its main practice areas. It links partners, associates, billable hours, pricing, and collections to the costs of delivering client work.
Use it to test hiring, utilisation, rate changes, and client mix. The summary shows how those choices affect profit per partner, cash flow, and the firm's value.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Law Firm Model
- Fee-earner inputs: Year-1 equity partners, new partners per year, leverage ratio, support-staff ratio, partner and associate billable-hour targets
- Utilisation: Year-1 utilisation with an annual ramp and a practical ceiling
- Rates and mix: standard hourly rate, realisation rate, rate escalation, four practice-group hour shares and rate indices, litigation success-fee uplift
- Cost structure: associate compensation and support wage with benefits and wage growth; occupancy, marketing & BD, technology & KM, PII insurance and SG&A as % of revenue; depreciation; tax
- Capital and working capital: maintenance capex %, fit-out per fee-earner, WIP & debtor lock-up % of revenue growth, base-year revenue
- Valuation: WACC, terminal growth, net debt, shares outstanding
- Headcount sheet: partner roll-forward, leveraged associate base, support staff, utilisation ramp, partner and associate hours, total billable hours, productivity
- Revenue sheet: four practice groups, fee revenue, litigation success fees, total revenue
Inside the Law Firm Financial Model: How Leverage, Rates and Cash Flow Drive Value
This law firm financial model projects a corporatized firm's revenue, profit and unlevered free cash flow over seven years. It links partners, associates, leverage and utilisation to practice-group billable hours and rates, then flows through costs, working capital and DCF valuation.
This article explains the model's operating drivers, calculation flow, outputs and practical use.
Operating Drivers: Leverage, Utilisation and Realisation
The law firm financial model treats leverage, the ratio of associates to equity partners, as the core profit engine. Equity partners roll forward at a constant net add; associates scale directly from the partner base; support staff follow fee-earners.
- Because associates earn fixed salaries but bill at the firm's rate card, wider leverage lifts gross margin and profit per equity partner. Utilisation—chargeable hours achieved against target—is a named input with an annual ramp and a practical ceiling, scaling both partner and associate hours.
- Realisation, the billed value net of write-offs and discounts, further adjusts revenue. Together, leverage, utilisation and realisation determine total billable hours and realised revenue.
From Billable Hours to Practice-Group Revenue
Total billable hours split across four practice groups—corporate & M&A, litigation, real estate and employment—using hour shares that sum to one. Each group applies the blended standard hourly rate, its own rate index, the realisation rate and an annual rate escalation.
- A contingent success-fee line geared to the litigation book captures disputes upside. This structure lets an analyst reweight practice mix or adjust rate indices to see how realised revenue per lawyer moves.
- The model reports revenue per lawyer alongside practice fee revenue and the success-fee layer.
Cost Structure and Profitability Metrics
Fee-earner delivery cost covers salaried associate compensation, headcount-driven and escalated by wage growth and benefits load, not set as a percent of revenue. Revenue less delivery cost gives gross profit.
- The overhead stack—support staff, occupancy, marketing, technology, insurance and SG&A—runs gross profit to EBITDA, then depreciation to EBIT and tax to net income. Equity partner compensation is the residual distributable pool, not an expense, so reported gross margin is high.
- The model reports pre-tax profit per equity partner (EBIT per partner) and EBITDA margin as the key profitability measures.
Free Cash Flow and DCF Valuation
The unlevered free cash flow bridge starts with NOPAT, adds depreciation, subtracts maintenance capex, fee-earner fit-out capex and the change in net working capital. Working capital reflects the sector's heavy cash-conversion lag, with WIP and debtor lock-up charged as a percent of revenue growth.
- The model discounts unlevered free cash flow at a WACC set above capital-intensive businesses. Enterprise value equals the present value of explicit cash flows plus the present value of a Gordon-growth terminal value.
- After subtracting net debt, the model reports equity value, value per share and implied EV/EBITDA.
income_statement.xlsx
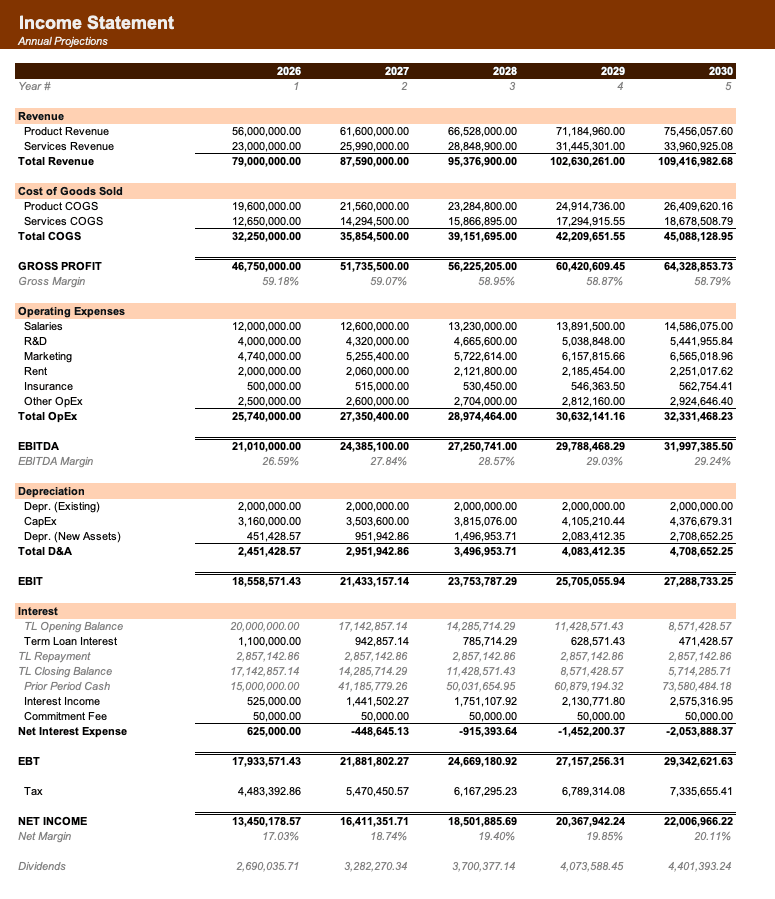
income_statement.xlsx
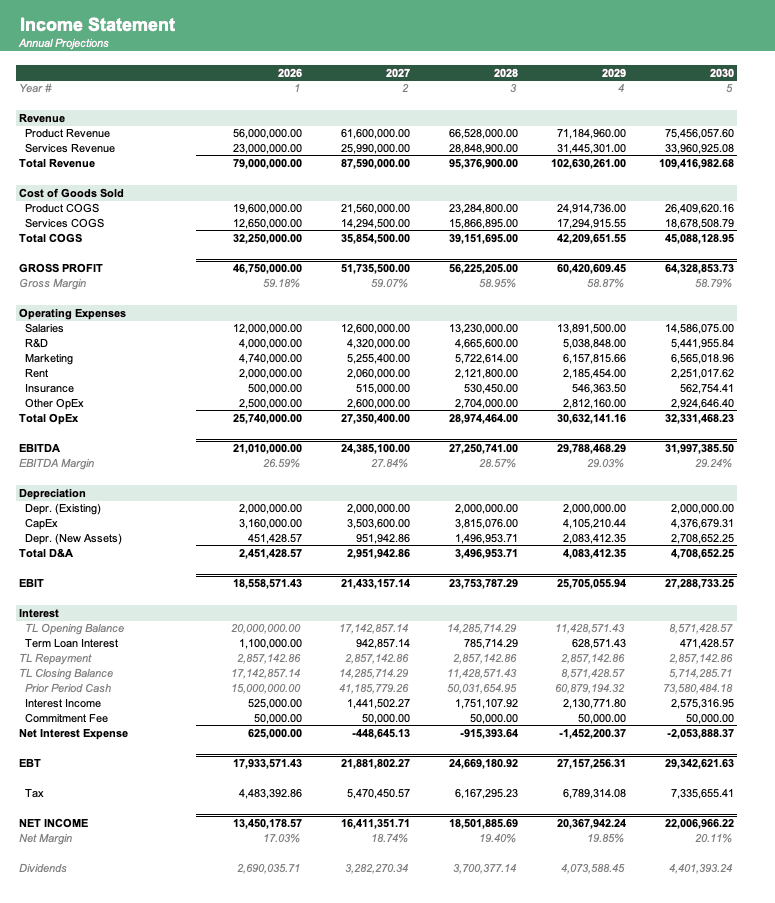
income_statement.xlsx
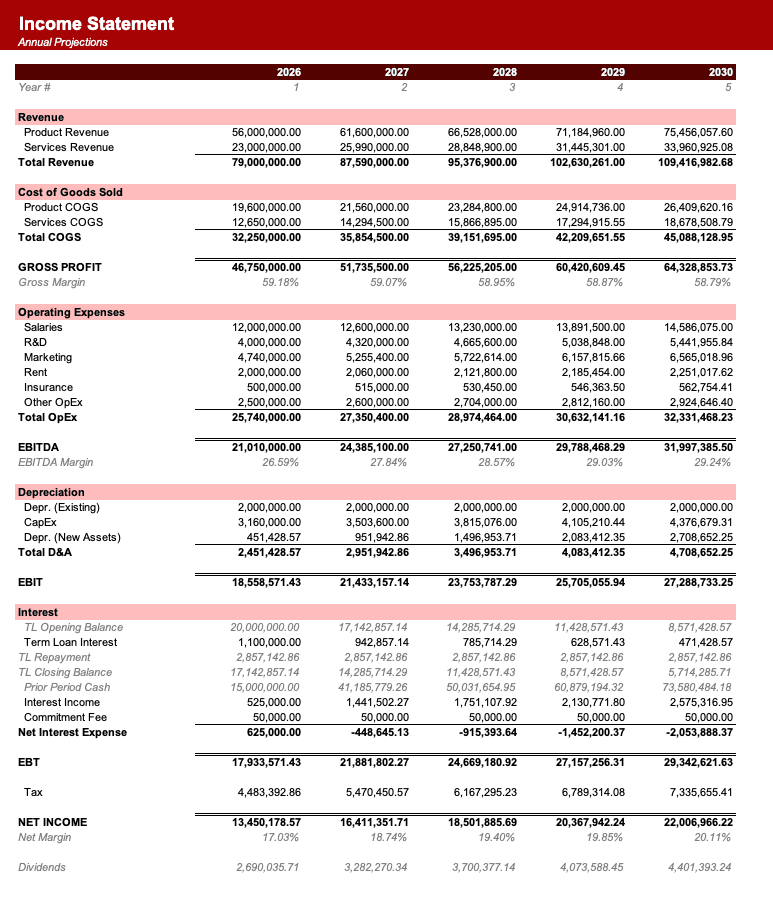
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
What is a law firm financial model?+
A law firm financial model captures the seven-year operating economics and intrinsic value of a full-service, corporatized law firm - the leverage-driven professional-services business that private-equity platforms and listed alternative business structures assemble out of independent partnerships. It rolls an equity-partner count forward, grows a salaried associate base off a partner-leverage ratio, turns billable-hour targets into total chargeable hours through a utilisation ramp, prices those hours across a four-practice mix at a blended rate, rate index and realisation rate, and discounts an unlevered free-cash-flow stream to enterprise value, equity value, and value per share while reporting profit per equity partner.
Why is leverage the key driver?+
Leverage - the ratio of salaried associates to equity partners - is the profit engine of a law firm. Associates bill hours well above their fully-loaded cost, and the spread accrues to the equity partners as the residual distributable pool. Because the model treats partner compensation as that residual rather than an expense, profit per equity partner rises directly with leverage, utilisation, realisation and the rate card, and the model lets an analyst flex each and watch PEP move.
How is profit per equity partner (PEP) calculated?+
PEP is reported on the industry-standard pre-tax basis: EBIT divided by the equity-partner count each year, which keeps it comparable to the AmLaw and Legal 500 benchmarks. Equity-partner compensation is not a cost line - it is the residual pool the partners draw - so the P&L runs to a net income before that draw, and the DCF applies entity tax so an after-tax unlevered cash flow can be discounted separately.
Why an unlevered DCF instead of an EBITDA multiple?+
A law firm ties up a large share of every revenue dollar in unbilled work-in-progress and uncollected debtors, so EBITDA overstates cash. The model bridges to unlevered free cash flow - NOPAT plus depreciation, less maintenance and fit-out capex, less the change in lock-up working capital - and discounts it at a WACC that reflects a people-dependent, goodwill-light asset base, then adds a Gordon-growth terminal value. The implied EV/EBITDA falls out as a sanity check rather than as the valuation input.
Have more financial modelling questions? Contact us
Related templates
Consulting_Firm.xlsx
Metric
2026
Revenue
--
EBITDA
--
Consulting Firm
Five-year pyramid model: headcount, utilization, billable rate, comp, and margins.
Staffing_Agency_Model.xlsx
Metric
2026
Revenue
--
EBITDA
--
Staffing Agency Model
Plan and value a staffing agency using recruiter capacity, worker placements, client billing, and operating costs.
CRO_Dashboard.xlsx
Metric
2026
Revenue
--
EBITDA
--
Chief Risk Officer Dashboard
Aggregate risk metrics and exposures across the organization with heat maps and limits.
Food_Manufacturing_Model.xlsx
Metric
2026
Revenue
--
EBITDA
--
Food Manufacturing Model
Operating model for food production and processing businesses with ingredient sourcing, production scheduling, and margin analysis.