Creating Financial Models in Excel: The Essential Formulas
Key Takeaways
- A small toolkit does most of the work. Referencing, lookups, logic, aggregation, and time-value functions cover the overwhelming majority of what any financial model needs.
- Referencing discipline comes first. Anchor assumptions with
$, keep period columns relative, and use mixed references for two-dimensional grids. Most drag-fill bugs trace back to a missing dollar sign. - Prefer INDEX/MATCH or XLOOKUP over VLOOKUP. They match on labels rather than fixed positions, so they survive inserted columns and read cleanly - the reason index match is a finance-modelling staple.
- Respect the NPV trap. Excel's
NPVdiscounts the first value by one period; keep time-zero flows outside the function or useXNPV.IRR, by contrast, expects the initial outflow as its first value. - Use CHOOSE for scenarios, not nested IF. A single
CHOOSEkeyed to a toggle is the standard, extensible way to switch Base / Bull / Bear cases. - Never hardcode. Every number belongs on an assumptions sheet; every formula references it. This is what makes a model auditable, flexible, and trustworthy.
To go deeper on structure and layout, read our guide to Excel financial modeling best practices, and see the errors these formulas help you avoid in common financial modelling mistakes. When you are ready to wire these formulas into a full model, start from our 3-statement financial model guide.
Creating financial models in Excel comes down to fluency with a surprisingly small set of formulas. You do not need hundreds of functions - you need to know a core toolkit cold and know exactly when to reach for each one. This guide walks through the essential Excel formulas for financial modeling, organised by the job they do: referencing, looking up, applying logic, aggregating, and valuing cash flows over time. Every function comes with a worked example and the exact syntax you would type into a cell.
Ask ten analysts what separates a clean, auditable model from a fragile spreadsheet that breaks the moment someone changes an input, and most will point to the same thing: disciplined use of a handful of Excel formulas. The functions themselves are not exotic. What matters is using the right formula for each job, wiring everything back to a single assumptions block, and never hardcoding a number inside a formula.
This post covers the financial modeling formulas that show up in virtually every professional model - from a 3-statement build to a DCF to an LBO. We will group them by purpose so you can see the decision behind each one, not just the syntax. If you are learning excel formulas for finance from scratch, work through the sections in order; if you already model, skip to the lookup and time-value sections, which is where most avoidable errors live.
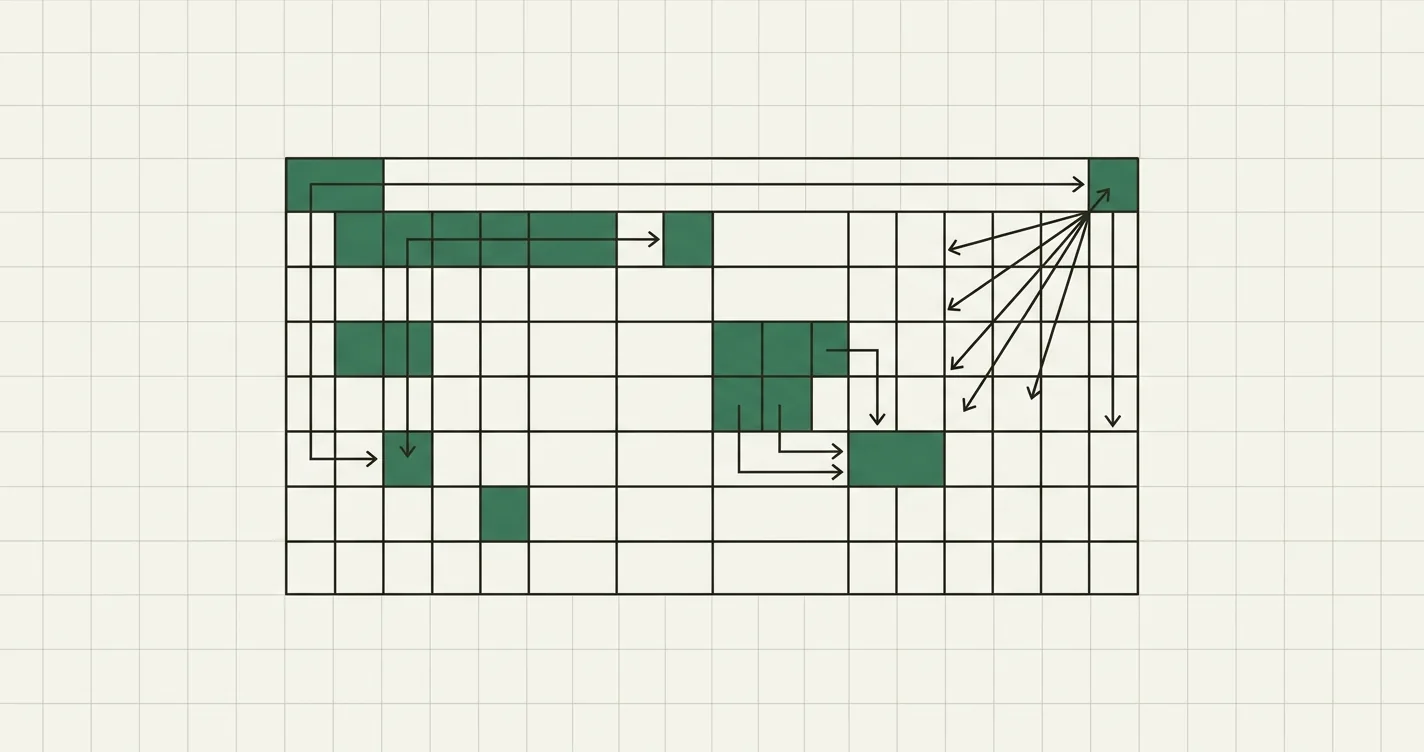
A decision tree for choosing the right Excel formula by the job it needs to do.
The Foundation: Absolute vs Relative References
Before any function, you have to get referencing right. This is the single most common source of drag-fill errors in financial models. Excel references come in three flavours, toggled with the $ sign (press F4 to cycle through them):
- Relative (
B2): shifts when you copy the formula across or down. - Absolute (
$B$2): locked to one cell no matter where you copy it. - Mixed (
$B2orB$2): locks only the column or only the row.
The rule for financial models: assumptions get anchored, period columns stay relative. When you build a forecast row that references a growth-rate assumption, the assumption reference must be absolute so it does not slide as you fill the row across the years.
// WRONG - the growth reference slides right as you copy across
= C5 * (1 + D2)

// RIGHT - growth rate is anchored, prior-period revenue stays relative
= C5 * (1 + $B$2)
Mixed references are the secret weapon for two-dimensional grids (like a sensitivity table), where you want the row input to always come from one column and the column input to always come from one row.
Lookup Functions: INDEX/MATCH and XLOOKUP
Lookups pull a value out of a table by matching a key. This is the backbone of any driver-based model - grabbing the right assumption for the right year, mapping a scenario toggle to a set of inputs, or pulling an actual from a data dump.
Why INDEX/MATCH beats VLOOKUP
Most beginners reach for VLOOKUP, but seasoned modellers prefer INDEX/MATCH (and, in modern Excel, XLOOKUP). Understanding index match for finance work pays off fast, because VLOOKUP has three weaknesses that cause real bugs:
- It can only look rightward - the lookup column must sit left of the return column.
- It references the return column by a hardcoded position number, which breaks the moment someone inserts a column.
- It is slower on large models because it scans every column up to the index.
INDEX/MATCH separates the two jobs: MATCH finds the position of your key, and INDEX returns the value at that position from any column you point at.
// Look up the 2027 revenue growth assumption from a table
// Years live in B4:F4, growth rates live in B5:F5
= INDEX(B5:F5, MATCH(2027, B4:F4, 0))
MATCH(2027, B4:F4, 0) returns the position of the year 2027 in the header row (the 0 forces an exact match). INDEX then returns the growth rate sitting in that same position on row 5.
Worked example. Suppose your assumptions table looks like this:
| 2026 | 2027 | 2028 | 2029 | 2030 | |
|---|---|---|---|---|---|
| Revenue growth | 20% | 15% | 12% | 10% | 8% |
= INDEX(B5:F5, MATCH(2027, B4:F4, 0)) returns 15%, because 2027 is the second entry and the second growth rate is 15%. Insert a new column, delete one, or reorder - the formula still returns the correct value because it matches on the label, not a fixed offset.
XLOOKUP: the modern one-formula answer
If your Excel version supports it, XLOOKUP collapses INDEX/MATCH into a single, more readable function and defaults to an exact match:
= XLOOKUP(2027, B4:F4, B5:F5)
Same result - 15% - with cleaner syntax. Use XLOOKUP when you know every user is on a recent version; fall back to INDEX/MATCH for maximum compatibility, since it works in every version ever shipped.
Logical Functions: IF, IFERROR and CHOOSE
Logical functions let a model respond to conditions - switch scenarios, cap a value, or handle a division that might blow up.
IF and nested IF
IF(test, value_if_true, value_if_false) is the workhorse. A common use is a debt sweep or a floor:
// Cash available for debt paydown cannot be negative
= IF(Cash_Flow_Available > 0, Cash_Flow_Available, 0)
Nesting IF statements works but gets unreadable fast. If you find yourself three levels deep, stop - there is almost always a cleaner tool.
CHOOSE for scenarios (not nested IF)
To toggle Base / Bull / Bear cases, CHOOSE is far cleaner than a chain of IFs. It takes an index number and returns the Nth argument:
// Scenario toggle in B1: 1 = Base, 2 = Bull, 3 = Bear
= CHOOSE($B$1, 0.10, 0.20, 0.02)
If B1 is 2, this returns 0.20 (the Bull growth rate). Adding a fourth scenario means adding one argument - no rewiring of nested logic. This is the standard pattern for scenario switches in institutional models.
IFERROR to trap #DIV/0! and #N/A
Division by a driver that can be zero, or a lookup that might miss, throws an error that then cascades through the whole model. Wrap it:
// Return 0 instead of #DIV/0! when the denominator is zero
= IFERROR(Revenue / Units_Sold, 0)
Use IFERROR deliberately, not as a blanket bandage - a stray error is often a signal that an assumption is wrong, and blindly hiding it can mask a real modelling mistake.
Aggregation: SUM, SUMIFS and SUMPRODUCT
SUMIFS for conditional totals
SUMIFS sums a range only where one or more conditions are met - invaluable for rolling up actuals by department, month, or category. The syntax is SUMIFS(sum_range, criteria_range1, criteria1, ...).
Worked example. Given this expense ledger:
| Department | Month | Amount ($000s) |
|---|---|---|
| Marketing | Jan | 12 |
| Marketing | Feb | 15 |
| Sales | Jan | 20 |
| Marketing | Mar | 18 |
| Sales | Feb | 22 |
Total all Marketing spend (assume Department in A2:A6, Month in B2:B6, Amount in C2:C6):
= SUMIFS(C2:C6, A2:A6, "Marketing")
This returns 45 (12 + 15 + 18). Add a second condition to isolate Marketing spend in February:
= SUMIFS(C2:C6, A2:A6, "Marketing", B2:B6, "Feb")
This returns 15 - the single February Marketing row.
SUMPRODUCT for weighted calculations
SUMPRODUCT multiplies aligned ranges element-by-element and sums the result - perfect for a weighted average cost, a blended rate, or a revenue build across price and volume.
// Total revenue = sum of (price x units) across three product lines
= SUMPRODUCT(Price_Range, Units_Range)
If prices are {100, 150, 200} and units are {10, 8, 5}, this returns 100*10 + 150*8 + 200*5 = 1000 + 1200 + 1000 = 3,200. One formula replaces a helper column of multiplications plus a SUM.
Time-Value Functions: NPV, IRR and PMT
This is where financial modeling formulas earn their keep - and where the most subtle errors hide. These functions turn a stream of cash flows into a value or a rate.
NPV - and its one big trap
NPV(rate, value1, value2, ...) discounts a series of cash flows to present value. The trap: Excel's NPV assumes the first cash flow arrives at the end of period 1, so it discounts every value by at least one period. If you have an outflow at time zero (today), you must add it outside the function.
Worked example. A project requires a $600k investment today and returns the following over five years, discounted at 10%:
| Year | Cash Flow ($000s) | Discount Factor (10%) | Present Value ($000s) |
|---|---|---|---|
| 1 | 100 | 0.9091 | 90.91 |
| 2 | 150 | 0.8264 | 123.96 |
| 3 | 200 | 0.7513 | 150.26 |
| 4 | 250 | 0.6830 | 170.75 |
| 5 | 300 | 0.6209 | 186.27 |
| Sum of PV | 722.2 |
The present value of the five inflows is about $722.2k. Subtracting the $600k invested today gives a net present value of about $122.2k:
// B2:B6 hold the Year 1-5 inflows; the -600 is today's outflow
= NPV(10%, B2:B6) - 600
NPV(10%, B2:B6) returns ~$722.2k, and subtracting the initial $600k outlay yields ~$122.2k. Because the NPV is positive, the project creates value at a 10% cost of capital.
XNPV for irregular dates
Real cash flows rarely land on neat annual anniversaries. XNPV(rate, values, dates) discounts each flow by its actual date, so it is the correct choice whenever timing is uneven:
= XNPV(10%, Cashflow_Range, Date_Range)
The first value/date pair is treated as time zero (not discounted), which also sidesteps the NPV end-of-period-1 trap.
IRR and XIRR
IRR returns the discount rate at which NPV equals zero - the project's implied annualised return. Unlike NPV, IRR does expect the initial outflow as the first value:
// A2:A7 hold: -600 (today), then 100, 150, 200, 250, 300
= IRR(A2:A7)
For the cash flows above, IRR returns approximately 16.4%. Since that comfortably exceeds the 10% discount rate, the positive NPV we calculated is confirmed. As with NPV, use XIRR when the cash flow dates are irregular.
PMT for loan and debt schedules
PMT(rate, nper, pv) returns the fixed periodic payment on an amortising loan - essential for debt schedules and real-estate models. Match the rate and period count to your payment frequency.
Worked example. A $500,000 loan at a 6% annual rate, repaid monthly over 5 years:
// Monthly rate = 6%/12; number of periods = 5 x 12 = 60
= PMT(6%/12, 5*12, -500000)
This returns $9,666.40 per month. Over 60 payments that totals about $579,984, of which roughly $79,984 is interest. (Enter the loan amount as a negative present value, or negate the result, so the payment comes back positive.)
Date Functions for Model Timelines
Period headers and schedules run on dates. Three functions cover almost every case:
EOMONTH(start, months)returns the last day of the month,monthsaway fromstart.= EOMONTH(DATE(2026,1,10), 0)returns 31 Jan 2026; using1instead returns 28 Feb 2026. This is the standard way to build month-end period columns.EDATE(start, months)returns the same day-of-month,monthsaway - useful for anniversary dates like contract renewals.DATE(year, month, day)assembles a real date from parts, which keeps timeline logic driven by an assumption (a model start year) rather than typed-in dates.
// First period end, driven by a start date in $B$1
= EOMONTH($B$1, 0)

// Each subsequent column: roll the prior period end forward one month
= EOMONTH(prior_period_end, 1)
Putting It Together: A Formula-Driven Revenue Build
Here is how these functions combine in a real forecast. Start with a Year 1 revenue of $10.0M and a growth-rate row on the assumptions sheet. Each year references the prior year and pulls its growth rate with an anchored reference (or a lookup):
| Year 1 | Year 2 | Year 3 | Year 4 | Year 5 | |
|---|---|---|---|---|---|
| Growth rate | - | 20% | 15% | 12% | 10% |
| Revenue ($M) | 10.00 | 12.00 | 13.80 | 15.46 | 17.00 |
The mechanics tie out step by step:
- Year 2:
10.00 x 1.20 = 12.00 - Year 3:
12.00 x 1.15 = 13.80 - Year 4:
13.80 x 1.12 = 15.46(15.456, shown rounded) - Year 5:
15.456 x 1.10 = 17.00(carry the unrounded prior-year figure)
// Year 1 revenue (input) references the assumptions sheet
= Assumptions!$B$3

// Year 2 onward: prior-period revenue x (1 + growth), growth pulled by lookup
= C10 * (1 + INDEX(Growth_Row, MATCH(D$9, Year_Row, 0)))
Every cell traces back to an assumption, nothing is hardcoded, and the row fills cleanly across all periods because the references are anchored correctly. Chain the same discipline through gross margin, operating expenses, working capital, and debt, and you have the skeleton of a full 3-statement model.
Common Mistakes to Avoid
- Hardcoding numbers inside formulas. Writing
= C5 * 1.15buries the growth assumption where no one can find or flex it. Always reference an input cell:= C5 * (1 + $B$2). - Forgetting the NPV end-of-period-1 trap.
NPVdiscounts the first argument by a full period. Never include a time-zero outflow inside the function - add it separately, or switch toXNPV. - Using VLOOKUP with a hardcoded column index. Insert a column and every
VLOOKUP(..., 4, 0)silently returns the wrong field. UseINDEX/MATCHorXLOOKUP, which match on labels. - Missing dollar signs on assumption references. A relative reference to a driver slides as you copy the formula across, quietly corrupting later periods. Anchor every assumption with
$. - Nested IF sprawl for scenarios. Four-deep
IFchains are unreadable and fragile. UseCHOOSEwith a scenario toggle instead. - Blanket IFERROR wrappers. Hiding every error masks real bugs. Trap errors only where a zero or blank is genuinely the correct answer, and investigate the rest.
- Mismatched rate and period in PMT. Feeding an annual rate with a monthly period count (or vice versa) produces a nonsense payment. Divide the annual rate by 12 and multiply the years by 12 for monthly loans.
Alex Tapio
Founder of Finamodel • Professional Financial Modeller • Ex-Deloitte