 Archer SPAC Financial Model
Enterprise/Security Startup Financials (Free Excel Download)



professionals from Deloitte
Used by professionals from






About this model
Archer is developing the Maker electric vertical-takeoff-and-landing aircraft for short urban trips. The aircraft is designed for four passengers, a 60-mile range, and a 150 mph cruise speed, with a stated goal of making city-to-airport travel faster and quieter than existing alternatives.
Its plan combines aircraft sales with a future urban air-mobility service. United Airlines placed a $1 billion order with an additional $500 million option, while Archer's manufacturing plan moves from lower-volume aerospace production toward scaled output with Stellantis after certification.
The SPAC model tracks transaction proceeds, trust redemptions, PIPE financing, and the pro forma ownership structure. Operating forecasts separately build OEM deliveries and aircraft pricing from ride-sharing revenue per seat-mile, then layer certification timing, fleet utilisation, manufacturing costs, and cash burn.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Archer SPAC
archer.com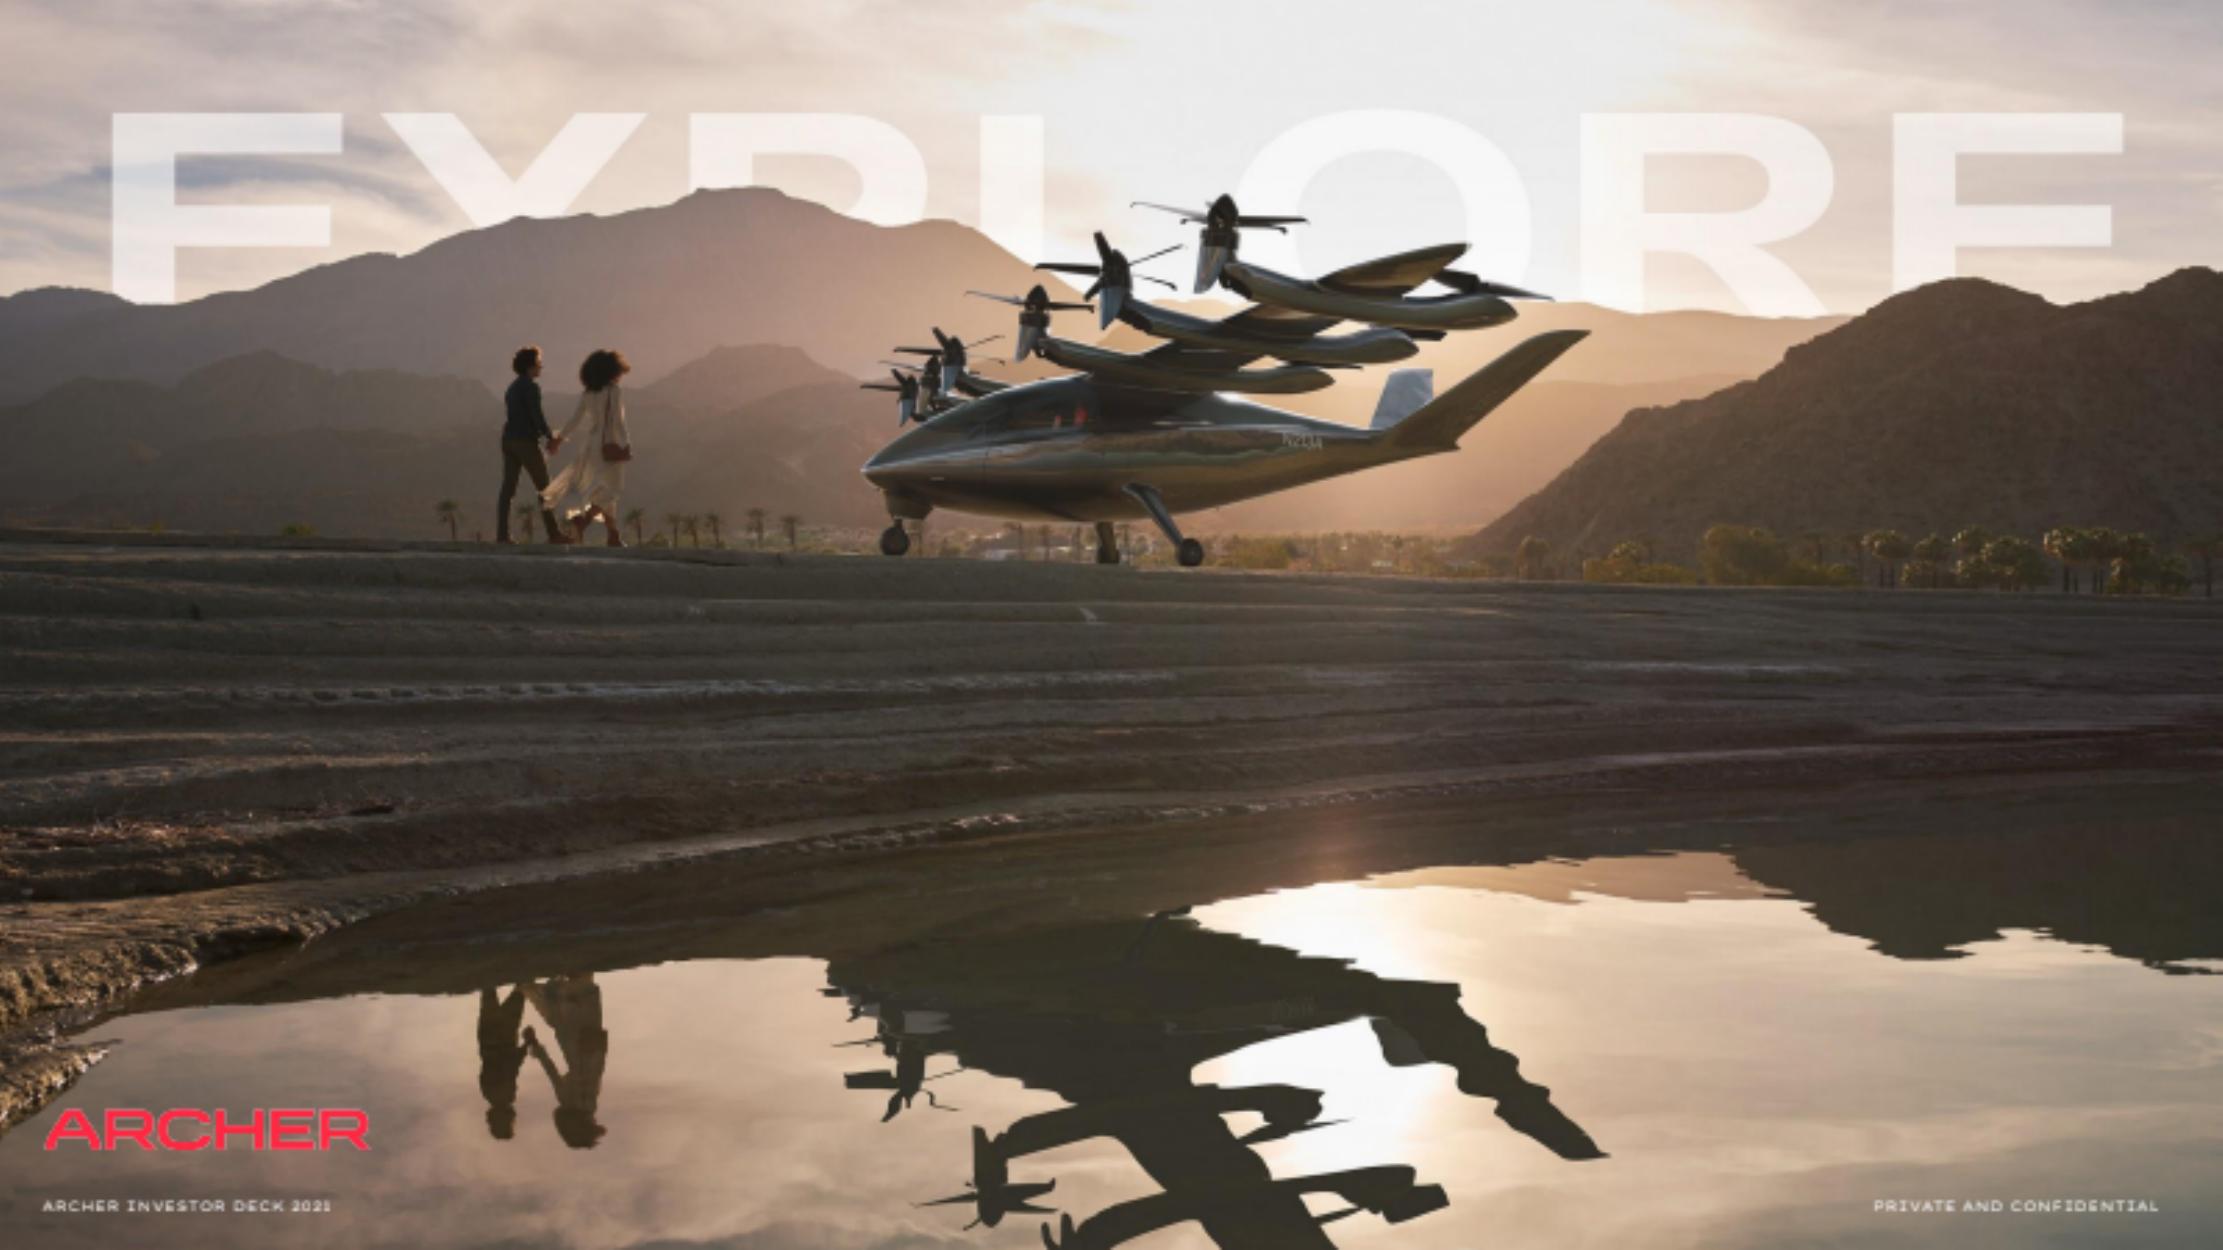
How to build a detailed financial model for Archer SPAC
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Archer SPAC model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Aircraft: "Maker" - eVTOL with 12 motors/propellers, high-aspect-ratio wing, carbon fiber composite airframe.
- Key specs: 60-mile range, 150 mph cruise, 45 dB noise (2,000 ft AGL - claims 100x quieter than helicopter), 4 passengers, zero emissions.
- Battery: "Meru" lithium-ion, 74 kWh / 672 kW max power.
- Cost target: $3.30/seat-mile (comparable to UberX).
- Value prop: 10x faster than car for urban routes (e.g., Manhattan–JFK in 7 min vs. 70 min UberX); priced at ~$50/trip vs. $1,775 helicopter.
Market
- Annual TAM: $1.5 trillion, comprising:
- Shared Mobility: $674B
- Airlines: $177B
- Cargo: $413B
- Military & Defense: $12B
- Key Accelerants (batteries, hardware, comms, software): $198B
- Upside TAM: $3.0 trillion by 2040
- Source: Morgan Stanley Research, "Flying Car Disruptor Series Update," October 2020.
- 2026E revenue of $2.23B represents <0.15% of TAM - no SAM/SOM breakdown provided.
- No SOM or market-share progression chart in deck.
Revenue model
Two segments:
Archer Direct - Aircraft OEM
- Sell eVTOL aircraft to airline/commercial partners.
- Anchor order: $1.0B from United Airlines + option for additional $500M.
- Aircraft delivery starting 2024 (post FAA Type Certificate).
- Future OEM markets (not in base forecast): cargo, DoD/military.
Archer UAM - Aerial Ride Sharing
- Operate own fleet for ride-sharing; revenue per seat-mile.
- Pricing: $3.30/seat-mile → ~$50/trip for a 25-mile route.
- 25 trips/day per aircraft at $3.30/mile over 25 miles → $2.4M revenue/aircraft/year (management projection).
- Operating model: own and operate fleet; costs decline via autonomy, scale manufacturing, battery improvement.
- OEM claimed to be 3x less profitable over aircraft life than UAM operations.
Manufacturing ramp:
- 2021–2026: Standard aerospace manufacturing, 200–1,000 aircraft/year.
- 2026+: High-volume manufacturing via Stellantis partnership, >5,000 aircraft/year.
Traction & metrics
- Orders: $1.0B from United Airlines (largest eVTOL purchase in history per deck); option for additional $500M.
- No revenue, no delivered aircraft as of deck date (2021).
- Team: 200+ years combined eVTOL experience; key hires from Wisk, Airbus Vahana, Piper, Mazda, Tesla.
- FAA certification: Process started 2020; Type Certificate targeted 2024.
- Battery: Meru flight worthiness testing began 2021.
- No customer count, no pilots, no flight hours cited as traction metrics.
Unit economics
All figures are management projections; no historical actuals.
Per eVTOL rideshare vehicle (annual, steady-state):
- Revenue: $2.4M
- Direct & Indirect Operating Cost: $1.4M
- Operating Income: $1.1M
- Implied operating margin: ~46%
Ride share economics basis:
- 25-mile trip at $3.30/seat-mile = $82.50 gross per trip (or ~$50 cited for NYC–JFK route - implies slightly different distance/pricing assumption)
- 25 trips/day × 365 days = $2.4M/year/aircraft
- Compared to ride-share car: $136,900/year → eVTOL generates ~18x more revenue per vehicle
OEM pricing: Not explicitly stated per-unit; implied from United order ($1B for undisclosed unit count).
Gross margin: Not broken out between segments in the deck; EBITDA margin shown at portfolio level (see §9 financial table).
Competition / moat
Competitive landscape (slide 27): Joby, Wisk, Lilium, Volocopter, EHang.
Archer differentiation claimed:
- Only eVTOL with a contracted airline order (United Airlines).
- U.S. FAA certification (vs. EASA or CAA for European/Chinese competitors).
- Designed for mass manufacturing from day one; Stellantis OEM partnership for composites.
- No battery energy advancement needed (unlike Lilium, Volocopter, EHang).
- 4-passenger piloted aircraft - same spec as Joby; differentiated from Wisk (2-pax autonomous) and Lilium (regional).
Moat: Regulatory head-start (FAA intake board approved 2020), United Airlines strategic partnership (equity holder + operational co-development), Stellantis composites partnership, proprietary battery (Meru) and flight software.
Team & funding ask / use of funds
Founders:
- Adam Goldstein & Brett Adcock - Co-Founders, Co-CEOs (previously co-founders of Vettery, acquired).
- Marc Lore - First/largest Archer investor; founder of Jet.com ($3.3B Walmart acquisition), Quidsi.com ($500M Amazon acquisition).
SPAC sponsor:
- Ken Moelis - Chairman, Atlas Crest; Founder & CEO, Moelis & Company.
- Michael Spellacy - CEO, Atlas Crest; 25 years in tech/aerospace advisory.
Transaction / capital raise:
- Pro forma enterprise value: $2,713M (~$2.7B)
- Pro forma equity value: $3,750M (375M shares × $10 ACIC share price)
- Cash to Archer balance sheet: $1,037M
- Sources: $500M SPAC cash in trust + $600M PIPE + $2,650M rolled Archer equity
- Est. transaction expenses: $63M
- Pro forma ownership: Existing Archer shareholders 67%, PIPE 16%, Public SPAC 13%, Founder shares 3%
- PIPE investors: United Airlines, Stellantis, Exor, Baron Capital, Federated Hermes Kaufmann, Mubadala, Putnam, Access Industries, Ken Moelis, Marc Lore ($30M combined).
Use of proceeds (2021–2025):
- ~$500M: Organizational buildout & R&D (certification, core tech, autonomy)
- ~$550M: Capital investments (manufacturing facility, in-house component manufacturing)
Valuation anchor: 1.2x 2026E EV/Revenue; 4.2x 2026E EV/EBITDA - presented as discount to comps (e.g., Tesla 2025: 8.7x rev / 46.5x EBITDA).
Recommended financial model
This is a SPAC/de-SPAC deal, not an operating startup model. The primary deliverable is a SPAC/de-SPAC model with an integrated operating forecast.
Archetype + why
SPAC/de-SPAC model with integrated operating forecast (dual-segment: OEM + UAM).
- Deal mechanics (sources & uses, pro forma cap table, ownership waterfall) must be modeled first.
- The operating forecast is long-horizon (2024–2030) and aircraft-production-unit-driven; it needs to tie back to the deal valuation (EV/Revenue, EV/EBITDA at 2026E).
- Two distinct P&L segments - OEM (per-unit aircraft sales) and UAM (fleet-operated ride-sharing, per-seat-mile) - with different margin profiles, capex intensity, and timing.
Forecast horizon & granularity
- Horizon: 2021–2030 (deal close through mature operations); deck shows 2024E–2030E financials.
- Granularity: Annual (deck provides annual figures; no quarterly breakout shown).
- Pre-revenue years (2021–2023): R&D/capex spend only.
- First revenue year: 2024E (10 aircraft produced).
Key drivers & assumptions
Deal mechanics:
- ACIC share price: $10.00
- Pro forma shares outstanding: 375M
- PIPE: $600M
- SPAC trust: $500M
- Transaction expenses: $63M
- Cash to balance sheet: $1,037M
Aircraft production volume:
| Year | Units |
|---|---|
| 2024E | 10 |
| 2025E | 250 |
| 2026E | 500 |
| 2027E | 650 |
| 2028E | 800 |
| 2029E | 1,400 |
| 2030E | 2,300 |
Revenue:
| Year | Revenue ($M) | Growth % |
|---|---|---|
| 2024E | $42 | NM |
| 2025E | $1,044 | 2,375% |
| 2026E | $2,230 | 114% |
| 2027E | $3,444 | 54% |
| 2028E | $4,709 | 37% |
| 2029E | $7,523 | 60% |
| 2030E | $12,335 | 64% |
EBITDA:
| Year | EBITDA ($M) | Margin % |
|---|---|---|
| 2024E | ($147) | NM |
| 2025E | $255 | 24% |
| 2026E | $647 | 29% |
| 2027E | $1,092 | 32% |
| 2028E | $1,551 | 33% |
| 2029E | $2,609 | 35% |
| 2030E | $4,520 | 37% |
Capex & Free Cash Flow:
| Year | Capex ($M) | FCF ($M) |
|---|---|---|
| 2024E | ($58) | ($205) |
| 2025E | ($265) | ($10) |
| 2026E | ($490) | $157 |
| 2027E | ($592) | $500 |
| 2028E | ($667) | $884 |
| 2029E | ($1,312) | $1,297 |
| 2030E | ($1,745) | $2,775 |
Unit economics inputs:
- Revenue per rideshare aircraft/year: $2.4M
- Direct & indirect operating cost/aircraft/year: $1.4M
- Operating income/aircraft/year: $1.1M
- Cost per seat-mile: $3.30
- Trips/day per aircraft: 25
- Average trip distance: 25 miles
Segment revenue split (OEM vs. UAM): Deck does not explicitly split revenue by segment year-by-year. Reasonable assumption: 2024 is 100% OEM (United Airlines order); UAM contribution grows from ~0% in 2024 to majority by 2027+ as fleet scales. Model should allow segment toggle.
OEM aircraft ASP: Implied ~$4.2M/unit based on 2024E revenue of $42M ÷ 10 aircraft. Flag for sensitivity - deck doesn't state per-unit price explicitly.
EBITDA-to-net income bridge: No D&A, interest, or tax disclosed. Pre-revenue and pre-cash-flow-positive through 2025, so net loss will exceed EBITDA loss in early years. Model D&A as % of capex; no debt per deal structure; NOL carryforward shields taxes initially.
FCF derivation: FCF = EBITDA − Capex (per deck definition); working capital and D&A adjustments not provided. Model FCF using EBITDA − Capex as shown; add D&A add-back and working capital build as separate assumptions.
Cash flow breakeven: Q4 2025.
Autonomy cost reduction: Margin expansion from 24% (2025) to 37% (2030) partly attributed to autonomy (no pilot cost from ~2028). Autonomy timeline: supervised 2027, remote 2028.
Manufacturing cost curve: Cost/unit declines as volume scales from 250 (2025) to 2,300 (2030). Deck implies this but gives no explicit per-unit cost by year. Model as declining COGS/unit with production volume (economies of scale + Stellantis partnership).
Scenarios
| Variable | Bear | Base | Bull |
|---|---|---|---|
| Aircraft production volume | 50% of deck | Deck figures | 120% of deck |
| OEM ASP | $3.5M | ~$4.2M [implied] | $5.0M |
| UAM trips/day per aircraft | 15 | 25 | 30 |
| EBITDA margin 2030 | 28% | 37% | 42% |
| Autonomy timeline | Delayed 2yrs | Per deck | On time |
| SPAC redemptions | 80% | 0% | 0% |
| FAA Type Certificate | 2026 (2yr delay) | 2024 | 2024 |
Required sheets / outputs
- Deal Summary - Sources & uses, pro forma cap table, ownership table (Archer shareholders / PIPE / public / founders), EV bridge
- Operating Forecast - Annual 2021–2030; aircraft production units, OEM revenue, UAM fleet revenue, combined P&L (revenue / EBITDA / EBITDA margin / Capex / FCF)
- Segment Build - OEM P&L (units × ASP, COGS, gross profit) and UAM P&L (fleet size, utilization, revenue/aircraft, operating cost/aircraft, segment income)
- Unit Economics - Per-aircraft economics for UAM (sensitivity on trips/day, ASP/mile, utilization rate, cost per trip)
- Valuation - EV/Revenue and EV/EBITDA at deal price vs. comps (Tesla, Joby, Blade, Airbnb, Lyft); sensitivity table on entry multiple vs. exit multiple
- Scenario Toggle - Bear / Base / Bull switch driving production volumes, ASP, margins, autonomy timing
- Cash & Runway - Uses of $1.037B proceeds vs. annual cash burn through FCF breakeven (Q4 2025)
Frequently asked
Is the Archer SPAC financial model free?+
Yes. The Archer SPAC model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Archer SPAC's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us

Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Other Enterprise/Security Startup Financial Models
Browse another startup in the same category.
AgBiome
AgBiome is a microbial-platform agtech company that discovers, develops, and commercialises biological crop protection products (and licences the platform across adjacent markets).
Alation
Enterprise data intelligence platform - data catalog, governance, and metadata management for large organisations.
Archera
Cloud resource automation platform that continuously optimizes AWS commitment purchases, de-risks overcommitment, and automates FinOps workflows.

Ardoq
Cloud-native Enterprise Architecture (EA) SaaS platform that helps large enterprises navigate digital transformation through automated data collection, graph-based architecture modelling, and change impact analysis.
Ascend
Ascend.io is an enterprise big data automation platform ("Enterprise Intelligence Platform") that abstracts away the complexity of big data engineering so non-experts can build and run data pipelines.
Athennian
Cloud-based legal entity management system (EMS) uniting entity data with workflow and document automation.
Auditboard
Cloud-based integrated risk management platform connecting audit, risk, compliance, and ESG teams across the enterprise.

BoostUp
AI-powered contextual revenue intelligence platform that automatically extracts unstructured digital sales data to replace manual CRM entry and power forecasting


