 Castor Financial Model
Biotech/Pharma Startup Financials (Free Excel Download)
SaaS platform enabling self-service decentralized clinical trials (DCT) for pharma, biotech, and research institutions.



professionals from Deloitte
Used by professionals from






About this model
Castor is a self-service platform for decentralised clinical trials, covering eConsent, data capture, monitoring, and EHR or data-pipeline imports. It follows ICH GCP, FDA Part 11, ISO 27001, GDPR, and HIPAA requirements, with 99% of customers reportedly building their own studies.
The SaaS product can be priced by study or module, with direct self-service and enterprise sales to research organisations, pharma, and biotech. The research does not disclose tiers, seats, ACV, or a meaningful services layer; its self-service design suggests implementation revenue should remain limited.
Castor supports more than 7,500 studies across 90 countries, 75,000 researchers, 2.6 million enrolled patients, and 250 million-plus data points. It powered the WHO SOLIDARITY trial. The model should forecast sponsor customers, studies, modules, ARR, expansion, churn, cloud cost, and support.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Castor
castoredc.com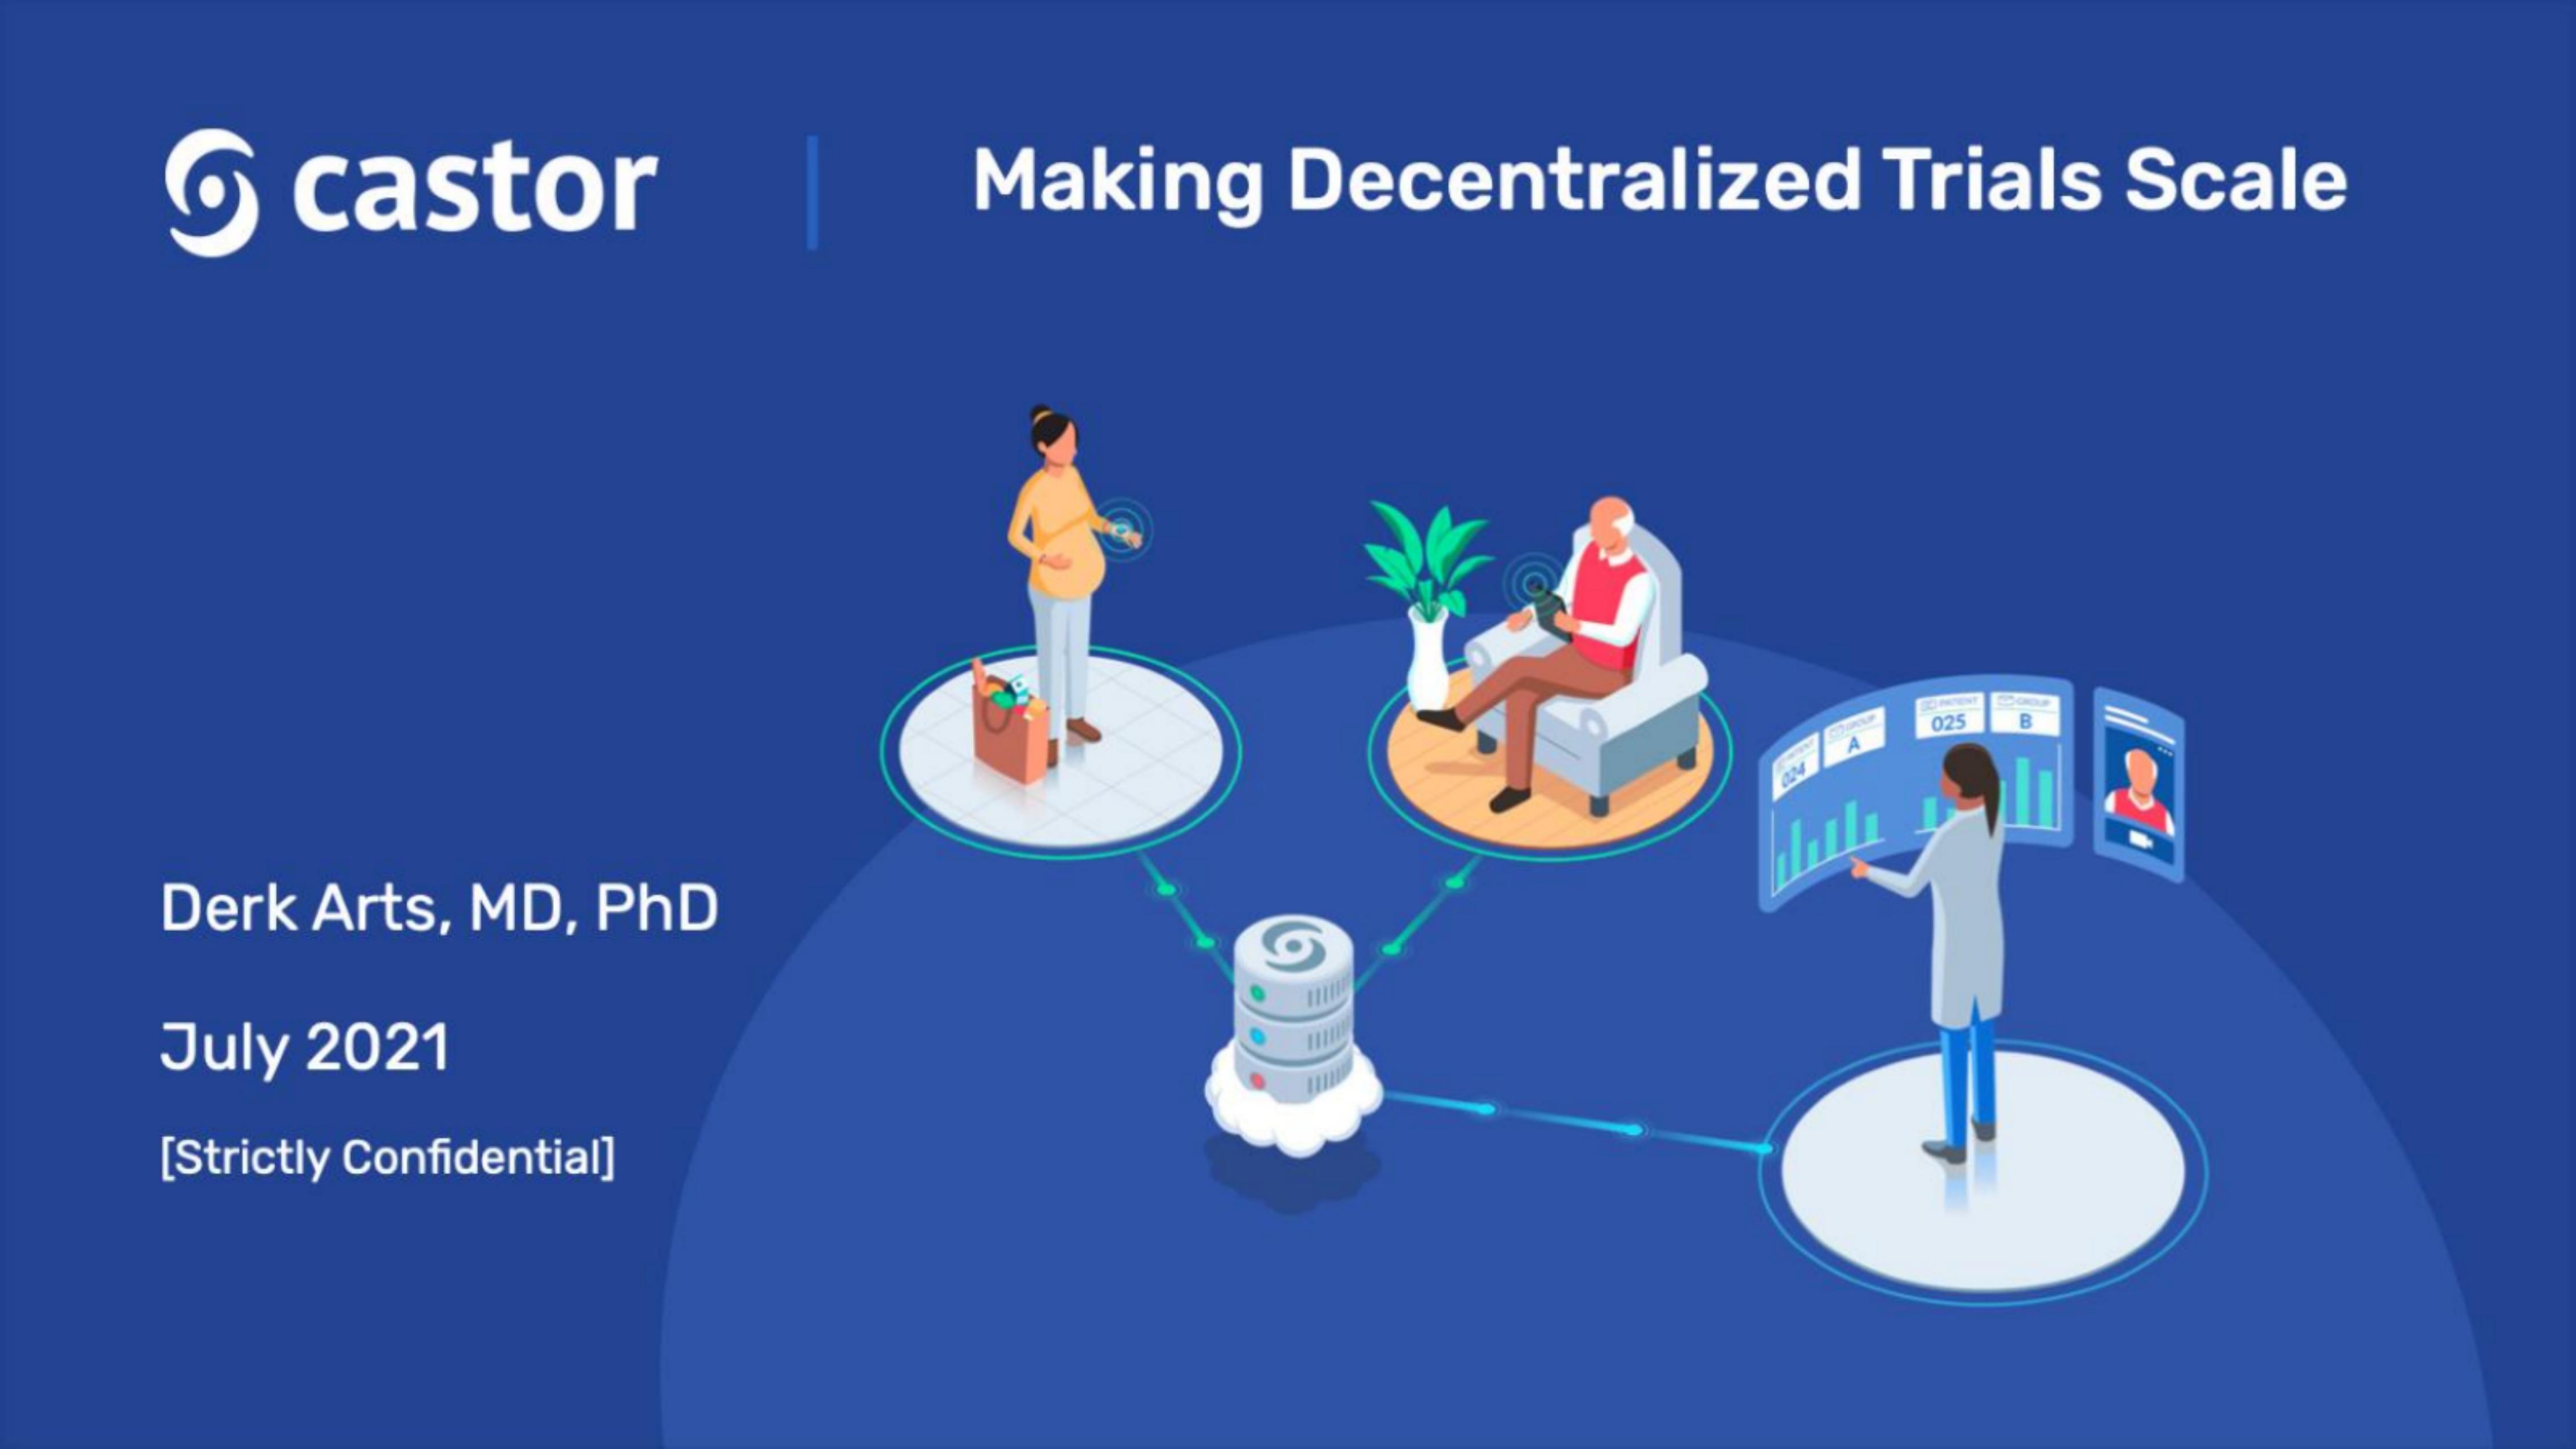
How to build a detailed financial model for Castor
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Castor model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Unified DCT platform covering four modules: Enroll (eConsent), Capture (eCRF / data collection), Manage (monitoring), and data pipeline/EHR imports.
- Self-service by design: 99% of customers build their own studies.
- Compliance stack: ICH GCP, FDA 21 CFR Part 11, ISO 27001, GDPR, HIPAA.
- Claimed operational benefits vs. traditional trials: 60% shorter time to first patient in, 30% less time on data cleaning, 70% time saved with EHR imports.
- Flagship reference: powering WHO SOLIDARITY Trial (COVID-19 therapeutics + vaccine) - ~1.5m data points, 3,000 investigators, 15K+ patients, 30 countries.
Market
- Global DCT Market: $2.5Bn → $10Bn by 2026 (source cited as Accenture / Grand View Research).
- Virtual component usage in trials projected to increase 3x in next 3 years from 2021.
- Broader context stat: clinical trial automation achieved only 8% vs. 42% potential.
Revenue model
- Self-service SaaS platform - customers pay to access and run studies; no pricing tiers, seat counts, or ACV figures disclosed in the deck.
- Product modules (eConsent, data capture, monitoring, EHR integration) suggest either modular per-module pricing or study-based licensing.
- No services/professional services revenue mentioned; "99% build their own (self-service)" implies minimal services attach.
- Channels: direct (self-service signup) + enterprise (pharma/biotech relationships implied by top-10 pharma audit references and WHO partnership).
Traction & metrics
- Studies supported: 7,500+
- Countries with deployments: 90+
- Researchers on platform: 75,000
- Enrolled patients: 2,600,000
- Data points captured: 250,000,000+
- Team size: 100+
- Total funding to date: $60m
Competition / moat
- Moat signals (implied, not stated explicitly): regulatory compliance stack (FDA/ICH/GDPR/HIPAA), global infrastructure (4-region server footprint), depth of data repository (250m+ data points, 2.6m patients), self-service model vs. services-heavy incumbents, and WHO Solidarity Trial as flagship credential.
- Differentiation stated: only "scalable, unified platform" to design trials, capture data, and monitor progress.
Team & funding ask / use of funds
- Founder: Derk Arts, MD, PhD.
- Team: 100+ as of July 2021.
- Investors: F-Prime Capital, Eight Roads, Two Sigma Ventures, inkef capital, WR Hambrecht+Co.
Recommended financial model
- Archetype + why: B2B SaaS ARR model. Revenue is recurring platform subscription (self-service, study-based or seat/module-based); no evidence of transaction or usage revenue. Model should track new studies started (volume driver) × average contract value (ACV), expanding into ARR waterfall (new, expansion, churn).
- Forecast horizon & granularity: 5 years (2021–2026), annual, with monthly detail for Year 1–2. Aligns with the 2026 DCT market sizing endpoint cited in the deck.
- Key drivers & assumptions:
| Driver | Value / Source |
|---|---|
| Starting study count (active ARR base) | 7,500 studies; assume a subset are active paying customers - 15–25% paying conversion at SaaS entry price |
| ACV per study / customer | $10k–$30k/study-year, typical mid-market clinical SaaS; no deck data |
| New study growth rate (YoY) | 40–60% given Series B stage and DCT market 4× growth to 2026 |
| Gross margin | 70–80%, consistent with B2B SaaS at scale; hosting costs across 4 regions compress slightly below pure-software peers |
| Net Revenue Retention (NRR) | 110–120%; study expansions and multi-module upsell are the primary lever |
| Annual churn rate | 8–12% logo churn; clinical trials are multi-year, reducing churn |
| Sales & marketing as % of revenue | 35–45% early post-Series-B, declining to 25–30% by Year 5 |
| R&D as % of revenue | 20–25%; platform roadmap (AI/ML, EHR integration) requires continued investment |
| G&A as % of revenue | 10–15%, scaling down as revenue grows |
| Team headcount growth | ~100 at Series B; model 30–40% headcount growth Year 1–2 |
| DCT market size by 2026 | $10Bn |
| Castor implied SOM by 2026 | 0.5–1.5% of $10Bn TAM = $50m–$150m ARR (calibrate scenario endpoints) |
- Scenarios (Base / Bull / Bear - which variables flex):
- Base: 50% study volume growth YoY, ACV $15k, NRR 115%, churn 10%.
- Bull: 70% study growth, ACV $20k (enterprise tilt), NRR 125%, churn 7%; accelerated by post-COVID DCT tailwind and WHO brand leverage.
- Bear: 30% growth, ACV $12k (commoditization pressure), NRR 105%, churn 15%; slower pharma adoption of fully decentralized trials.
- Required sheets / outputs:
- Assumptions dashboard (all drivers in one place, editable)
- Revenue build - study volume × ACV → ARR waterfall (new, expansion, churn, net new ARR)
- P&L - ARR to EBITDA by year
- Headcount plan - functional hiring tied to revenue milestones
- Cash & runway - uses of Series B proceeds; burn rate vs. ARR breakeven
- Market penetration bridge - Castor ARR vs. $10Bn DCT market (SOM chart)
- Scenario toggle - Base/Bull/Bear outputs on one summary page
Frequently asked
Is the Castor financial model free?+
Yes. The Castor model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Castor's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us

Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Other Biotech/Pharma Startup Financial Models
Browse another startup in the same category.
Ada Health
AI-powered symptom assessment app and clinical decision-support platform for consumers and healthcare partners.
Affini-T
Engineered T cell therapies targeting oncogenic driver mutations (KRAS, p53) in hard-to-treat solid tumors
Alto Pharmacy
Alto Pharmacy is a tech-enabled, same-day prescription delivery pharmacy disrupting the $450B US pharmacy market via a direct-to-patient courier model and provider-facing software platform.
Aphea.Bio
Aphea.Bio is a Belgian ag-biotech company developing and commercialising microbial biologicals (biostimulants, biofungicides, bioherbicides, bioinsecticides) for row crops, targeting yield improvement and reduced synthetic input use.
Aurion Biotech
Cell therapy company developing an injectable corneal endothelial cell treatment to restore vision in patients with corneal endothelial disease.
Beckley Psytech
Clinical-stage psychedelic drug development platform advancing a pipeline of psychedelic compounds (psilocybin, 5-MeO-DMT, NCEs) as licensed pharmaceutical medicines for neuropsychiatric disorders.
BrightInsight
Regulated digital health platform-as-a-service for biopharma and medtech companies to build, launch, and maintain compliant connected-drug and medical-device software products.
Carrum Health
Value-based care marketplace connecting self-insured employers to top-tier surgical and oncology Centers of Excellence (COEs) via all-inclusive bundled payments.


