COCollateralEdge Financial Model
Fintech Startup Financials (Free Excel Download)
Fintech platform enabling regional/community banks to cover up to 20% of marginal C&I loan risk via a proprietary collateral-based contract, letting banks say YES to borrowers they would otherwise turn away.

professionals from Deloitte
About this model
CollateralEdge helps regional and community banks take on marginal commercial-and-industrial loans through a proprietary collateral-based risk-coverage contract. The product is intended to let banks approve viable borrowers they might otherwise decline.
The company sells through bank partnerships and may pair its operating platform with an affiliated junior-capital pool. That structure makes it important to distinguish fee income from any investment or risk-bearing returns generated alongside the coverage product.
The model should forecast bank partners, covered loans per bank, average loan size, and fee yield on covered volume. If capital is deployed, add a distinct schedule for commitments, yields, realised losses, recoveries, and capital availability; it should not be blended into the asset-light platform margin.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About CollateralEdge
How to build a detailed financial model for CollateralEdge
A complete walkthrough of the business, drivers, and assumptions behind the downloadable CollateralEdge model - distilled from its pitch deck and publicly available information.
Product & value proposition
- CollateralEdge inserts itself between a regional/community bank and a marginal C&I borrower.
- The bank remains sole lender. CollateralEdge provides collateral-backed coverage on up to 20% of the loan amount, reducing the bank's effective credit risk on that slice.
- Delivered via a cloud-based "Pricing Portal" that integrates into the bank's existing underwriting workflow - no new IT integration required, one master agreement governs all deals.
- Target loan size: nonsyndicated term loans $5M–$50M.
- Only covers C&I amortizing term loans - no revolvers, no real estate, no syndicated.
- CollateralEdge earns a fee/spread on each covered transaction; the bank captures higher loan economics (increased spread) with lower risk rating and reserve requirements.
Market
- US C&I loan market: $2.6 trillion
- Addressable bank universe: 650 US banks with >$1B in assets
- Target customer: banks with ~$1B–$50B in assets (community and regional)
- Loan size per deal: $5M–$50M nonsyndicated term loans
- Average C&I market loss rate cited: ~1.0%
- Q3 2020 fintech VC investment: $8.9 billion (cited as market tailwind)
Revenue model
- Primary revenue: fee income per covered transaction. Exact fee structure (basis points on loan, flat fee, or spread-sharing) not stated in deck.
- Channel: direct bank partnerships - B2B enterprise sales to regional/community bank loan officers and credit departments.
- Ancillary: "affiliated junior capital pool" mentioned as part of end-to-end solution, implying CollateralEdge may also manage or co-invest in a capital vehicle that funds the risk coverage - this would generate investment income or management fees in addition to platform fees.
- No pricing schedule, no fee table, no disclosed rate card in deck.
Competition / moat
- Competitive framing: three existing options for banks on marginal credit (restrict credit, sub-debt/mezz, non-bank lender) - all presented as inferior.
- CollateralEdge positions as the only bank-centric solution that keeps the bank as sole lender, avoids intercreditor conflicts, and does not require the bank to lose the customer relationship.
- Moat claims: proprietary pricing algorithm with ML/AI, first-mover in the category ("completely new way of addressing debt capital delivery"), standardized contract format enabling scalability.
- No named competitors cited in deck.
Team & funding ask / use of funds
- Joel Radt: ~25 years finance; investment banker (Credit Suisse), investor (Grotech Capital), CFO of United Orthopedic Group (15 acquisitions, 3 refinancings over 6 years to exit).
- Joe Beard: investment banker / senior leader; ~$10B in M&A/equity/debt advisory; Partner at Perot Jain (portfolio of 40+ companies); Founder of Venture Dallas; UMB Bank North Texas Advisory Board.
- Combined ~40+ years finance expertise.
Recommended financial model
- Archetype + why: Fee-per-deal / transaction-volume revenue model with a capital deployment overlay. Two interlinked P&Ls:
- Platform P&L - SaaS-lite fee income from bank partners (coverage fee in bps on each loan covered × number of deals per bank × number of bank partners). This is the primary operating business.
- Capital pool P&L (optional second tab) - If CollateralEdge co-invests via the "affiliated junior capital pool," model the capital deployed, yield earned, and loss reserve against the ~1% C&I average loss rate. This is not a classic 3-statement model but resembles a specialty finance / credit fund P&L.
Closest archetype: B2B fintech transaction-fee model (similar to marketplace or payments) layered with a specialty finance / credit loss model for the capital vehicle.
- Forecast horizon & granularity:
- 5 years (Year 1–5); monthly in Year 1, quarterly in Years 2–3, annual in Years 4–5.
- Year 1–2 are relationship-building / onboarding; volume ramps from Year 2 onward.
- Key drivers & assumptions:
| Driver | Value / source |
|---|---|
| Bank partners onboarded (Year 1 / Y2 / Y3 / Y4 / Y5) | 2 / 6 / 15 / 30 / 50 - typical B2B fintech enterprise ramp |
| Deals per bank per year (average) | 5 → 15 ramp - early banks experiment, then expand |
| Average loan size covered | $15M (midpoint of $5M–$50M range) |
| CollateralEdge coverage % per loan | max 20% per policy → $3M average exposure per deal |
| Platform fee (bps on covered amount) | 150–250 bps p.a. on covered slice - needs verification from pricing deck |
| C&I average loss rate | ~1.0% |
| Loss reserve / credit loss expense | 1.0–1.5% of covered exposure annually |
| Capital deployed in junior capital pool | not modelled in base case; toggle as optional scenario |
| Headcount: sales / tech / ops | lean team; 2 founders + 2 sales hires (Y1) → ~10 FTE by Y3 |
| Tech opex (cloud, data, engineering) | $500K–$1M/year; offshore engineering model |
| CAC (bank partner acquisition cost) | $50K–$100K per bank (enterprise sales cycle, senior banker relationships) |
- Scenarios (Base / Bull / Bear - which variables flex):
- Base: 2 bank partners in Y1, 5 deals/bank, 150 bps fee, 1.0% loss rate.
- Bull: Faster bank onboarding (3× base), higher deal volume per bank, 200 bps fee, no credit losses above reserve.
- Bear: Slow bank adoption (1 partner Y1, 3 by Y3), low deal volume, 100 bps fee, 1.5% loss rate materializes.
- Flex variables: bank onboarding pace, deals/bank/year, fee rate (bps), credit loss rate.
- Required sheets / outputs:
- Assumptions - all inputs/drivers clearly flagged or, with toggle for capital pool scenario.
- Bank Partnership Ramp - cohort table: partners onboarded by year, deals per cohort, loan volume.
- Revenue Build - covered exposure × fee bps = gross fee income; less credit loss provision = net revenue.
- P&L - revenue less opex (headcount, tech, sales, G&A) → EBITDA → net income.
- Balance Sheet (simplified) - only if capital pool is included; otherwise a stub.
- Cash Flow / Runway - operating cash burn to break-even; key question for seed raise.
- Scenario toggle - Base / Bull / Bear switcher.
- Dashboard - KPI summary: active bank partners, total loans covered ($M), gross fee income, net loss ratio, cash runway.
Frequently asked
Is the CollateralEdge financial model free?+
Yes. The CollateralEdge model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from CollateralEdge's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other Fintech Startup Financial Models
Browse another startup in the same category.
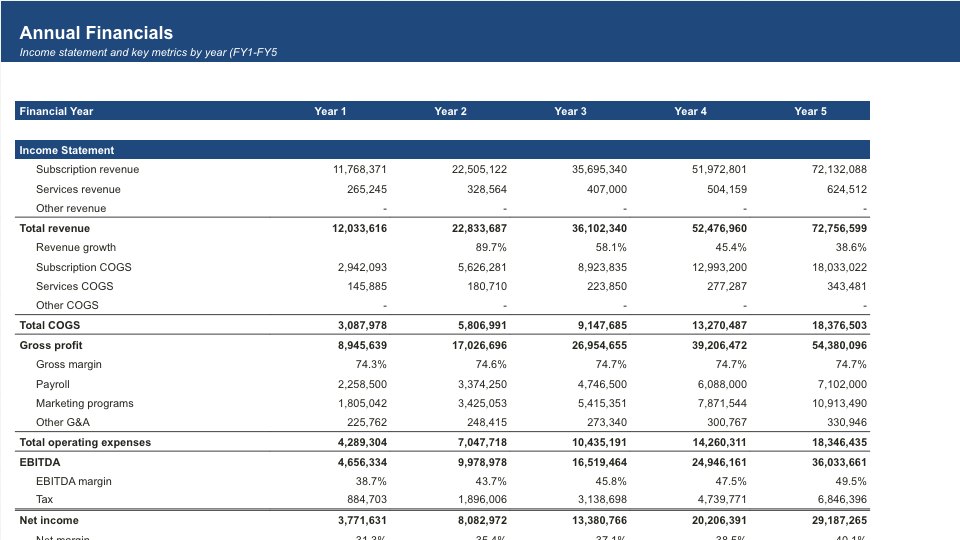
Acin
SaaS and data subscription network for operational risk management at Tier 1 financial institutions
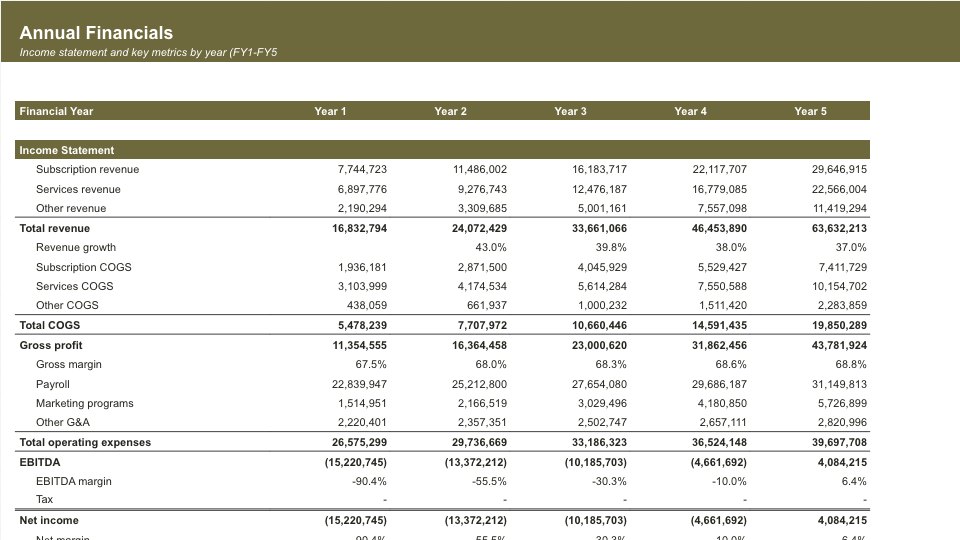
Ageras Group
B2B SME ecosystem - marketplace connecting SMEs with accountants + cloud accounting/payroll software + embedded financial services (lending, factoring, banking)
Airbase
Unified non-payroll spend management platform (corporate cards, AP/bill pay, expense reimbursement, approval workflows) for mid-market companies.
Altruist
Vertically integrated all-in-one platform for registered investment advisors (RIAs) - combining custodial, portfolio management, practice management, and client acquisition tools.
Amenitiz
All-in-one hotel management SaaS platform ("Shopify for hotels") for independent hoteliers - PMS, booking engine, channel manager, website builder, payments, and AI-driven revenue management.
Anrok
SaaS sales tax compliance platform - nexus monitoring, calculation, registration, filing, and remittance - built specifically for SaaS companies.
Arrival
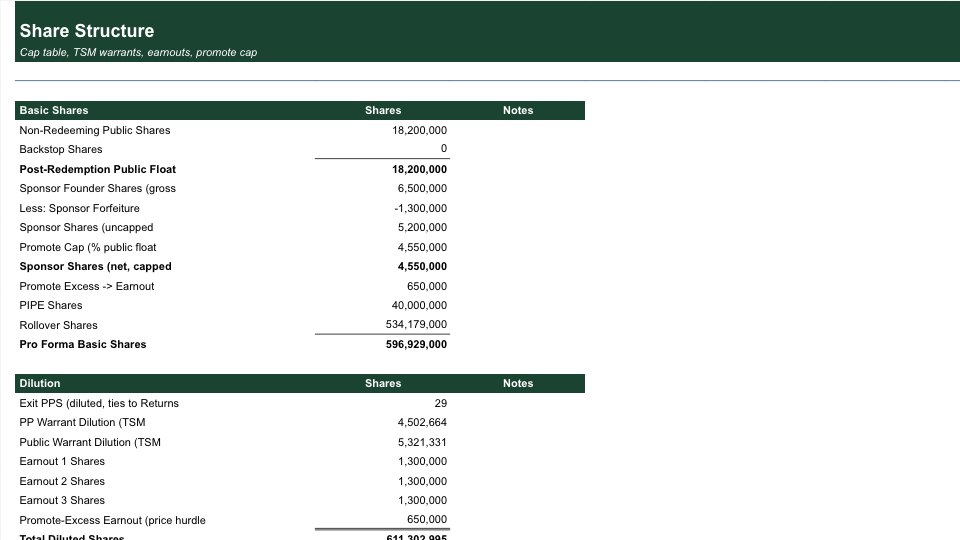
Arrival is an EV manufacturer of commercial vans and buses using proprietary Microfactories and vertically integrated components, going public via SPAC merger with CIIG Merger Corp.
AtoB
AtoB is building financial infrastructure for commercial fleets, starting with a no-fee Visa fleet card for fuel and expanding into payroll, BNPL, and international.