 Fintern Financial Model
Fintech Startup Financials (Free Excel Download)
Open Banking-powered consumer credit lender targeting near-prime UK borrowers, with a B2B lending-as-a-service layer planned for international expansion.

professionals from Deloitte
About this model
Fintern is an open-banking-powered credit provider for near-prime UK consumers, with a planned lending-as-a-service offering for partner institutions. Its consumer product originates unsecured personal loans using data-led underwriting rather than traditional credit processes alone.
The company combines a balance-sheet lending engine with a potential capital-light technology business. That dual structure offers exposure to interest income and credit risk on one side, and recurring software or platform revenue on the other.
The model should separately forecast consumer loan originations, average balances, APR, funding cost, defaults, and collections to derive net interest margin. The LaaS segment needs partner count, contracted ARR, implementation timing, and retention assumptions, then both segments roll into a consolidated P&L.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Fintern
fintern.ai
How to build a detailed financial model for Fintern
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Fintern model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Unsecured personal loans £1,000–£7,500
- Target: near-prime consumers (bureau default rate 5–19%) who are mis-classified by traditional credit scoring
- Fintern achieves 4–5% annualised default rate and 3–4% annualised loss rate on this cohort
- Uses Open Banking transaction data + alternative data + proprietary analytics to sub-segment near-prime risk bands; identifies sub-segments with 2–11% default rate within bands the market prices at ~10%
- Fully automated E2E lending platform; 66% of loan reviews fully automated as at Sep 2021
- Headline APR 18.8% as at May 2021, competitive with mainstream lenders (Barclays 20.9%, HSBC 21.9%) and vastly cheaper than specialist lenders (69.9–1270.0%)
- B2B layer: provide credit decisioning technology to third-party lenders globally on a fee/subscription/AUM model (capital-light)
Market
- Addressable market: 10m consumers in the UK
- Near-prime segment: ~30% of UK consumer credit score distribution
- No explicit TAM/SAM/SOM in £ terms presented in deck
- Target loan book: £1bn UK consumer loan book
Revenue model
B2C - Net Interest Margin (NIM) lending:
- Originate and hold unsecured personal loans £1,000–£7,500 at 18.8% APR
- Revenue = interest income on balance sheet loans minus cost of funds minus credit losses
- Target PBT £40m p.a. at scale (balance sheet £550m by Feb 2026)
B2B - Lending Technology as a Service (LaaS):
- Provide credit technology to partner lenders
- Pricing models: fee, subscription, and/or AUM-based
- Target: £32m ARR by 2025 from ~50 global clients
- Economic interest retained in loans owned by partners
- Described as capital-light
Distribution:
- Broker/introducer channel: 30 customer introducers onboarded; 25% of the time shown as the ONLY offer to customers via largest broker partner
Traction & metrics
All figures from unless noted:
- Regulatory lending permission: Feb 2021
- £40m debt and equity funding raised to date (as at 7 Feb 2021 - note: appears to be Feb 2022 deck, likely a slide date error)
- £32m seed funding; Series A £8m Dec 2021
- 21 team members
- Started lending March 2021
- 50% month-on-month origination growth to date
- Loan origination target £80m by Feb 2023
- Balance sheet target £550m by Feb 2026
- >50% reduction in credit losses vs market; currently achieving 75% reduction
- Actual bad rate (3MIA) tracking well below 50% of market PD curve through month 9 of cohort
- 66% loan reviews fully automated
- 90% in-month cure rate on late repayments
- Customer rating 4.5/5 (App Store 4.5, Trustpilot 4.3, Android 4.6)
- 30 customer introducers onboarded
- 25% of broker partner traffic shown as only offer
- B2B pipeline: 2 anchor clients targeted in 2022
Unit economics
- Annualised default rate on near-prime book: 4–5%
- Annualised loss rate: 3–4%
- APR: 18.8%
- Implied gross spread (APR minus loss rate): ~15–16% before cost of funds and opex
- Target: "below market CAC" stated as a goal but no CAC figure disclosed
- Automation benefit: low marginal cost per loan cited; 66% fully automated reviews
- Target PBT £40m p.a. at £1bn book (B2C); implies ~4% PBT/assets
- No explicit LTV, CAC £, or payback period in deck
Competition / moat
- Direct competitors shown: Zopa (15.4% APR), Clydesdale Bank (18.9% APR) in mainstream tier; Koyo, Lendable in digital
- Moat claims:
- Proprietary Open Banking + alternative data credit engine - achieves >50% loss reduction
- Higher approval rates for near-prime vs. incumbents
- Fully automated E2E platform (scalable, low cost-to-serve)
- Data network effect implied - more loans = better analytics
- Traditional banks have coarse credit scoring that cannot sub-segment near-prime efficiently
Team & funding ask / use of funds
Team (11 named):
- CEO/co-founder: Gerald Chappell (ex-McKinsey Partner, led global Digital Lending & Credit Analytics)
- COO/CFO/co-founder: Dr. Michelle He, CFA (ex-EY Director, ML PhD)
- CCO: Dr. Alan Cathcart (ex-MD HSBC & Bank of England, maths PhD Cambridge, 30+ years)
- CGO: Sam Power (ex-Wealthsimple, Tilt)
- CSO/CRO: Dr. Mark London (ex-EY Partner, UK quant team lead, maths/physics PhD)
- CTO: Bob Cui (ex-XiaoMi tech lead)
- CPO: Ni Li (ex-VP BAML)
- Board: Andrew Bloom (founder/ex-CEO Masthaven, ~£1bn challenger bank); Manson Yang (serial entrepreneur, Dolphin Browse ~200m users, WEF New Technology Pioneer 2020)
Funding to date:
- £32m seed
- £8m Series A (Dec 2021)
- £40m total debt and equity
Recommended financial model
Archetype + why: Dual-stream model: (1) Consumer lending NIM model (balance-sheet lender) + (2) SaaS/LaaS ARR model for the B2B technology licensing layer. The B2C stream is a classic balance-sheet lender model - revenue is interest income, key risk metric is loss rate, and the P&L is driven by loan book growth, NIM, and credit losses. The B2B stream is a capital-light SaaS/subscription revenue line. Both streams should be modelled separately with a consolidated P&L.
Forecast horizon & granularity:
- Monthly for Years 1–2 (lending ramp, cohort seasoning critical)
- Quarterly for Years 3–5 (to 2026 to match stated balance sheet target)
Key drivers & assumptions:
*B2C Lending:*
- Monthly origination volume (£): 50% MoM growth tapering
- Target origination by Feb 2023: £80m
- Target balance sheet by Feb 2026: £550m
- Average loan size:
- Average loan term:
- APR / yield: 18.8%
- Cost of funds (warehouse / securitisation):
- Annualised loss rate: 3–4%
- Opex / cost-to-serve per loan:
- Automation rate: 66%, targeting ~80%+
- Target PBT at scale: £40m p.a. on £1bn book
*B2B LaaS:*
- Anchor clients 2022: 2
- Global clients by 2025: 50
- Target ARR by 2025: £32m
- Implied ACV per client: £640k
- Revenue per client model:
- Gross margin on B2B:
*Credit loss model (cohort-based):*
- Default rate by vintage: 4–5% annualised
- Currently achieving 75% reduction vs market PD
- Cure rate: 90% in-month
- Net loss rate: 3–4% annualised
Scenarios (Base / Bull / Bear - which variables flex):
- Base: Origination ramps to £80m by Feb 2023, book reaches £550m by Feb 2026; loss rate 3–4%; B2B at 50 clients / £32m ARR by 2025
- Bull: Loss rates hold below 3% as data improves; CAC falls with brand; B2B client ramp accelerates; cost of funds improves via securitisation
- Bear: Origination growth stalls (macro tightening, recession, higher defaults); loss rate drifts to 6–7% if credit cycle turns; B2B pipeline fails to materialise; cost of funds rises materially (relevant in rising rate environment post-Feb 2022)
Required sheets / outputs:
- Assumptions - all drivers consolidated
- Loan Book Build - monthly cohort origination, balance, prepayment, charge-offs
- Income Statement - interest income, cost of funds, NIM, provision, opex, PBT (B2C)
- B2B Revenue Schedule - client ramp, ARR bridge, revenue recognition
- Consolidated P&L - B2C + B2B combined
- Balance Sheet - loan book as asset, warehouse/debt facility as liability, equity
- Cash Flow - operating CF, funding drawdowns/repayments, equity raises
- Credit Metrics - loss rate by cohort, arrears curve vs. market, provision coverage
- Scenario / Sensitivity - NIM vs. loss rate; origination volume vs. cost of funds
Frequently asked
Is the Fintern financial model free?+
Yes. The Fintern model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
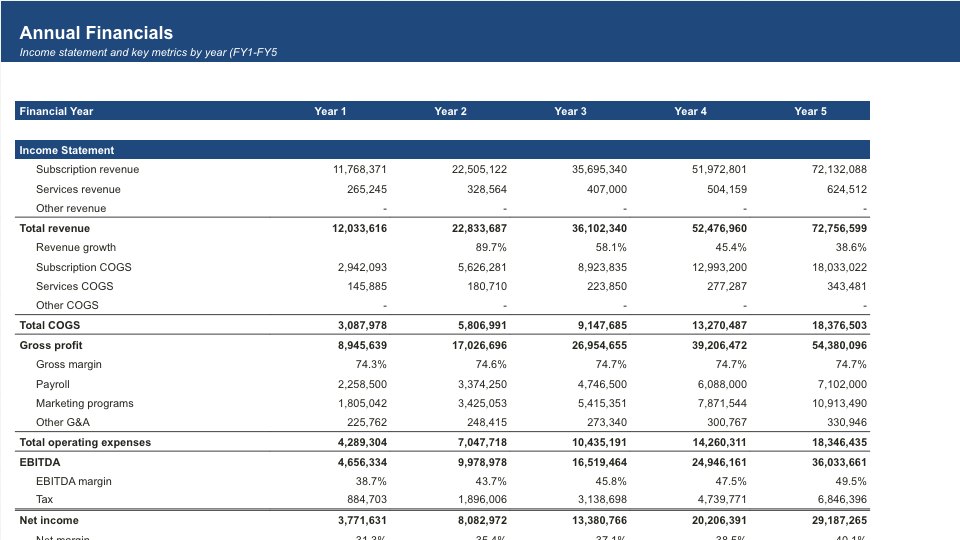
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Fintern's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other Fintech Startup Financial Models
Browse another startup in the same category.
Acin
SaaS and data subscription network for operational risk management at Tier 1 financial institutions
Ageras Group
B2B SME ecosystem - marketplace connecting SMEs with accountants + cloud accounting/payroll software + embedded financial services (lending, factoring, banking)
Airbase
Unified non-payroll spend management platform (corporate cards, AP/bill pay, expense reimbursement, approval workflows) for mid-market companies.
Altruist
Vertically integrated all-in-one platform for registered investment advisors (RIAs) - combining custodial, portfolio management, practice management, and client acquisition tools.
Amenitiz
All-in-one hotel management SaaS platform ("Shopify for hotels") for independent hoteliers - PMS, booking engine, channel manager, website builder, payments, and AI-driven revenue management.
Anrok
SaaS sales tax compliance platform - nexus monitoring, calculation, registration, filing, and remittance - built specifically for SaaS companies.
Arrival
Arrival is an EV manufacturer of commercial vans and buses using proprietary Microfactories and vertically integrated components, going public via SPAC merger with CIIG Merger Corp.
AtoB
AtoB is building financial infrastructure for commercial fleets, starting with a no-fee Visa fleet card for fuel and expanding into payroll, BNPL, and international.