Sable Financial Model
Fintech Startup Financials (Free Excel Download)
Digital banking platform giving new-to-America internationals instant access to checking accounts, debit cards, and secured credit cards via mobile.

professionals from Deloitte
About this model
Sable is a digital banking platform for internationals new to the US, offering checking accounts, debit cards, and secured credit cards through a mobile app. It helps customers establish a US financial footprint soon after arrival.
The product earns from debit and credit-card interchange and can benefit from the deposit collateral that supports secured credit limits. Direct-to-consumer distribution means app adoption, activation, and early engagement are central to customer lifetime value.
The model should forecast acquired users, funded accounts, active debit and credit cards, spend per card, and net interchange. Security deposits, credit balances, interest income, losses, and deposit float should be modelled separately, together with acquisition cost and cohort retention.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Sable
sablehomes.com
How to build a detailed financial model for Sable
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Sable model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Mobile-first onboarding using only a passport (no SSN required).
- Access to checking account, debit card, and secured credit card within 5 minutes.
- Two card SKUs: "Sable" (debit/checking) and "Sable ONE" (secured credit card), both Visa.
- Savings account also offered.
- Earns Sable Points rewards.
- Solves three friction points for internationals: offline-only checking without SSN, slow card delivery, and no credit history for credit card approval.
- Long-term vision: global borderless banking platform.
Market
- Initial U.S. market size: $5B
- 10M internationals move to the US every year
- 1.5M of those each year are prime or super prime credit quality
- 4.5M credit-worthy internationals have moved to the US over the past 3 years (cumulative addressable pool)
- 1.5M credit-worthy internationals arrive every year (annual new cohort)
Revenue model
- Interchange fees on debit and credit card spend
- Secured credit card requires a security deposit (collateral-funded credit limit); Sable earns net interest margin on the float
- Savings account - interest spread income possible.
- Distribution channel: Direct-to-consumer via mobile app (iOS/Android); app store + word-of-mouth implied.
Traction & metrics
- Product went live with credit cards and checking accounts in 3 months from founding/build
- Live with bank accounts, debit cards, and secured credit cards at time of deck
- App UI shows illustrative balances (not real traction data): Checking $500.00, Credit $820.00, Credit Limit $1,000.00, Secured Deposit $1,000.00.
Competition / moat
- Problem framed as: incumbents require SSN, in-branch visits, slow card delivery, and an existing U.S. credit history - all barriers for day-1 internationals.
- Moat implied by: passport-only onboarding, speed (5 minutes), and team's prior banking product experience.
Team & funding ask / use of funds
Team:
- Naveen Qureshi - Co-CEO & Chief Product Officer; consumer finance & tech product management; ex-Capital One, Amazon.
- Towers Wilen - Co-CEO & Chief Operating Officer; portfolio management & business development in credit cards; ex-American Express, Accenture.
- Joseph Finlayson - CTO; engineering / development lead in financial services; ex-McKinsey, Sberbank.
- Joyce Mehlman - Compliance Officer; former COO of Bancorp; 30 years in financial services (13 years fintech).
- Brent Reynolds - Credit Risk; 16-year Capital One veteran; advisor to Affirm.
- Team has collectively launched 14 banking products.
Recommended financial model
- Archetype + why: Consumer neobank / secured-credit card model - a hybrid of (a) DTC customer cohort build with monthly active user (MAU) tracking and (b) a credit book model. Revenue has two main legs: interchange (on spend volume) and net interest income (on secured deposit float). This is closer to a fintech lending/card model than pure SaaS.
- Forecast horizon & granularity: 3 years monthly (Year 1–2 monthly, Year 3 quarterly is acceptable). Early stage means the first 12 months are the most assumption-sensitive.
- Key drivers & assumptions:
- New customer additions per month
- Average security deposit per secured card customer
- Interchange rate on card spend
- Monthly card spend per active customer (monthly GMV per user)
- Net interest margin on secured deposit float
- Monthly churn rate
- CAC (customer acquisition cost)
- Gross margin on interchange
- Headcount and OpEx ramp
- $5B initial market
- 1.5M new credit-worthy internationals per year
- Scenarios (Base / Bull / Bear - which variables flex):
- Bear: slow customer ramp (500→1,500/mo by Y3), higher churn (5%/mo), CAC $80, thin interchange yield.
- Base: moderate ramp (500→5,000/mo), churn declining to 2%, CAC $45, standard interchange.
- Bull: fast word-of-mouth viral growth (500→10,000/mo), low churn (1%), CAC $25, cross-sell to savings/remittance adds revenue per user.
- Required sheets / outputs:
- Assumptions - all drivers with scenario toggle (Base/Bull/Bear)
- Cohort Build - monthly new customers, churn, cumulative active users
- Revenue - interchange (GMV × rate), net interest income (deposit float × NIM), any fee income
- Credit Book - secured deposit balances, credit utilization, credit loss reserve (even if simple at this stage)
- P&L (Income Statement) - gross profit, CAC spend, headcount OpEx, EBITDA
- Cash & Runway - cash burn, fundraising trigger point
- KPI Dashboard - MAU, GMV, revenue per user, CAC payback period, LTV/CAC
Frequently asked
Is the Sable financial model free?+
Yes. The Sable model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Sable's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other Fintech Startup Financial Models
Browse another startup in the same category.
Acin
SaaS and data subscription network for operational risk management at Tier 1 financial institutions
Ageras Group
B2B SME ecosystem - marketplace connecting SMEs with accountants + cloud accounting/payroll software + embedded financial services (lending, factoring, banking)
Airbase
Unified non-payroll spend management platform (corporate cards, AP/bill pay, expense reimbursement, approval workflows) for mid-market companies.
Altruist
Vertically integrated all-in-one platform for registered investment advisors (RIAs) - combining custodial, portfolio management, practice management, and client acquisition tools.
Amenitiz
All-in-one hotel management SaaS platform ("Shopify for hotels") for independent hoteliers - PMS, booking engine, channel manager, website builder, payments, and AI-driven revenue management.
Anrok
SaaS sales tax compliance platform - nexus monitoring, calculation, registration, filing, and remittance - built specifically for SaaS companies.
Arrival
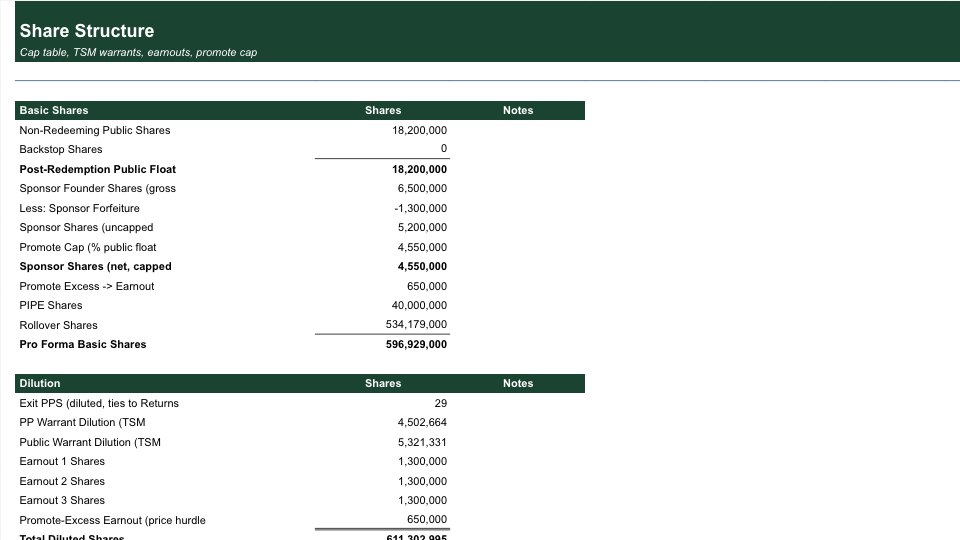
Arrival is an EV manufacturer of commercial vans and buses using proprietary Microfactories and vertically integrated components, going public via SPAC merger with CIIG Merger Corp.
AtoB
AtoB is building financial infrastructure for commercial fleets, starting with a no-fee Visa fleet card for fuel and expanding into payroll, BNPL, and international.