Zeta Financial Model
Fintech Startup Financials (Free Excel Download)
Cloud-native "Omni Stack" banking technology platform replacing legacy core and payment processing infrastructure for banks and fintechs.

professionals from Deloitte
About this model
Zeta is a cloud-native banking technology platform replacing legacy core and payment-processing infrastructure for banks and fintechs. Its Omni Stack includes products for traditional banks, fintechs, and enterprises with distinct deployment and volume characteristics.
The company is expected to earn platform licensing or SaaS fees alongside card-processing and transaction revenue. Its scale in issued cards means payment volume can become a material complement to contracted software revenue as customers expand.
The model should forecast clients by Tachyon, Fusion, and Electron segment; annual platform contract value; implementation timing; cards issued; active cards; and transaction volume. Keep licence ARR and volume revenue separate, with cloud, card-network, and implementation costs allocated to show segment profitability.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Zeta
zeta.tech
How to build a detailed financial model for Zeta
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Zeta model - distilled from its pitch deck and publicly available information.
Product & value proposition
Three product lines:
- Tachyon (for banks): Full-stack modern banking and payments suite - Tachyon Credit, Debit, Prepaid, Core, Savings, Loan Management, Payments Hub, Gateway, Merchant Management, FRM, ACS, IAM, CLM.
- Fusion (for fintechs): Embeddable banking-as-a-service - enables fintechs to embed banking products into their apps.
- Electron (for enterprises): Enterprise payments - employee benefits, T&E cards, rewards & recognition, P-cards, AP/AR.
Also offers retail products directly: Zeta Credit Card, Debit Card, Deposits, BNPL.
Value proposition: Single modern full-stack alternative to the fragmented legacy vendor landscape (Fiserv, FIS, TSYS, Oracle, Finastra etc.) - lower cost-to-income ratio, modern UX, speed/agility, 100% API coverage.
Market
- TAM framed as "$300Bn Annual IT Spend by Banks".
- Competitor revenue benchmarks as proxy for addressable market (CY20): Fiserv $14.9bn, FIS $12.6bn, Global Payments $7.4bn, Jack Henry $1.7bn.
- No SAM/SOM breakdown, no growth rate for the market cited.
Revenue model
Not explicitly stated in deck. Based on product structure, inferred revenue streams:
- Platform licensing / SaaS fees from banks for Tachyon stack - likely per-module or per-bank annual contract value (ACV). Rationale: B2B banking tech is universally sold on annual licenses.
- Transaction / interchange revenue from card issuance (10M cards issued) - per-transaction or monthly fee per active card. Rationale: card processing platforms typically earn basis points per transaction or flat per-card-per-month.
- Revenue share or SaaS fee from Fusion (fintech BaaS) and Electron (enterprise) segments. Rationale: consistent with BaaS and enterprise payments market norms.
- No pricing tiers, contract values, or ARPU figures shown in deck.
Traction & metrics
All figures from slide 3 (timeline) and slides 20–23 unless noted:
| Metric | Value | Slide |
|---|---|---|
| Valuation | $1.45B | 3 |
| Cards issued | 10 million | 20 |
| FI customers (banks) | 10+ | 22 |
| Fintech customers | 20+ | 23 |
| Corporate customers (2017) | 750+ | 3 |
| Employees | 750+ | 3 |
| Countries live | 8 | 21 |
| Sodexo implied valuation of Zeta (2018) | $300Mn | 3 |
| Network deals | Visa & Mastercard | 3 |
Named bank customers: HDFC Bank, Axis Bank, Kotak Mahindra Bank, IndusInd Bank, YES Bank, RBL Bank, SBM Bank, Sodexo. Named fintech customers (20+): BharatPe, Aditya Birla Group, Stashfin, FamPay, Junio, Mobikwik, and others.
No revenue figures, ARR, GMV, transaction volumes, or growth rates disclosed.
Competition / moat
Positioning matrix (slide 14, X-axis: Legacy→Modern; Y-axis: Discrete components→Full Stack):
- Zeta positioned: top-right (Full Stack + Modern) - sole occupant of that quadrant.
- Legacy full-stack: FIS, TSYS, Fiserv, Oracle, Finastra.
- Modern but discrete: Temenos, Mambu, 10x, Galileo, Marqeta, Backbase, Thought Machine, Infosys Finacle, 2C2P.
Claimed moat: Only vendor offering a unified modern full-stack (not point solutions), plus 100% API coverage and existing live bank deployments with top-14 global bank (HDFC).
Team & funding ask / use of funds
- Bhavin Turakhia (CEO & Co-founder): Serial entrepreneur - Directi ($160mn valuation), Radix ($450mn valuation), NOVA/Flock/Titan (collaboration tools).
- Ramki Gaddipati (CTO & Co-founder): Founder of Bridle; named Asia's best entrepreneur under 25; engineering leadership at Morgan Stanley.
- Implied round context: $1.45B valuation at time of deck; this appears to be a Series C or later growth round based on traction, but round details absent.
Recommended financial model
- Archetype + why: B2B SaaS / fintech infrastructure multi-segment model. Zeta has three distinct go-to-market segments (Tachyon/banks, Fusion/fintechs, Electron/enterprises) each with different contract sizes and volume characteristics. The primary model should be an ARR-based SaaS model with a card-volume overlay (interchange/per-card revenue). This is not a marketplace or DTC model - it is a platform licensing + transaction revenue business.
- Forecast horizon & granularity: 5-year annual model (2022–2026) with Year 1 broken into quarters. The company is already at scale ($1.45B valuation, 10+ banks) so monthly granularity isn't needed.
- Key drivers & assumptions:
*Tachyon (Banks segment)*
- Number of bank clients: 10; +3–5 new bank wins/year. Rationale: enterprise bank sales cycles are 12–24 months; 3–5/yr is consistent with a 750-person org targeting global expansion.
- ACV per bank: $2–5M/year. Rationale: top-tier core banking replacements (Temenos, Thought Machine comps) command $2–10M ACV; lower end used for conservatism.
- Net Revenue Retention: 110–120%. Rationale: banking tech is sticky; module expansion (add Tachyon Loans, FRM etc.) drives upsell.
*Fusion (Fintechs segment)*
- Number of fintech clients: 20+; +10–15 new/year. Rationale: shorter sales cycles vs. banks; large addressable pool.
- ACV per fintech: $100K–$500K. Rationale: fintechs are smaller, but some (BharatPe, Mobikwik) are sizeable.
- Plus variable card/transaction revenue: ~$0.50–$1.00 per active card/month. Rationale: BaaS market standard.
*Electron (Enterprises segment)*
- 750+ corp customers as of 2017 - likely Electron/prepaid/benefit card segment.
- ARPU $10–50K/year per enterprise. Rationale: employee benefits / T&E card programs are mid-market SaaS; Sodexo partnership suggests volume-based model.
*Cards / volume overlay*
- Active cards issued: 10M. 20–40% active rate; ~$0.50–$1.00/active card/month revenue. Rationale: interchange and processing fees industry norm.
*Headcount & costs*
- 750+ employees. ~60–65% of costs are personnel. Rationale: pure software/infra company; typical for B2B SaaS.
- R&D ~30%, S&M ~20%, G&A ~10% of revenue. Rationale: growth-stage fintech infra benchmarks.
- Gross margin 60–70% (software licensing), lower on transaction revenue (~40%). Rationale: banking platform peers (Temenos, Mambu).
- Scenarios (Base / Bull / Bear - which variables flex):
- Bear: Slower bank deal closure (1–2 new banks/yr), lower ACV, no US/UK market traction in forecast period.
- Base: 3–4 new banks/yr, $2–3M ACV, moderate card volume growth, fintech segment grows 10–15/yr.
- Bull: 5+ new banks/yr including US Tier-1 bank, $4–5M ACV, card volume surpasses 30M, Fusion scales rapidly.
- Flex variables: bank win rate, ACV, active card count, geographic expansion pace (US/UK).
- Required sheets / outputs:
- Assumptions - all drivers by segment, toggle for Base/Bull/Bear.
- Revenue Build - Tachyon (bank count × ACV), Fusion (fintech count × ACV + card volume), Electron (corp count × ARPU).
- P&L - Revenue, Gross Profit, OpEx by function (R&D, S&M, G&A), EBITDA.
- Headcount Plan - by function, linked to cost build.
- Cash Flow & Runway - given no disclosed funding; model burn and implied runway.
- KPI Dashboard - ARR, NRR, cards issued (cumulative + active), customers by segment, CAC payback (once data available).
Frequently asked
Is the Zeta financial model free?+
Yes. The Zeta model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
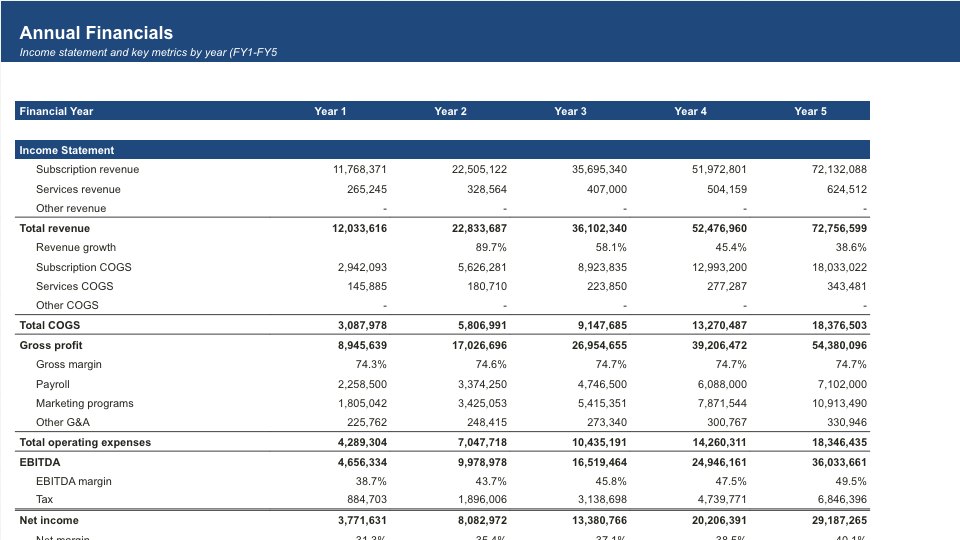
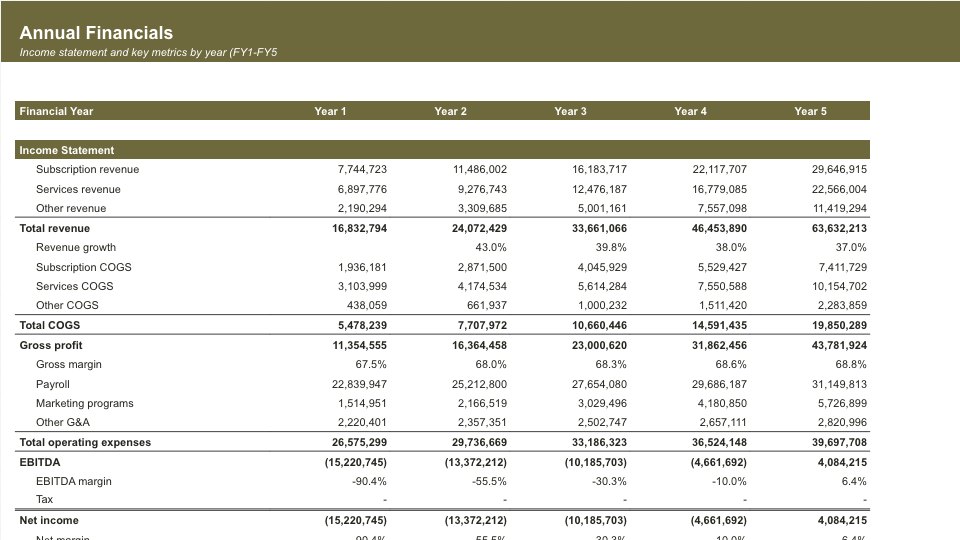
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Zeta's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Other Fintech Startup Financial Models
Browse another startup in the same category.
Acin
SaaS and data subscription network for operational risk management at Tier 1 financial institutions
Ageras Group
B2B SME ecosystem - marketplace connecting SMEs with accountants + cloud accounting/payroll software + embedded financial services (lending, factoring, banking)
Airbase
Unified non-payroll spend management platform (corporate cards, AP/bill pay, expense reimbursement, approval workflows) for mid-market companies.
Altruist
Vertically integrated all-in-one platform for registered investment advisors (RIAs) - combining custodial, portfolio management, practice management, and client acquisition tools.
Amenitiz
All-in-one hotel management SaaS platform ("Shopify for hotels") for independent hoteliers - PMS, booking engine, channel manager, website builder, payments, and AI-driven revenue management.
Anrok
SaaS sales tax compliance platform - nexus monitoring, calculation, registration, filing, and remittance - built specifically for SaaS companies.
Arrival
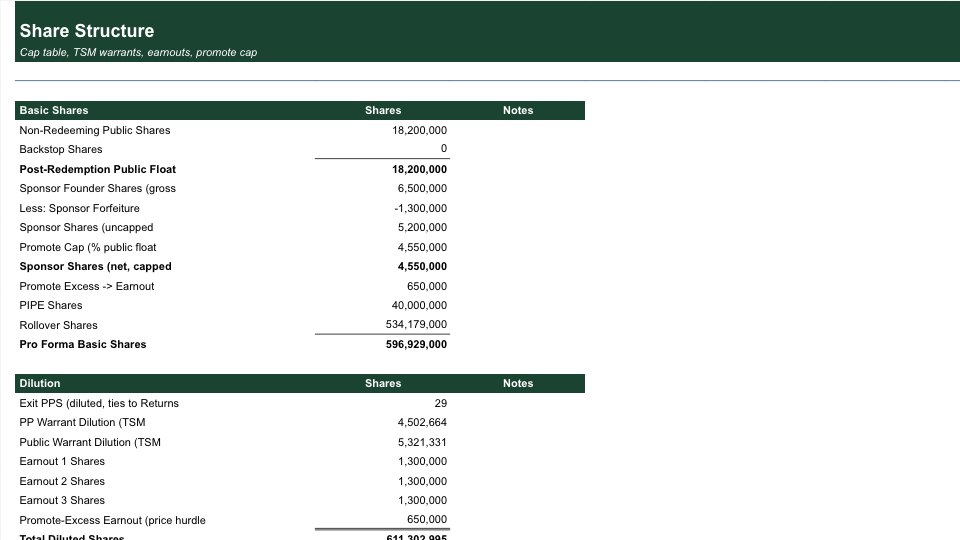
Arrival is an EV manufacturer of commercial vans and buses using proprietary Microfactories and vertically integrated components, going public via SPAC merger with CIIG Merger Corp.
AtoB
AtoB is building financial infrastructure for commercial fleets, starting with a no-fee Visa fleet card for fuel and expanding into payroll, BNPL, and international.