Captive Insurance Pro Forma
Insurance Excel Template (Free Download)
Turn premium volume, claims timing, reinsurance, and capital requirements into a projected captive insurer pro forma.

professionals from Deloitte
About this pro forma
This pro forma gives captive owners, risk managers, actuaries, boards, and lenders a projected view of underwriting and capital performance. Premiums, claims emergence, reserves, expenses, reinsurance structures, investment income, and capital adequacy flow into projected underwriting profit and cash.
Use the output to assess a new captive, retention strategy, or reinsurance programme. The underlying Excel engine makes combined-ratio improvement, claims timing, reserve needs, and funding requirements visible to decision-makers.
What every model includes
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
What's inside the Captive Insurance Pro Forma
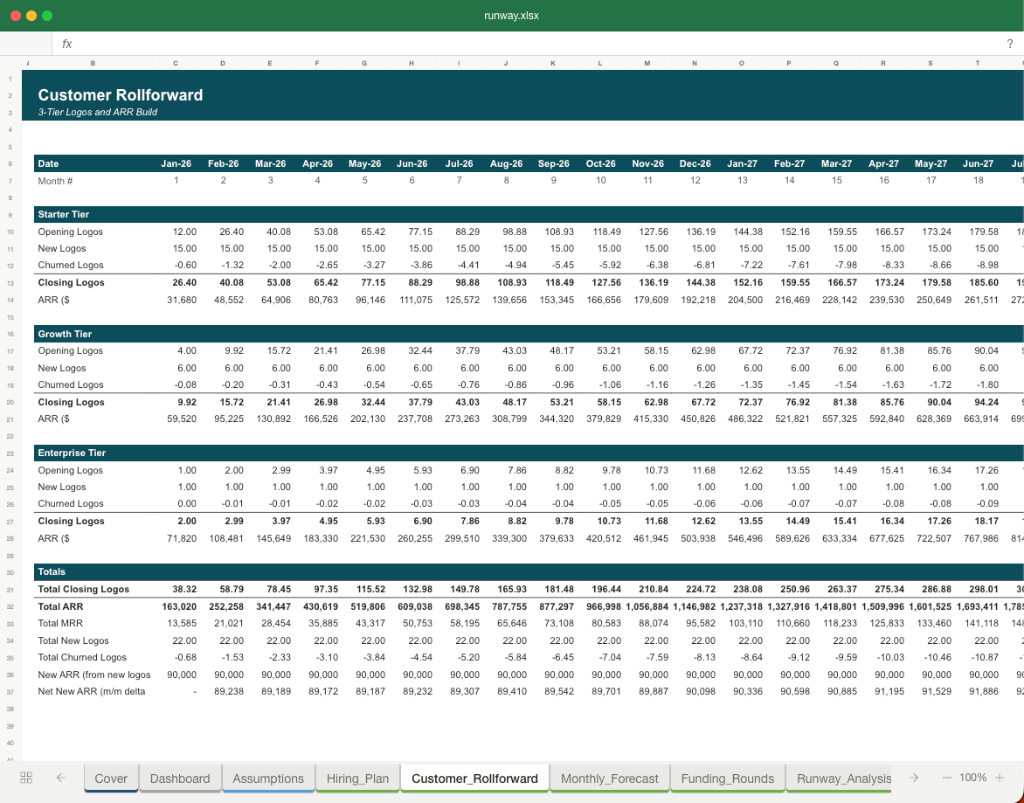
- Projected premium volume and underwriting revenue
- Claims timing, reserves, paid losses, and incurred losses
- Reinsurance programme, recoveries, and retained risk
- Underwriting expenses, combined ratio, and underwriting profit
- Capital adequacy, surplus, investment income, and cash flow
- Scenario outputs for risk, pricing, and reinsurance decisions
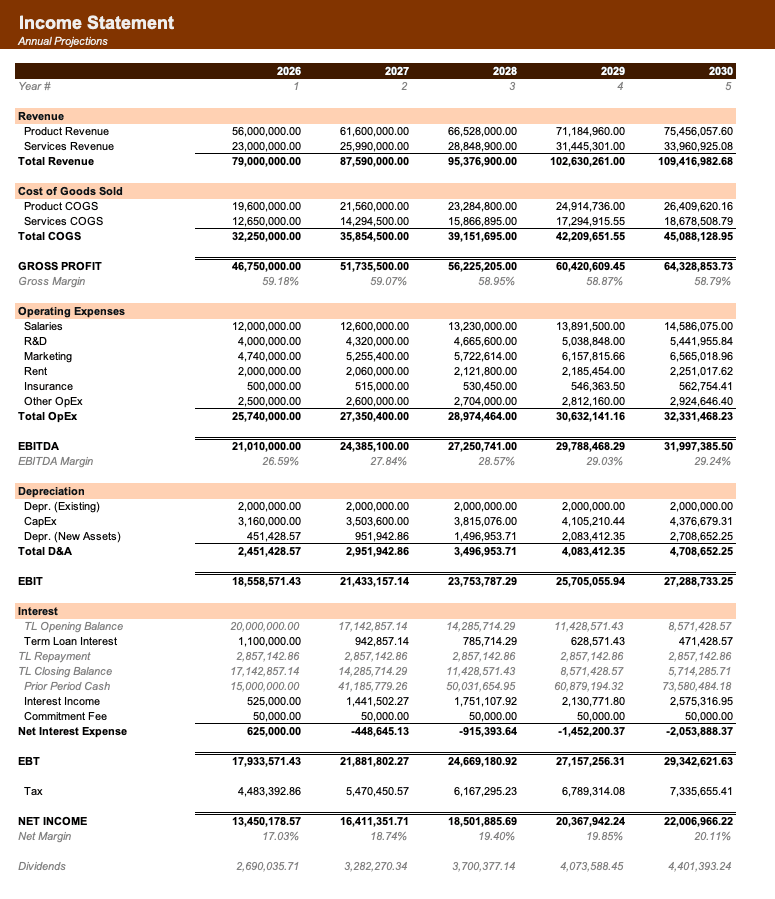
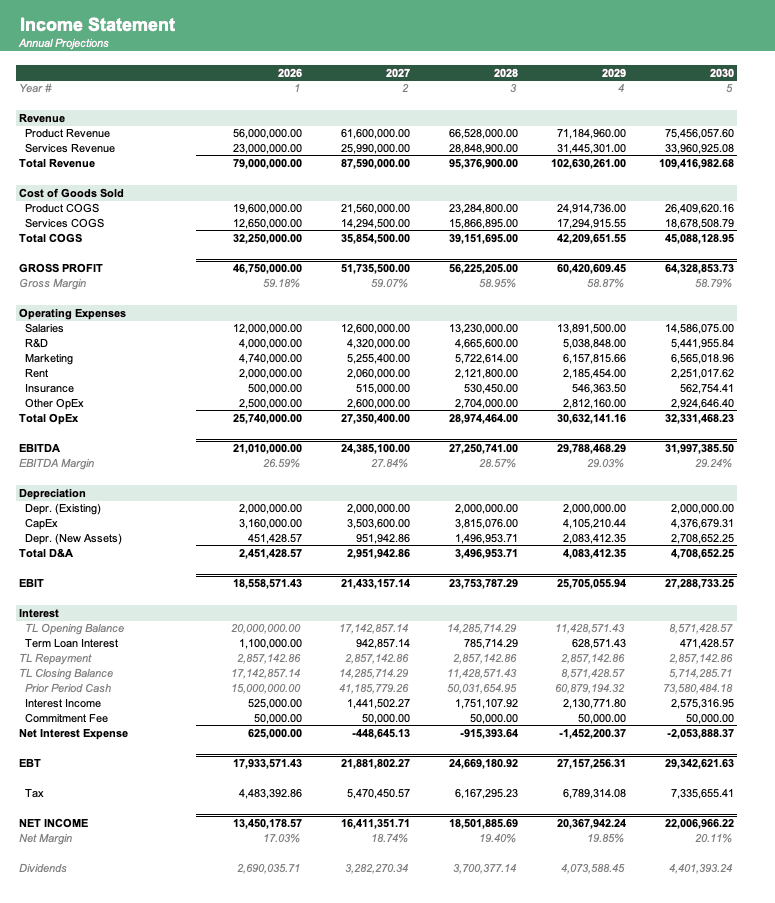
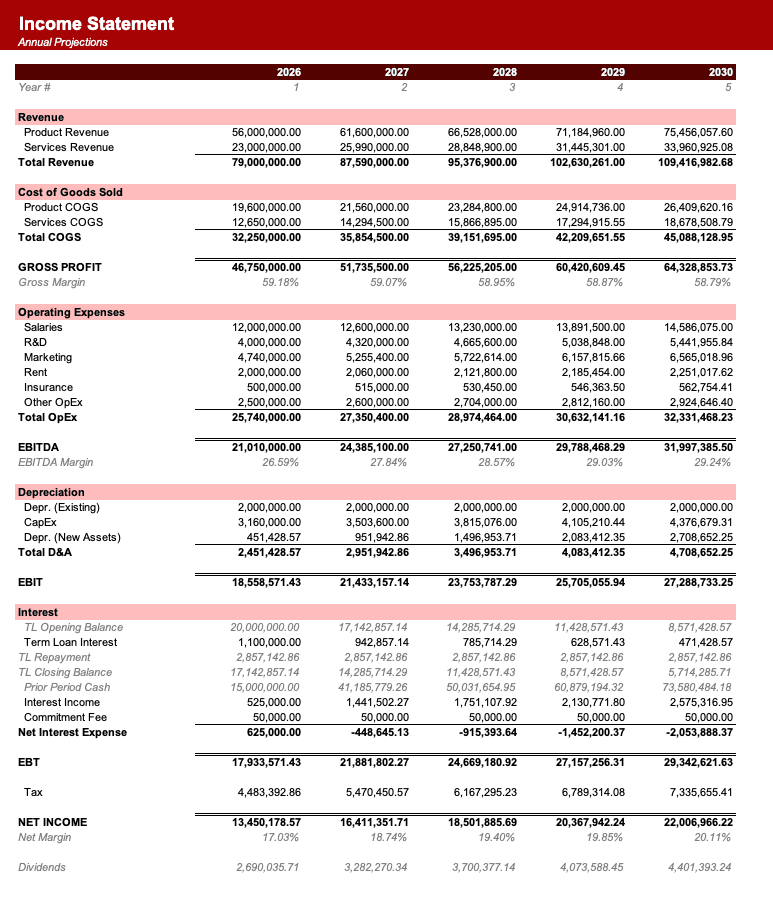
Formatted to IB standards
Named theme colors repaint the whole workbook in one click, on top of an investment-banking structure with clear input, output, and cross-sheet reference styling - brand-ready, institutional-grade, and fully auditable.
Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Frequently asked
Who uses this captive pro forma?+
Captive owners, risk managers, boards, actuaries, investors, and financing partners.
Does it model claims timing?+
Yes. Claims emergence, reserves, payments, and recoveries drive projected underwriting cash flow.
Can I test reinsurance structures?+
Yes. Reinsurance terms and recoveries can be flexed to compare retained risk and capital needs.
What is the main decision output?+
The model projects underwriting profit, combined ratio, surplus, capital adequacy, and cash requirements.
Have more financial modelling questions? Contact us
Related pro formas
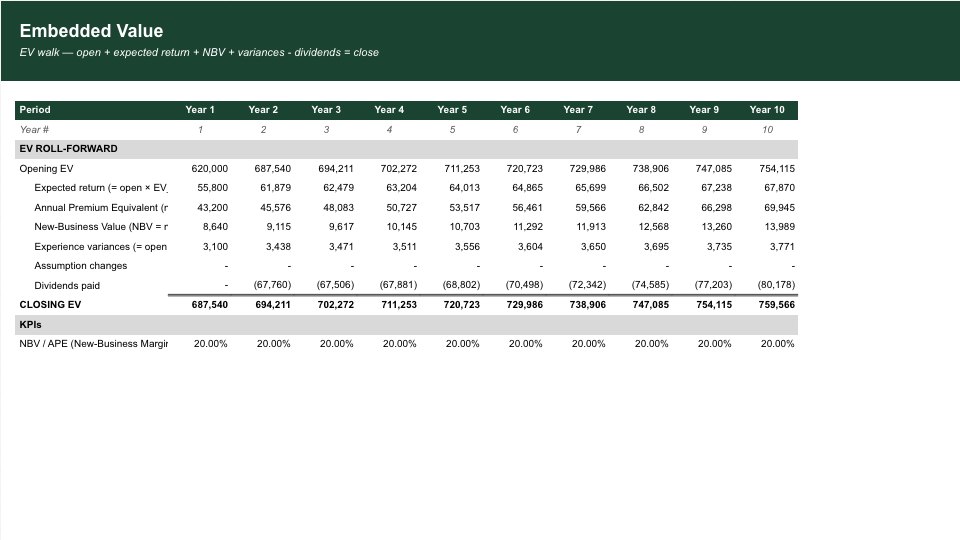
Life Insurance Pro Forma
Valuation model for life insurance products and in-force book value using mortality assumptions and surrender rates.
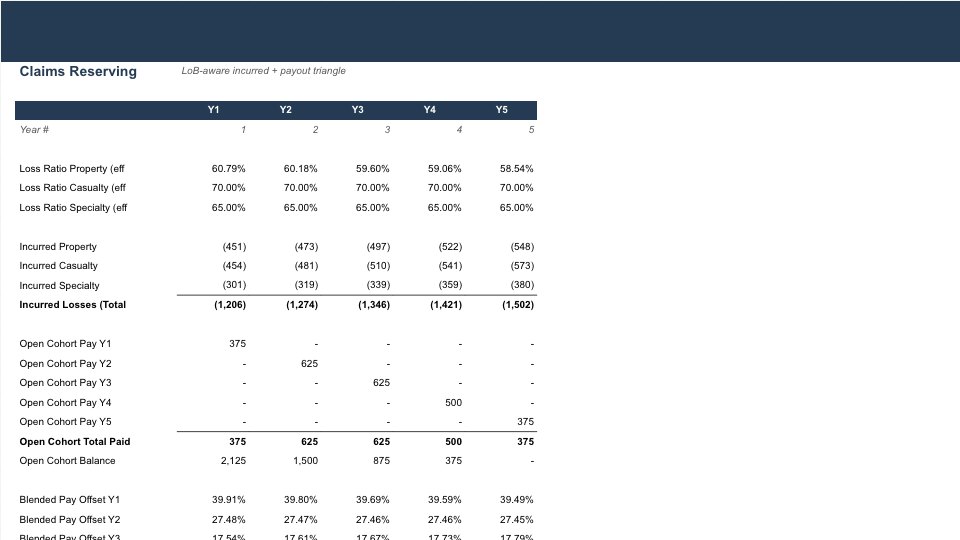
Reinsurance Pro Forma
Reinsurance premium income, claims reserves, underwriting margin, and ROE for reinsurance portfolios.
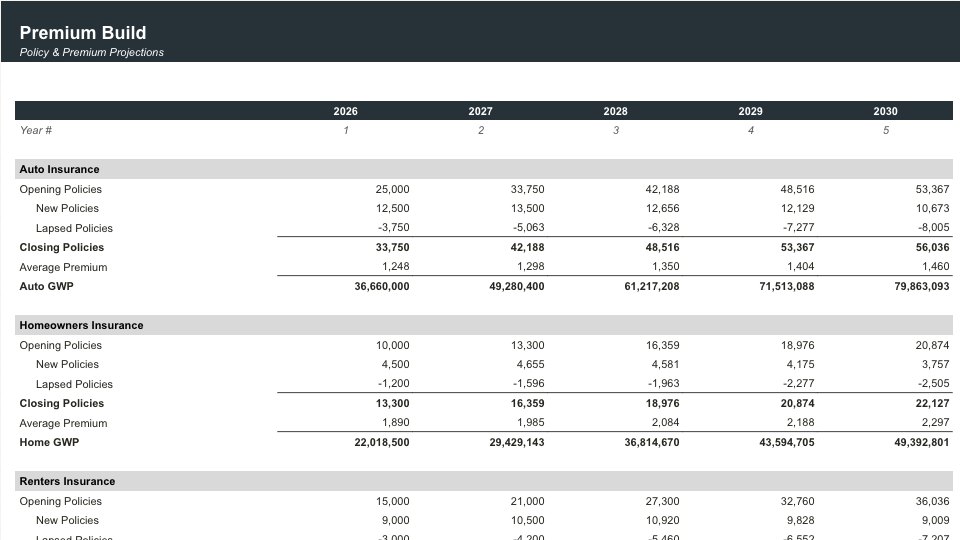
InsurTech Pro Forma
Operating model for insurance tech platforms including underwriting volumes, loss ratios, expense ratios, and insurance-linked returns.