 Relief Financial Model
Fintech Startup Financials (Free Excel Download)
Mobile app that guides Americans through debt settlement via AI-driven negotiation with creditors, charging a success fee.



professionals from Deloitte
Used by professionals from






About this model
Relief is a mobile app that helps Americans settle debt through AI-driven creditor negotiation. It positions the service as free to the consumer, earning a success fee only when a debt settlement is completed.
The documented economics are simple: the average settlement is $7,492 and the service earns 10%, or about $749 per resolved customer, paid by the creditor. The business therefore depends on enrolment quality and successful resolution, not subscription retention.
The model should forecast enrolled clients, creditor acceptance, settlement rate, average debt settled, and the 10% success fee. Customer acquisition cost, negotiation capacity, time from enrolment to settlement, and credit or compliance costs should be tracked to show cash conversion and unit economics.
A turnkey financial model
Live formulas, no hardcoded values
Outputs are driven by live formulas, so the workbook updates from its assumptions instead of relying on hardcoded results.
All assumptions in one tab
Inputs are clearly marked in the Assumptions tab and separated from calculations, making it clear what to change and what to leave intact.
Statements always balancing
For integrated-statement models, the balance sheet, cash flow, and supporting schedules tie through properly.
Distinct schedules for clarity
Debt, working capital, taxes, and cash flow can get messy quickly. We group calculations in clear schedules, not across disconnected tabs.
No hidden macros or external links
There are no unexplained external workbook links or macros to undermine auditability or portability.
Changes flow through the model
Update a key driver and see the impact carry through the forecast, financing, and return outputs. We never use hardcoded numbers in formulas.
About Relief
relief.tech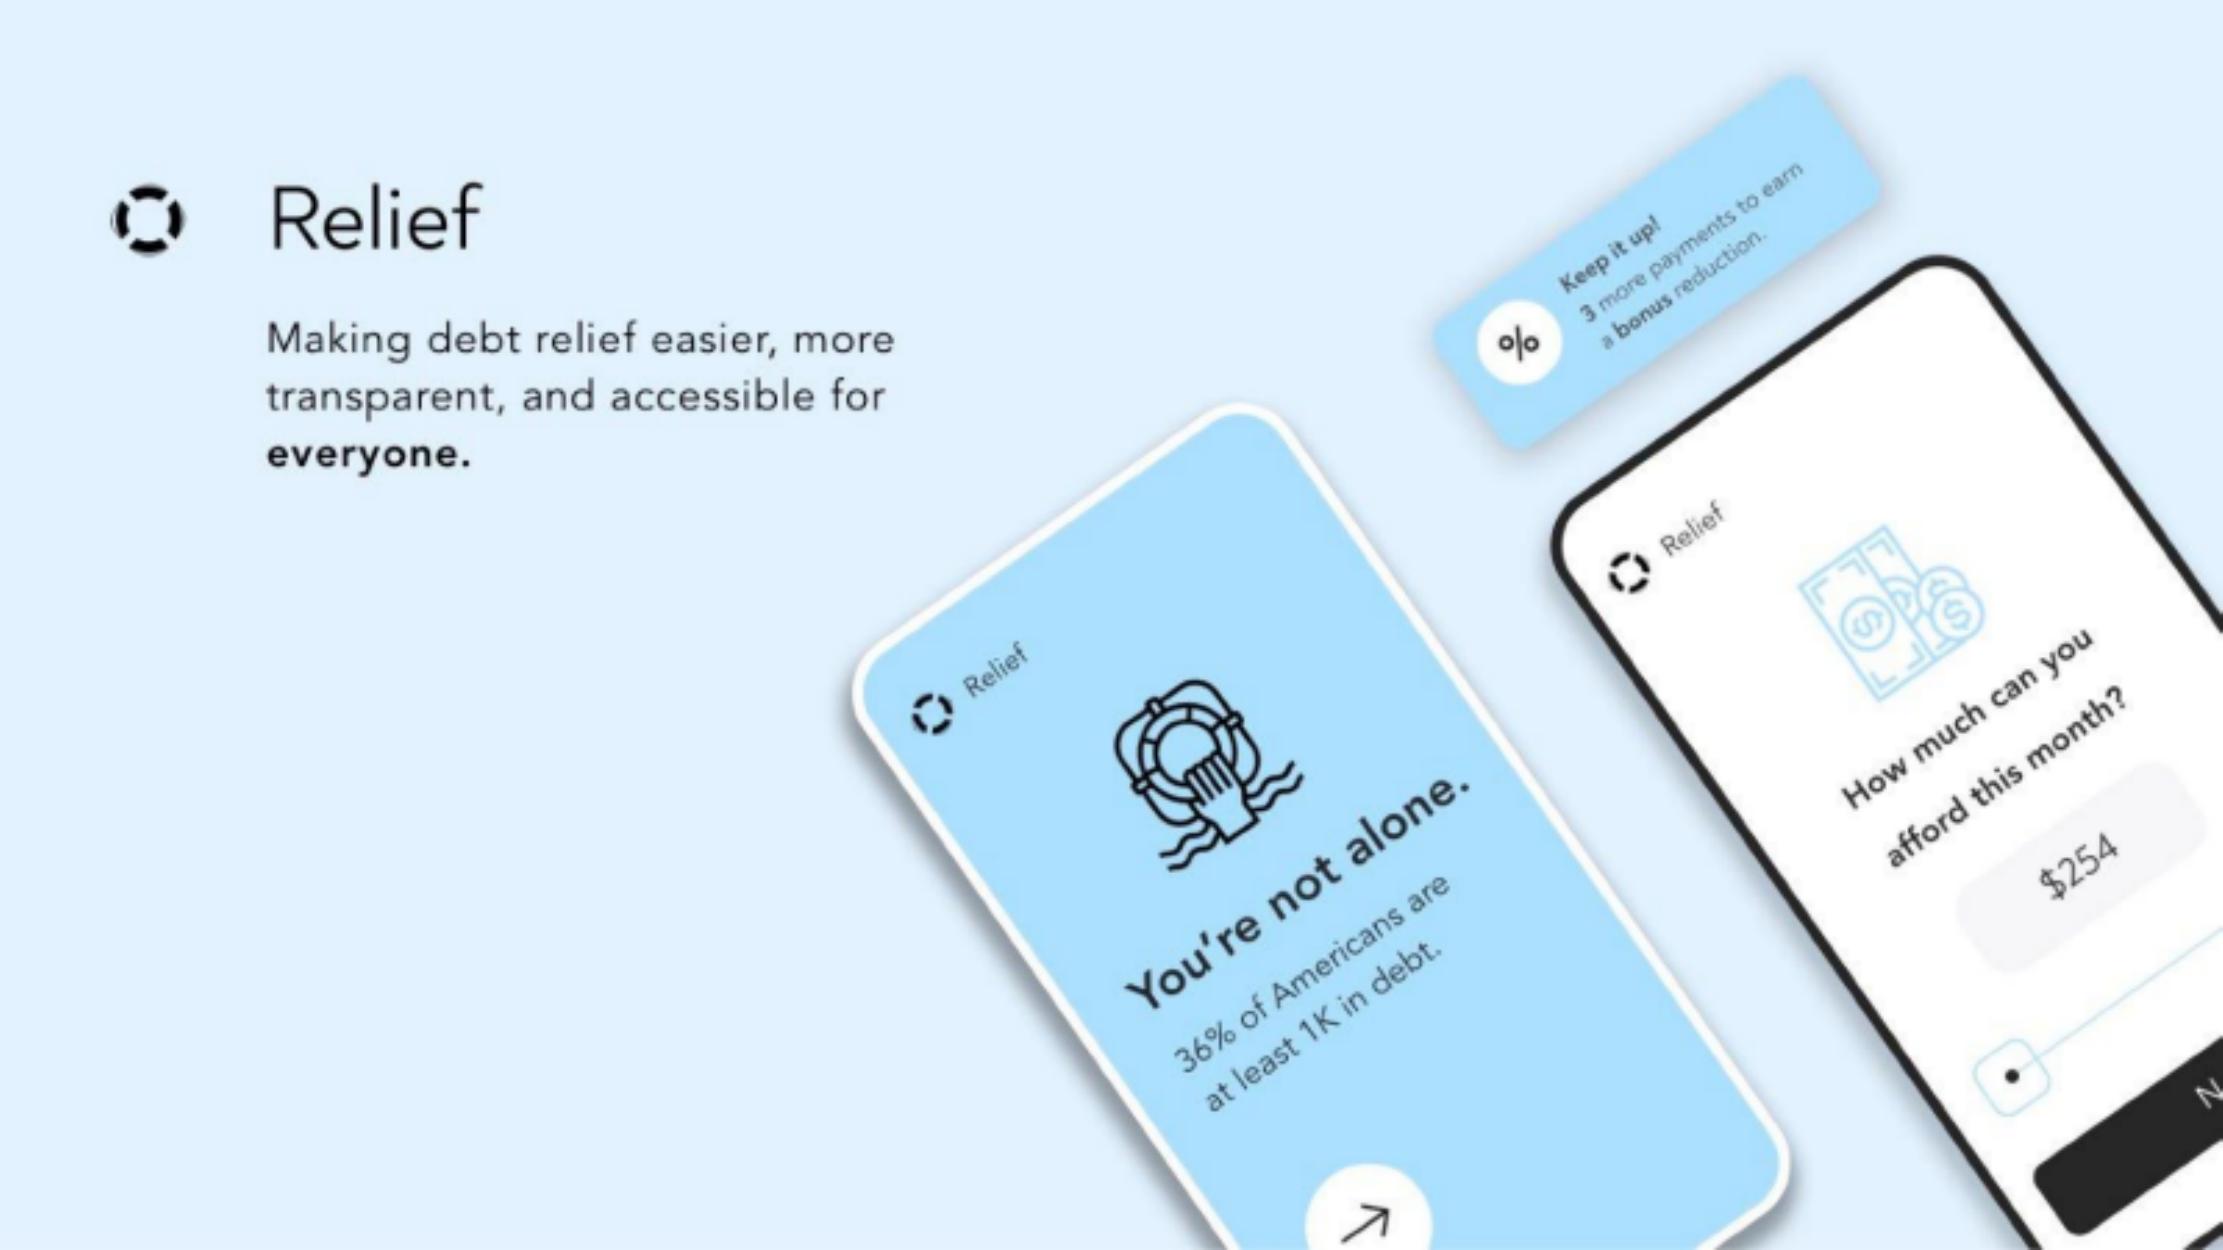
How to build a detailed financial model for Relief
A complete walkthrough of the business, drivers, and assumptions behind the downloadable Relief model - distilled from its pitch deck and publicly available information.
Product & value proposition
- Mobile app that assesses user finances and personal goals, then presents personalized debt-relief options (fast payoff vs. manageable payments).
- Relief negotiates with creditors on the user's behalf; shows negotiated offers transparently before the user commits.
- User pays into an escrow account while Relief negotiates; fee charged only on successful settlement.
- Educational content included; free materials and guidance throughout the process.
- Long-term vision: expand into credit score monitoring, debt consolidation, loan refinancing, and personal lending as a broader personal finance gateway.
Market
- TAM: $2.78 trillion - US consumer debt excl. mortgages, auto loans, HELOC (2019).
- SAM: $695 billion - US consumer debt expected to default or enter collections.
- SOM: $6.7 billion - amount currently enrolled in debt settlement programs.
- Context: 1 in 3 Americans have an account in collections; average personal debt $29,000 excl. mortgages (2019, Experian); projected to hit record highs in 2020.
Revenue model
- Single revenue line: success fee charged to creditor upon completed debt settlement.
- Average settlement amount per person: $7,492 (2019).
- Service fee rate: 10% of settlement amount.
- Average fee per resolved client: $749.
- Fee is paid by the creditor (debt holder), not the consumer - positions Relief as free to the end user.
- No subscription or monthly fee mentioned in deck.
Traction & metrics
- No live revenue or active user numbers disclosed.
- Beta user reach cited as pipeline, not current customers:
- 2.5M Bloom Acquisition debt holders (creditor partner).
- 2.7M combined mailing list (Alley + Colors Worldwide).
- App is pre-launch / pilot stage based on context (raising seed round to reach profitability in 12 months).
Unit economics
- Average revenue per settled account: $749.
- Average debt per settled account: $7,492.
- Take rate: 10% of settlement value.
Competition / moat
- Named competitors: TrueAccord, Resolve, Tally.
- Relief differentiates on: mobile-first UX, full transparency (shows negotiated offers), open to any credit score, AI-driven settlement negotiation, community-based gifting program.
- Analogizes itself to Robinhood (brokerage), Earnin (payday loans), Credit Karma (credit monitoring) as a category-defining app in debt.
- Industry problem: incumbents have poor reputations, call-center-heavy sales tactics, fraud allegations (Freedom Debt Relief $25M FTC settlement cited).
- Creditor partnership (Bloom Acquisitions) provides proprietary deal flow for pilot.
Team & funding ask / use of funds
- Jason Saltzman - CEO.
- Ram Berrouet - COO.
- Bryan Okeke - CTO.
- Chris Thomas - Creative Director.
- Finlay Kersaint - Finance.
- Advisors: Jeffery Hartman (Bloom Acquisitions), Jeffrey D. Silberman & Maria Earley (ReedSmith - Legal & Compliance).
- Headline claim: "20+ years of debt and development experience".
- Ask: $1.7M via convertible note.
- Use of funds: support operations through 12 months and reach profitability.
Recommended financial model
- Archetype + why: Transaction-volume / marketplace fee model. Relief earns a per-settlement success fee; the correct model structure is: enrolled clients → settled clients (settlement rate) × avg. settlement amount × 10% take rate = revenue. This mirrors a marketplace / debt-settlement agency model, not SaaS (no subscription) and not a 3-statement manufacturing P&L. A simplified single-entity P&L with volume build-out is appropriate.
- Forecast horizon & granularity: Monthly for Year 1 (2021, pilot/ramp), then quarterly for Years 2–4 (2022–2024) to match the deck's stated projection window.
- Key drivers & assumptions:
| Driver | Value / Basis |
|---|---|
| Avg. settlement amount per client | $7,492 |
| Take rate (service fee) | 10% |
| Avg. revenue per settlement | $749 |
| Total addressable enrolled pipeline (pilots) | 5.2M (2.5M Bloom + 2.7M mailing list) |
| Settlement conversion rate (enrolled → settled) | 5–10%; industry benchmark; not in deck |
| Monthly new client enrollments | Ramp from ~500/mo in Q1 2021 to scale, reverse-engineered from ~$30–40M revenue target by EOY 2022 |
| Avg. time from enrollment to settlement | 12–24 months; typical for debt settlement programs |
| Revenue recognition timing | Recognized at settlement completion, not at enrollment |
| CAC - digital/influencer channel | $50–$150/user; no data in deck |
| Gross margin | 60–70%; success-fee businesses are high-margin; ops costs (negotiators, tech, compliance) not disclosed |
| Headcount / opex | Seed-stage; ~10–20 FTEs; $1.7M raise implies ~12 months of burn |
| Monthly burn rate | ~$140K/mo ($1.7M ÷ 12 months) |
- Scenarios (Base / Bull / Bear):
- Flex variables: enrollment ramp rate, settlement conversion rate, take rate, CAC.
- Bear: slow creditor partner onboarding, 3% settlement rate, higher CAC.
- Base: 5–7% settlement rate, 10% take rate, steady ramp via Bloom partnership.
- Bull: 10%+ settlement rate, additional creditor partnerships, faster user adoption from mailing lists.
- Required sheets / outputs:
- Assumptions - all drivers listed above with toggles for scenarios.
- Volume Build - monthly: new enrollments, active pipeline (enrolled not yet settled), settlements completed.
- Revenue - settlements × avg. fee; monthly/quarterly revenue.
- P&L - revenue, COGS (negotiation ops, compliance), gross profit, OpEx (tech, marketing, G&A), EBITDA.
- Cash Flow & Runway - starting from $1.7M raise, monthly burn, cash balance, months to profitability.
- Market Penetration - SAM ($695B) → enrolled → settled; shows % capture to sanity-check revenue projections.
- Projected Revenue summary chart (2021–2024, matches deck slide 13).
Frequently asked
Is the Relief financial model free?+
Yes. The Relief model is a free Excel (.xlsx) download with live formulas. Sign up with your email and the workbook is yours to keep, review, and edit.
What's included in the model?+
A 5-year monthly forecast with P&L, cash flow and runway, valuation (exit multiple plus a DCF cross-check), MOIC/IRR returns, and unit economics, with live formulas throughout.
How was this model built?+
It was built from Relief's pitch deck and publicly available information, then structured to investment-banking standards as a fully editable Excel model.
Can I change the assumptions?+
Yes. You can change assumptions and the live formulas will recalculate in the downloadable Excel model.
Have more financial modelling questions? Contact us

Created by ex-finance professionals
Hey, I’m Alex and I created Finamodel.
Over my years in the finance industry I kept building the same models over and over again. Same structure, same assumptions, different logo. So I started building frameworks to turn them into clean, reusable templates.
Every model here is one I’d actually use for a client, and I personally vet each one before it goes up.
I’m not an expert in every industry, but I’ve built enough models to know what belongs in one. And when something is completely foreign to me, I reach out to my network for experts to work on our models with us.
Having a template library on hand cuts a first build from hours to minutes.
Need help finding your model? You’ll find me in the Finamodel app!
Other Fintech Startup Financial Models
Browse another startup in the same category.
Acin
SaaS and data subscription network for operational risk management at Tier 1 financial institutions

Ageras Group
B2B SME ecosystem - marketplace connecting SMEs with accountants + cloud accounting/payroll software + embedded financial services (lending, factoring, banking)

Airbase
Unified non-payroll spend management platform (corporate cards, AP/bill pay, expense reimbursement, approval workflows) for mid-market companies.

Altruist
Vertically integrated all-in-one platform for registered investment advisors (RIAs) - combining custodial, portfolio management, practice management, and client acquisition tools.
Amenitiz
All-in-one hotel management SaaS platform ("Shopify for hotels") for independent hoteliers - PMS, booking engine, channel manager, website builder, payments, and AI-driven revenue management.

Anrok
SaaS sales tax compliance platform - nexus monitoring, calculation, registration, filing, and remittance - built specifically for SaaS companies.
Arrival
Arrival is an EV manufacturer of commercial vans and buses using proprietary Microfactories and vertically integrated components, going public via SPAC merger with CIIG Merger Corp.

AtoB
AtoB is building financial infrastructure for commercial fleets, starting with a no-fee Visa fleet card for fuel and expanding into payroll, BNPL, and international.


